Noranda Aluminum — Investor Presentation (November 2010)
28 slides from Noranda Aluminum's investor presentation, Nov 2, 2010
Slide 1: Noranda Aluminum Holding Corporation—November 2010
Exhibit 99.1 NORANDA ALUMINUM HOLDING CORPORATION—NOVEMBER 2010
Slide 2: President and Chief Executive Officer; Chief Financial Officer
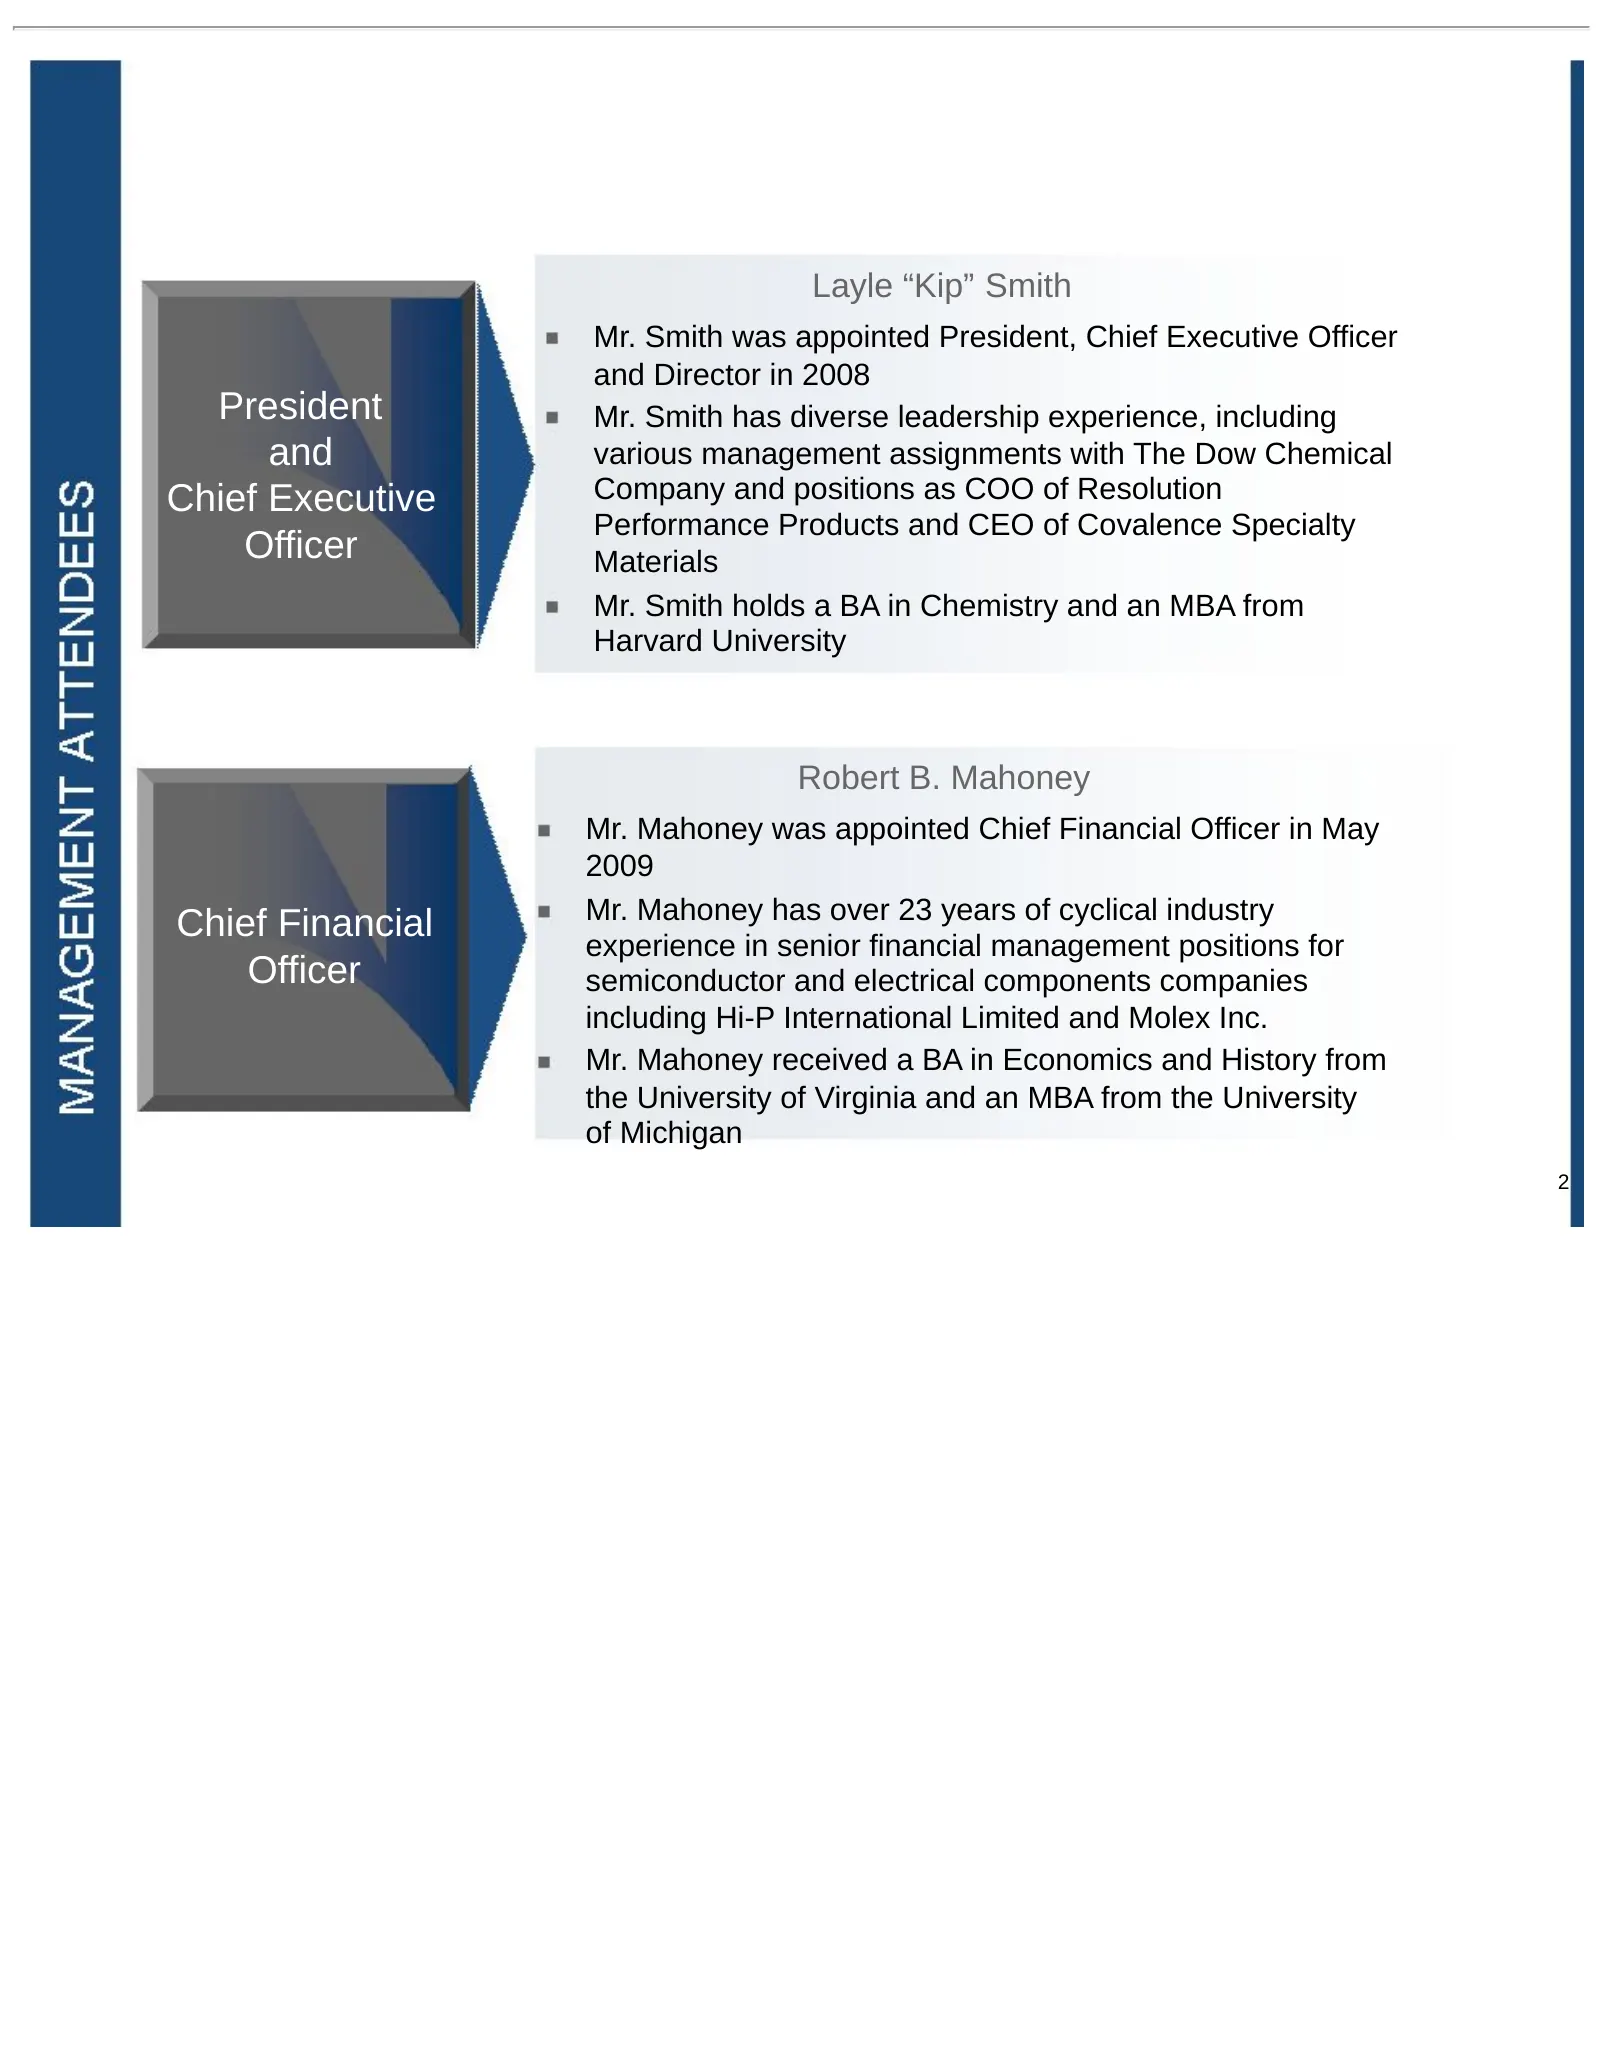
Layle “Kip” Smith Mr. Smith was appointed President, Chief Executive Officer and Director in 2008 President Mr. Smith has diverse leadership experience, including and various management assignments with The Dow Chemical Chief Executive Company and positions as COO of Resolution Performance Products
Slide 3: Forward Looking Statements
Forward Looking Statements The following information contains, or may be deemed to contain, "forward-looking statements" (as defined in the U.S. Private Securities Litigation Reform Act of 1995). By their nature, forward-looking statements involve risks and uncertainties because they relate to event
Slide 4: Noranda's Integrated Footprint
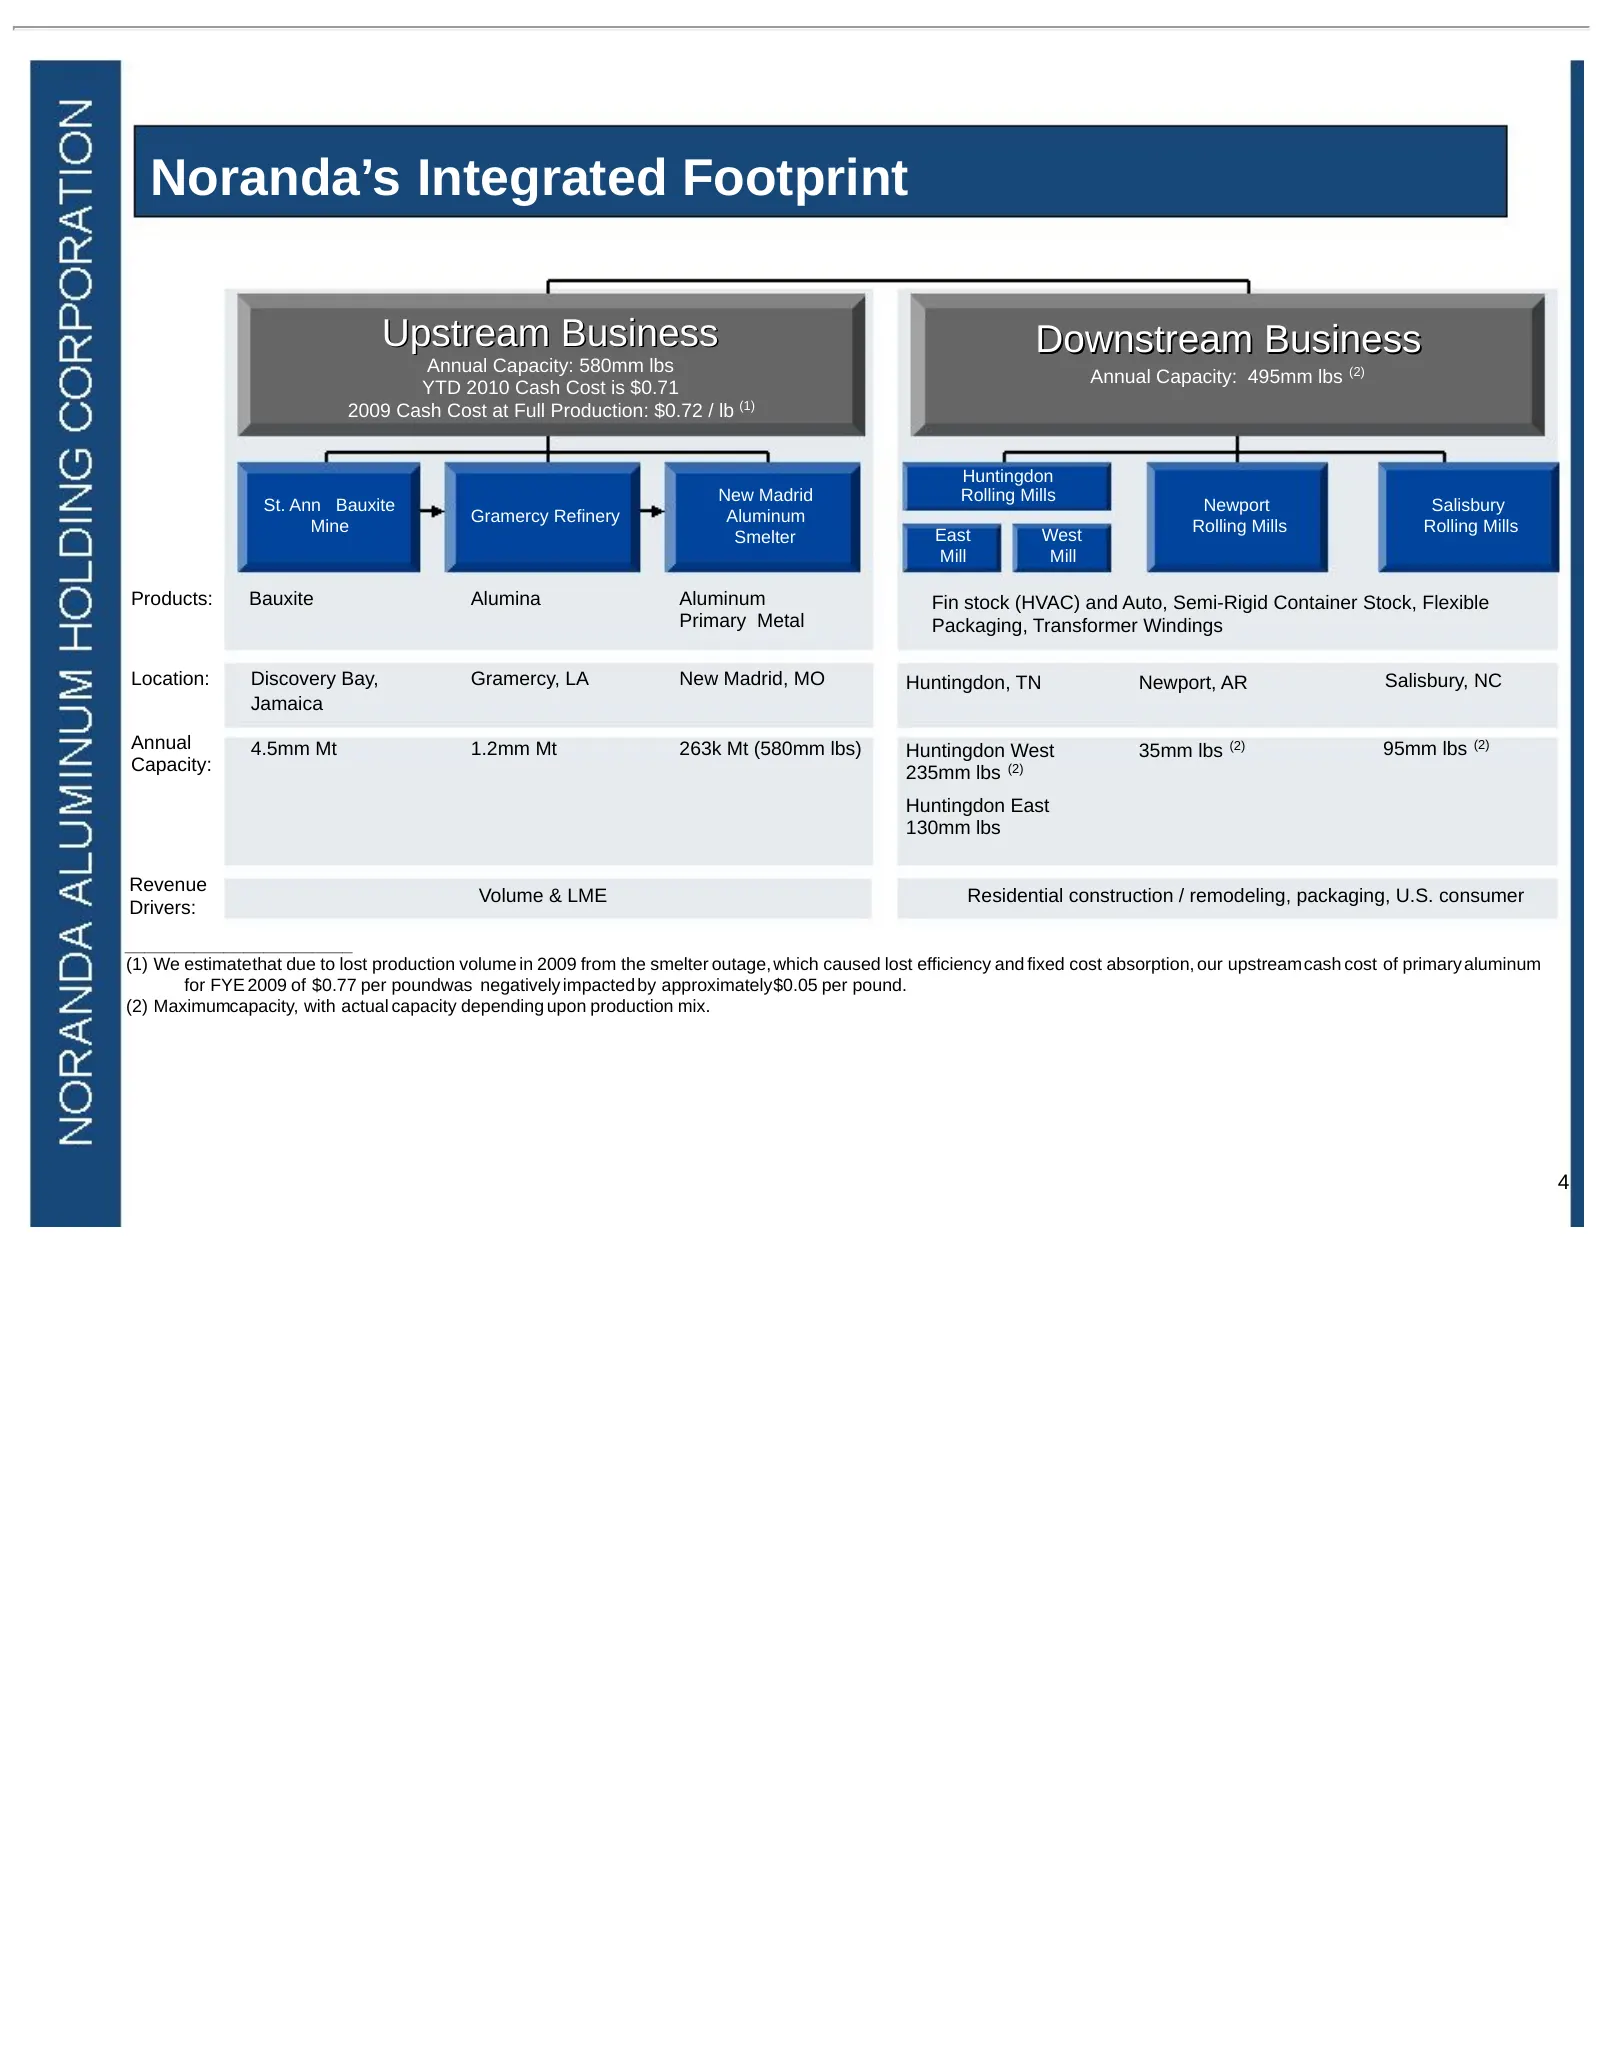
Noranda’s Integrated Footprint Upstream Business Downstream Business Annual Capacity: 580mm lbs Annual Capacity: 495mm lbs (2) YTD 2010 Cash Cost is $0.71 2009 Cash Cost at Full Production: $0.72 / lb (1) Huntingdon New Madrid Rolling Mills St. Ann Bauxite Newport Salisbury Gramercy Refinery Aluminu
Slide 5: Key Messages
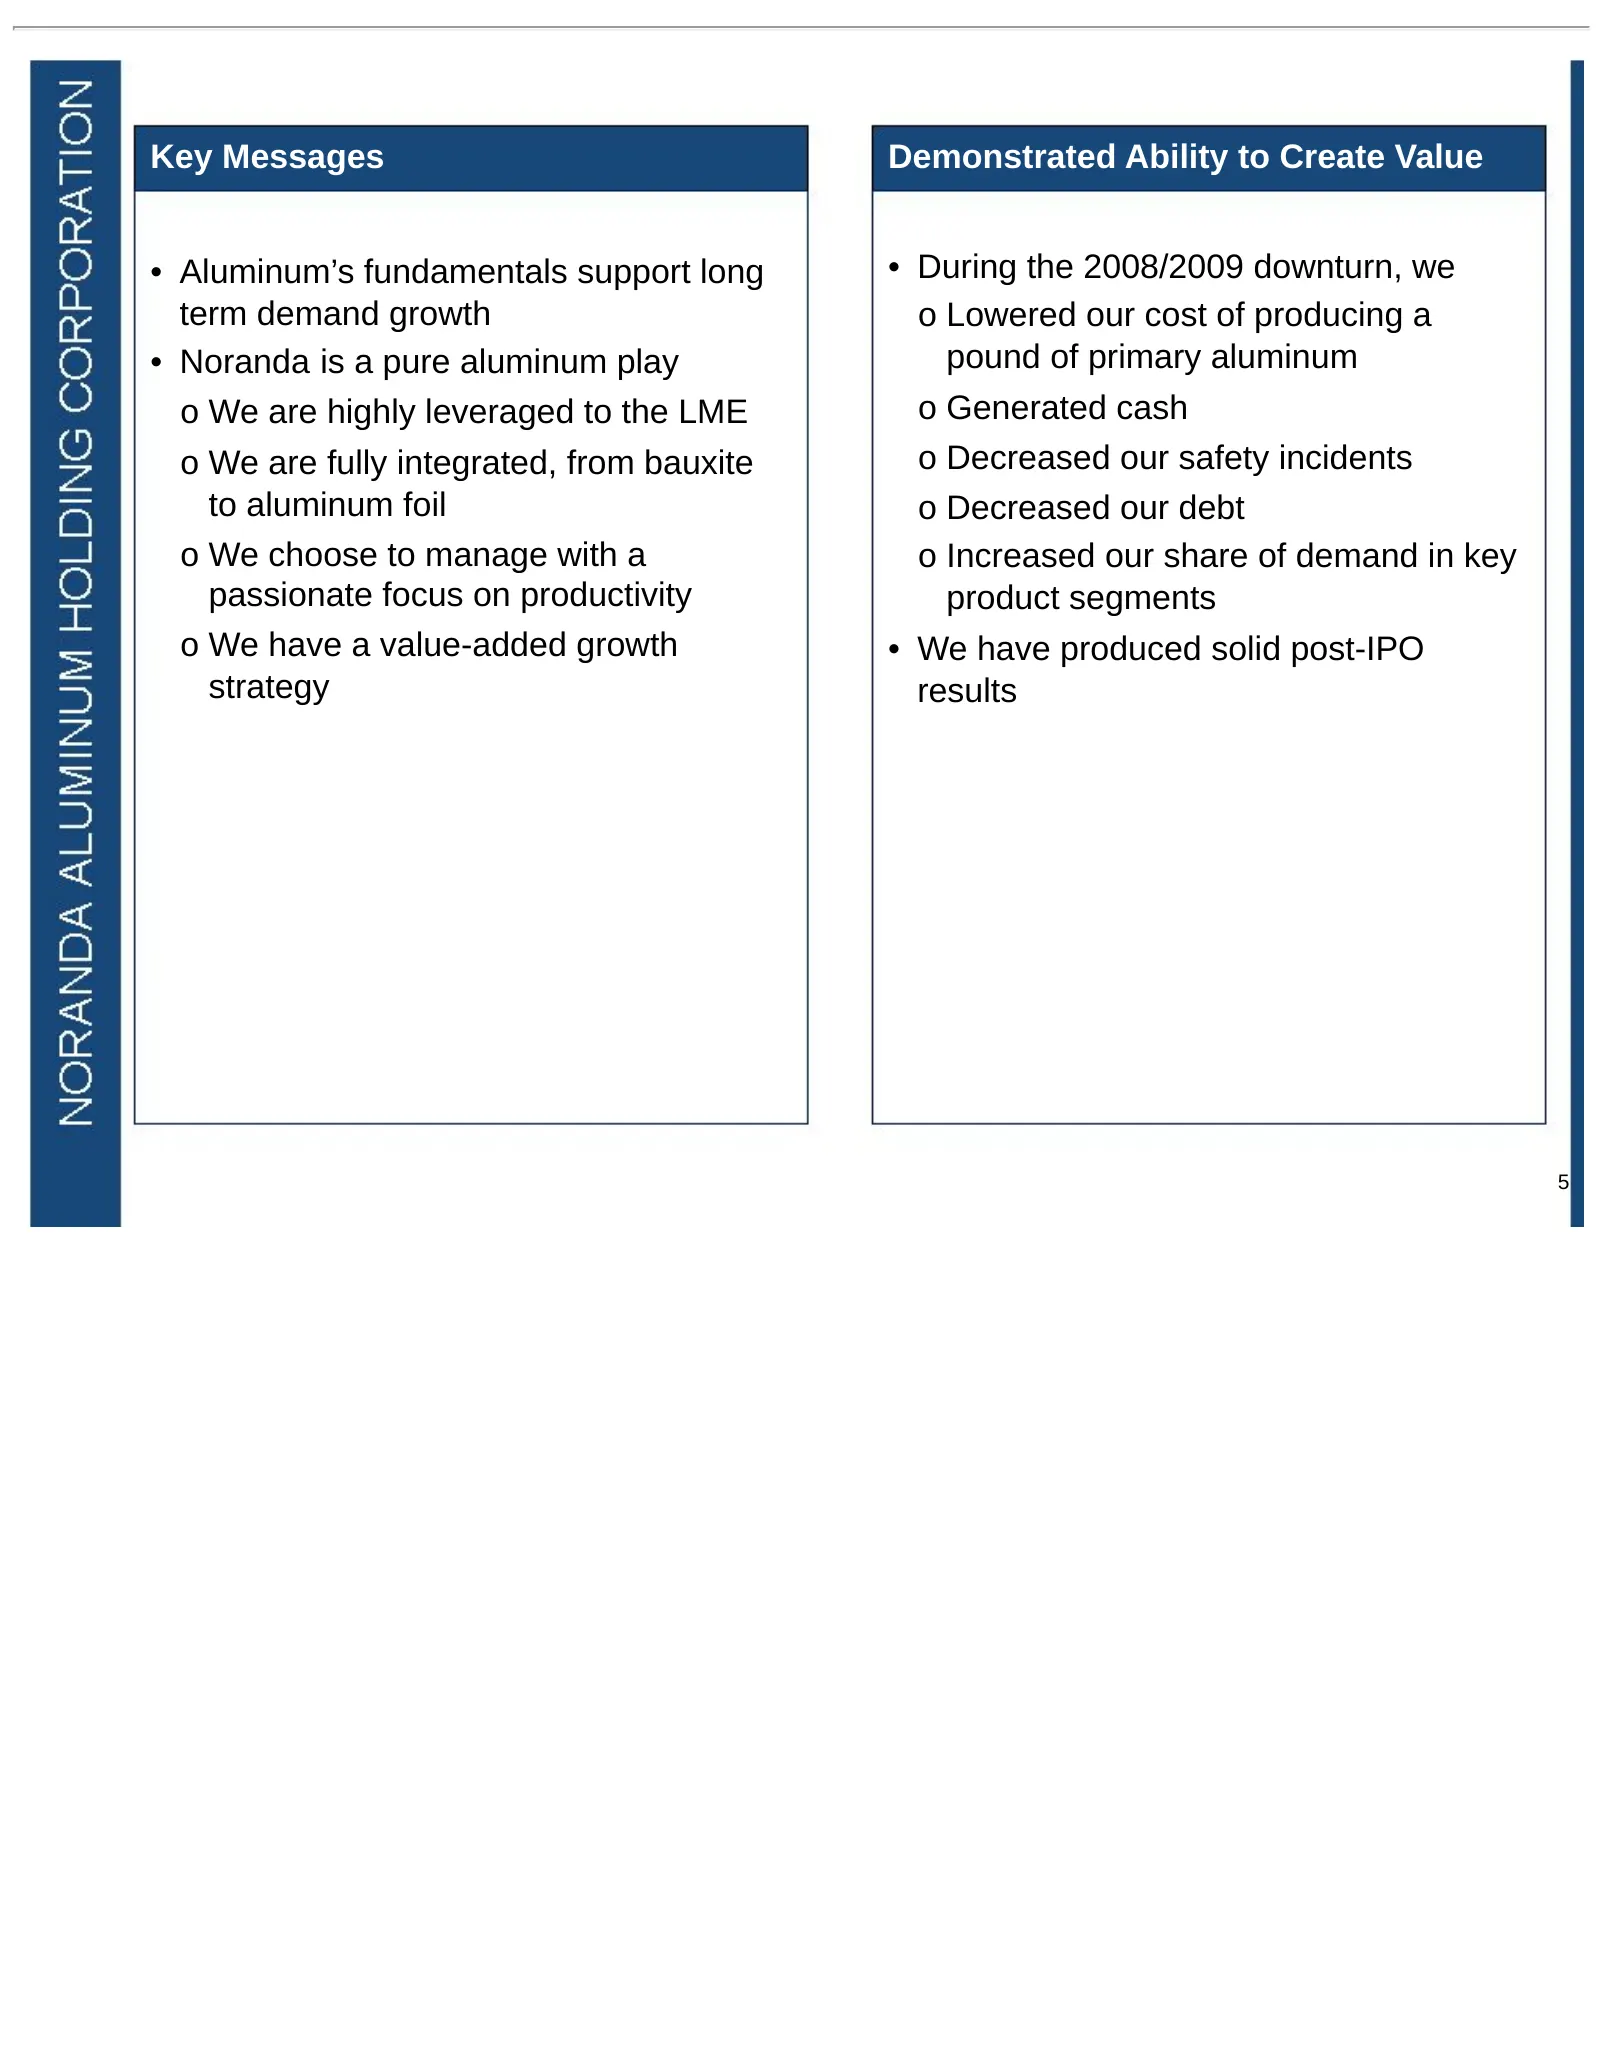
Key Messages Demonstrated Ability to Create Value • Aluminum’s fundamentals support long • During the 2008/2009 downturn, we term demand growth o Lowered our cost of producing a • Noranda is a pure aluminum play pound of primary aluminum o We are highly leveraged to the LME o Generated cash o We are
Slide 6: Noranda is well positioned for demand growth and a recovery in aluminum prices
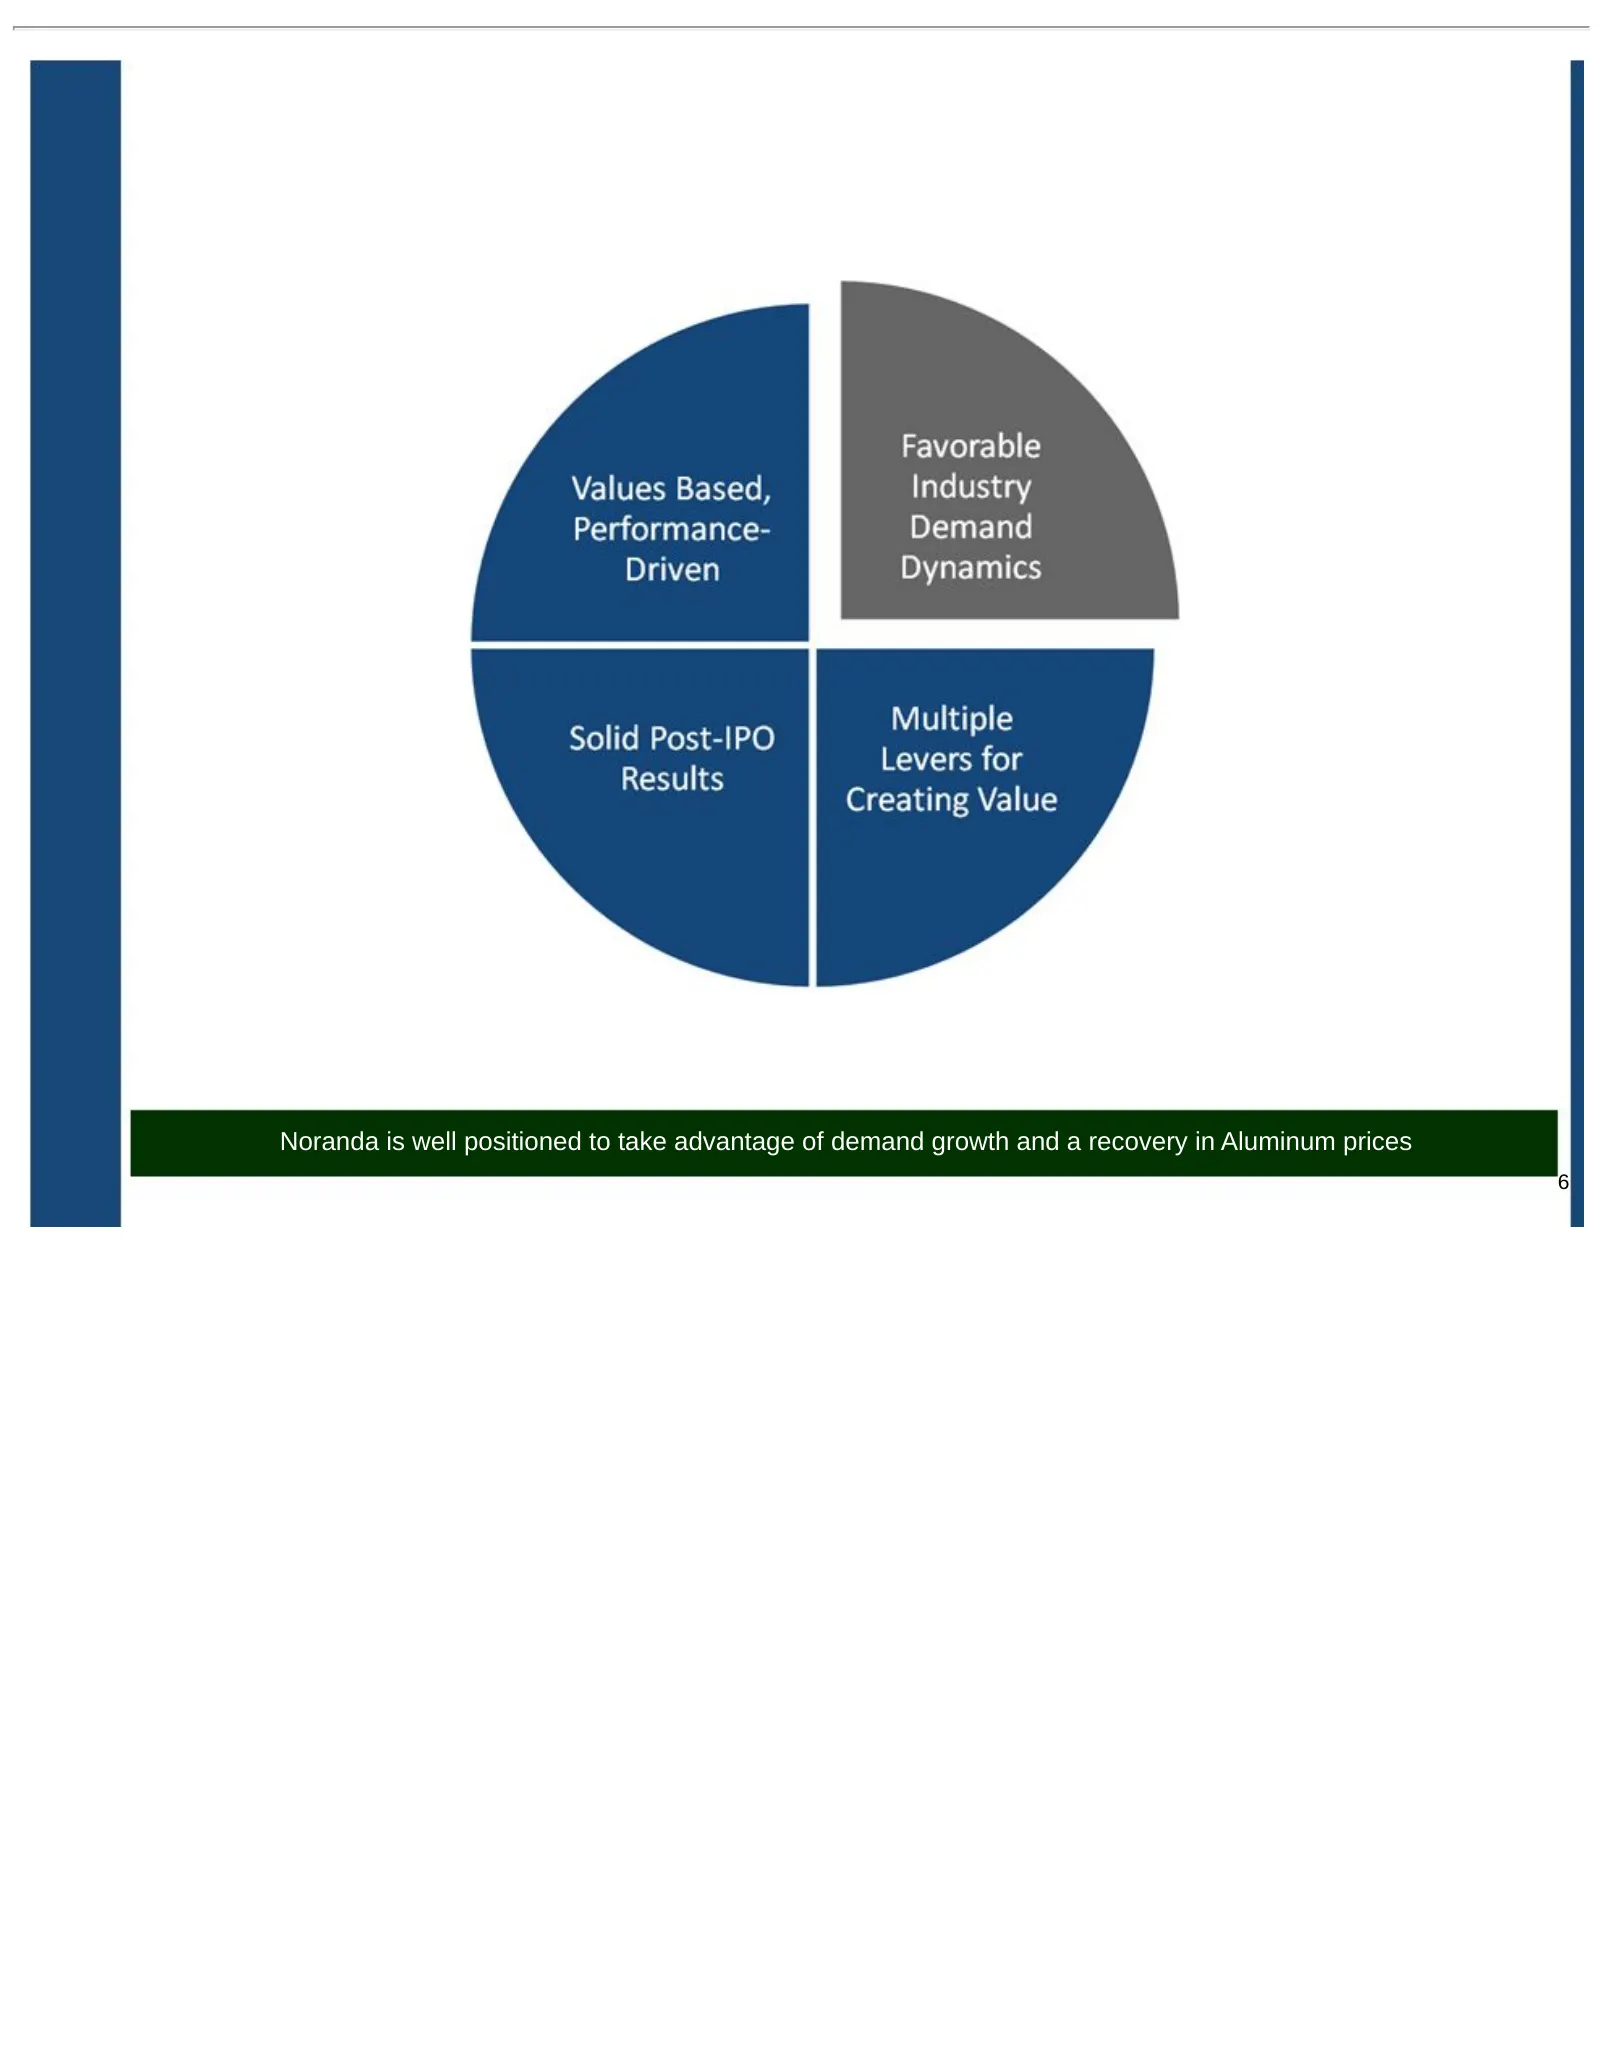
Noranda is well positioned to take advantage of demand growth and a recovery in Aluminum prices 6
Slide 7: We Hold a Positive Outlook For Aluminum
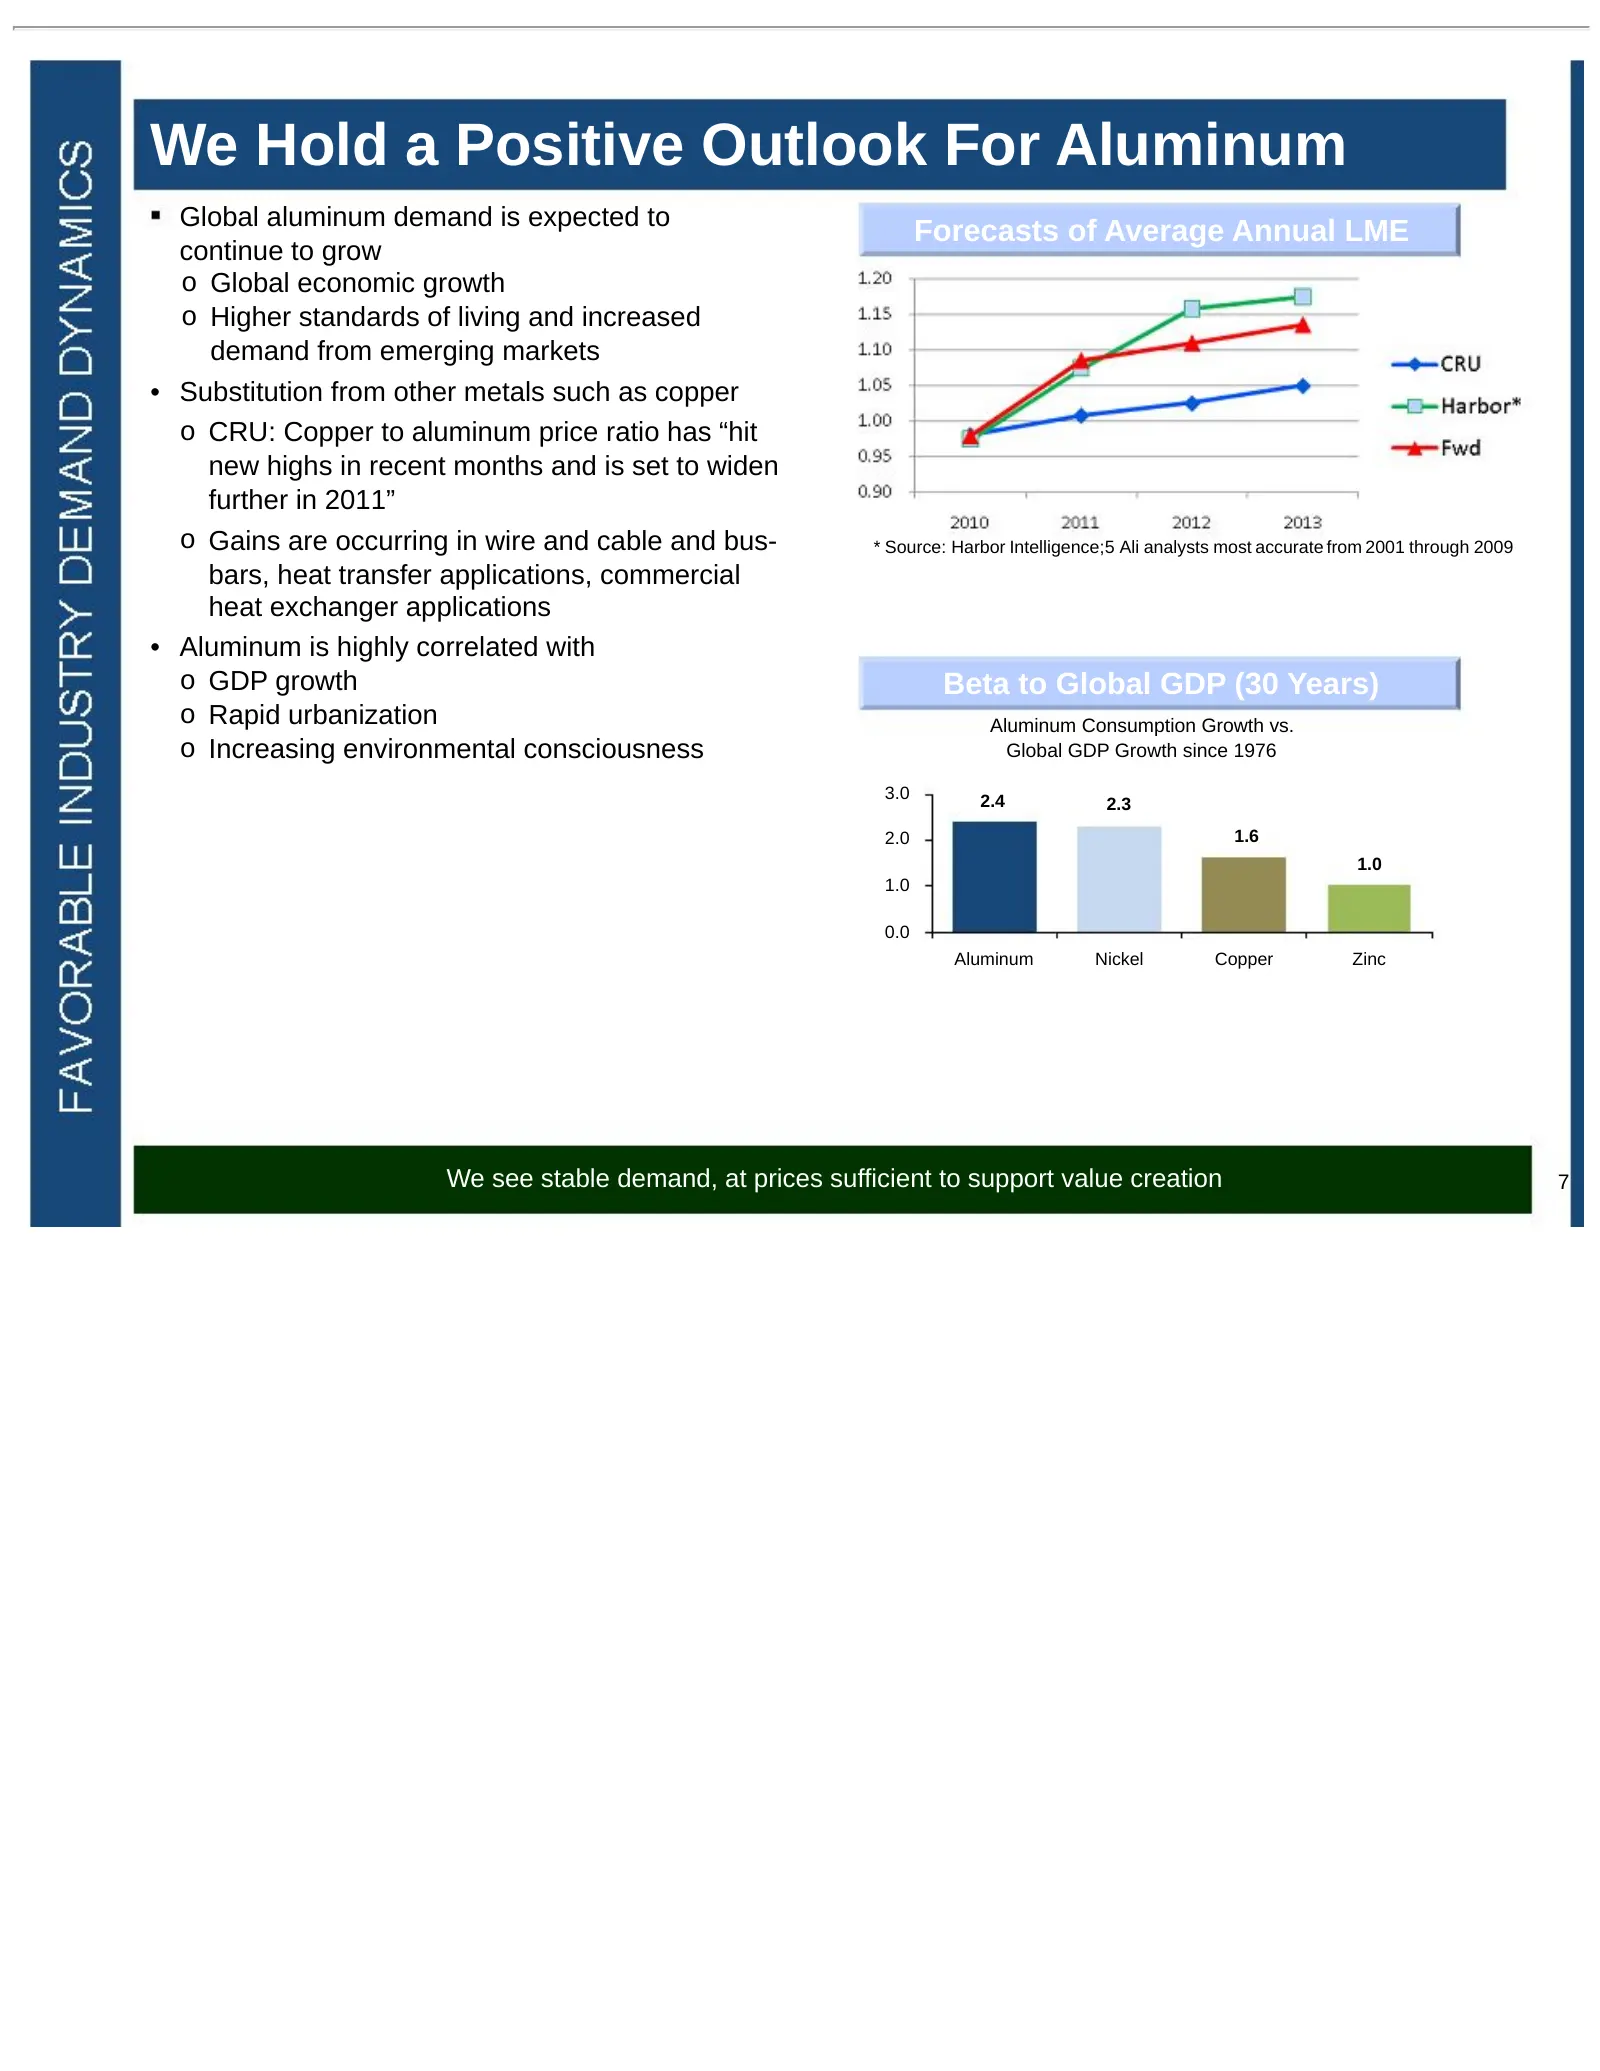
We Hold a Positive Outlook For Aluminum Global aluminum demand is expected to Forecasts of Average Annual LME continue to grow o Global economic growth o Higher standards of living and increased demand from emerging markets • Substitution from other metals such as copper o CRU: Copper to aluminum pr
Slide 8: We exercise significant control over the basic drivers of our success
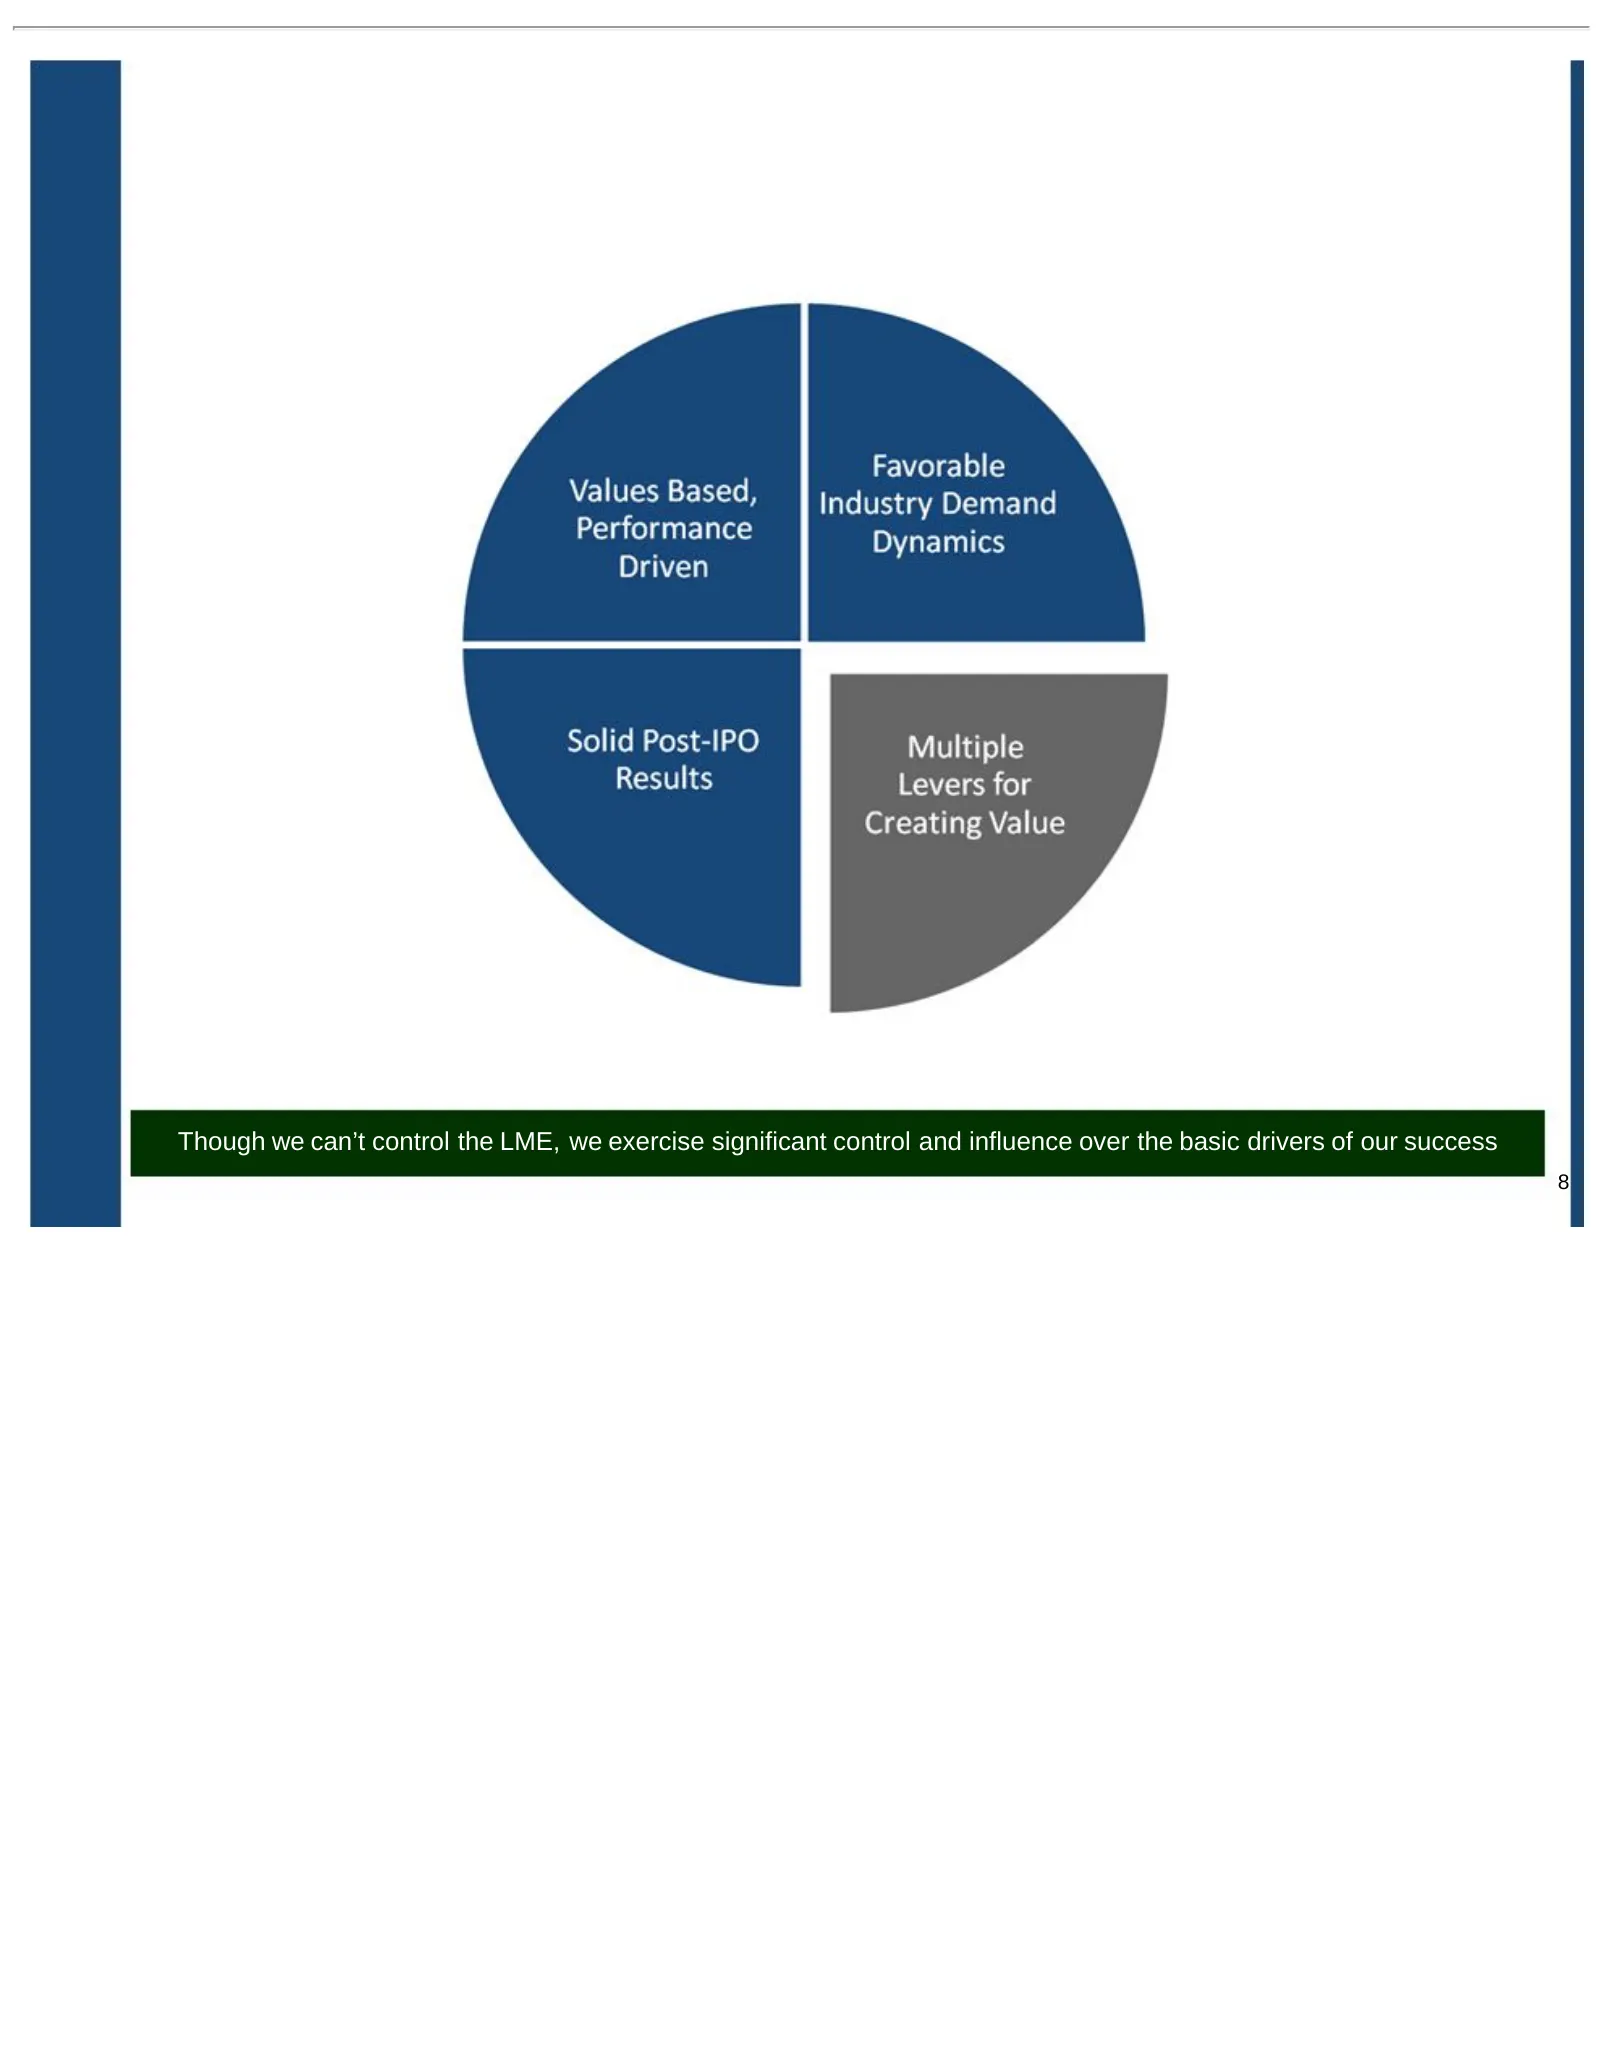
Though we can’t control the LME, we exercise significant control and influence over the basic drivers of our success 8
Slide 9: Vertically Integrated Upstream Business
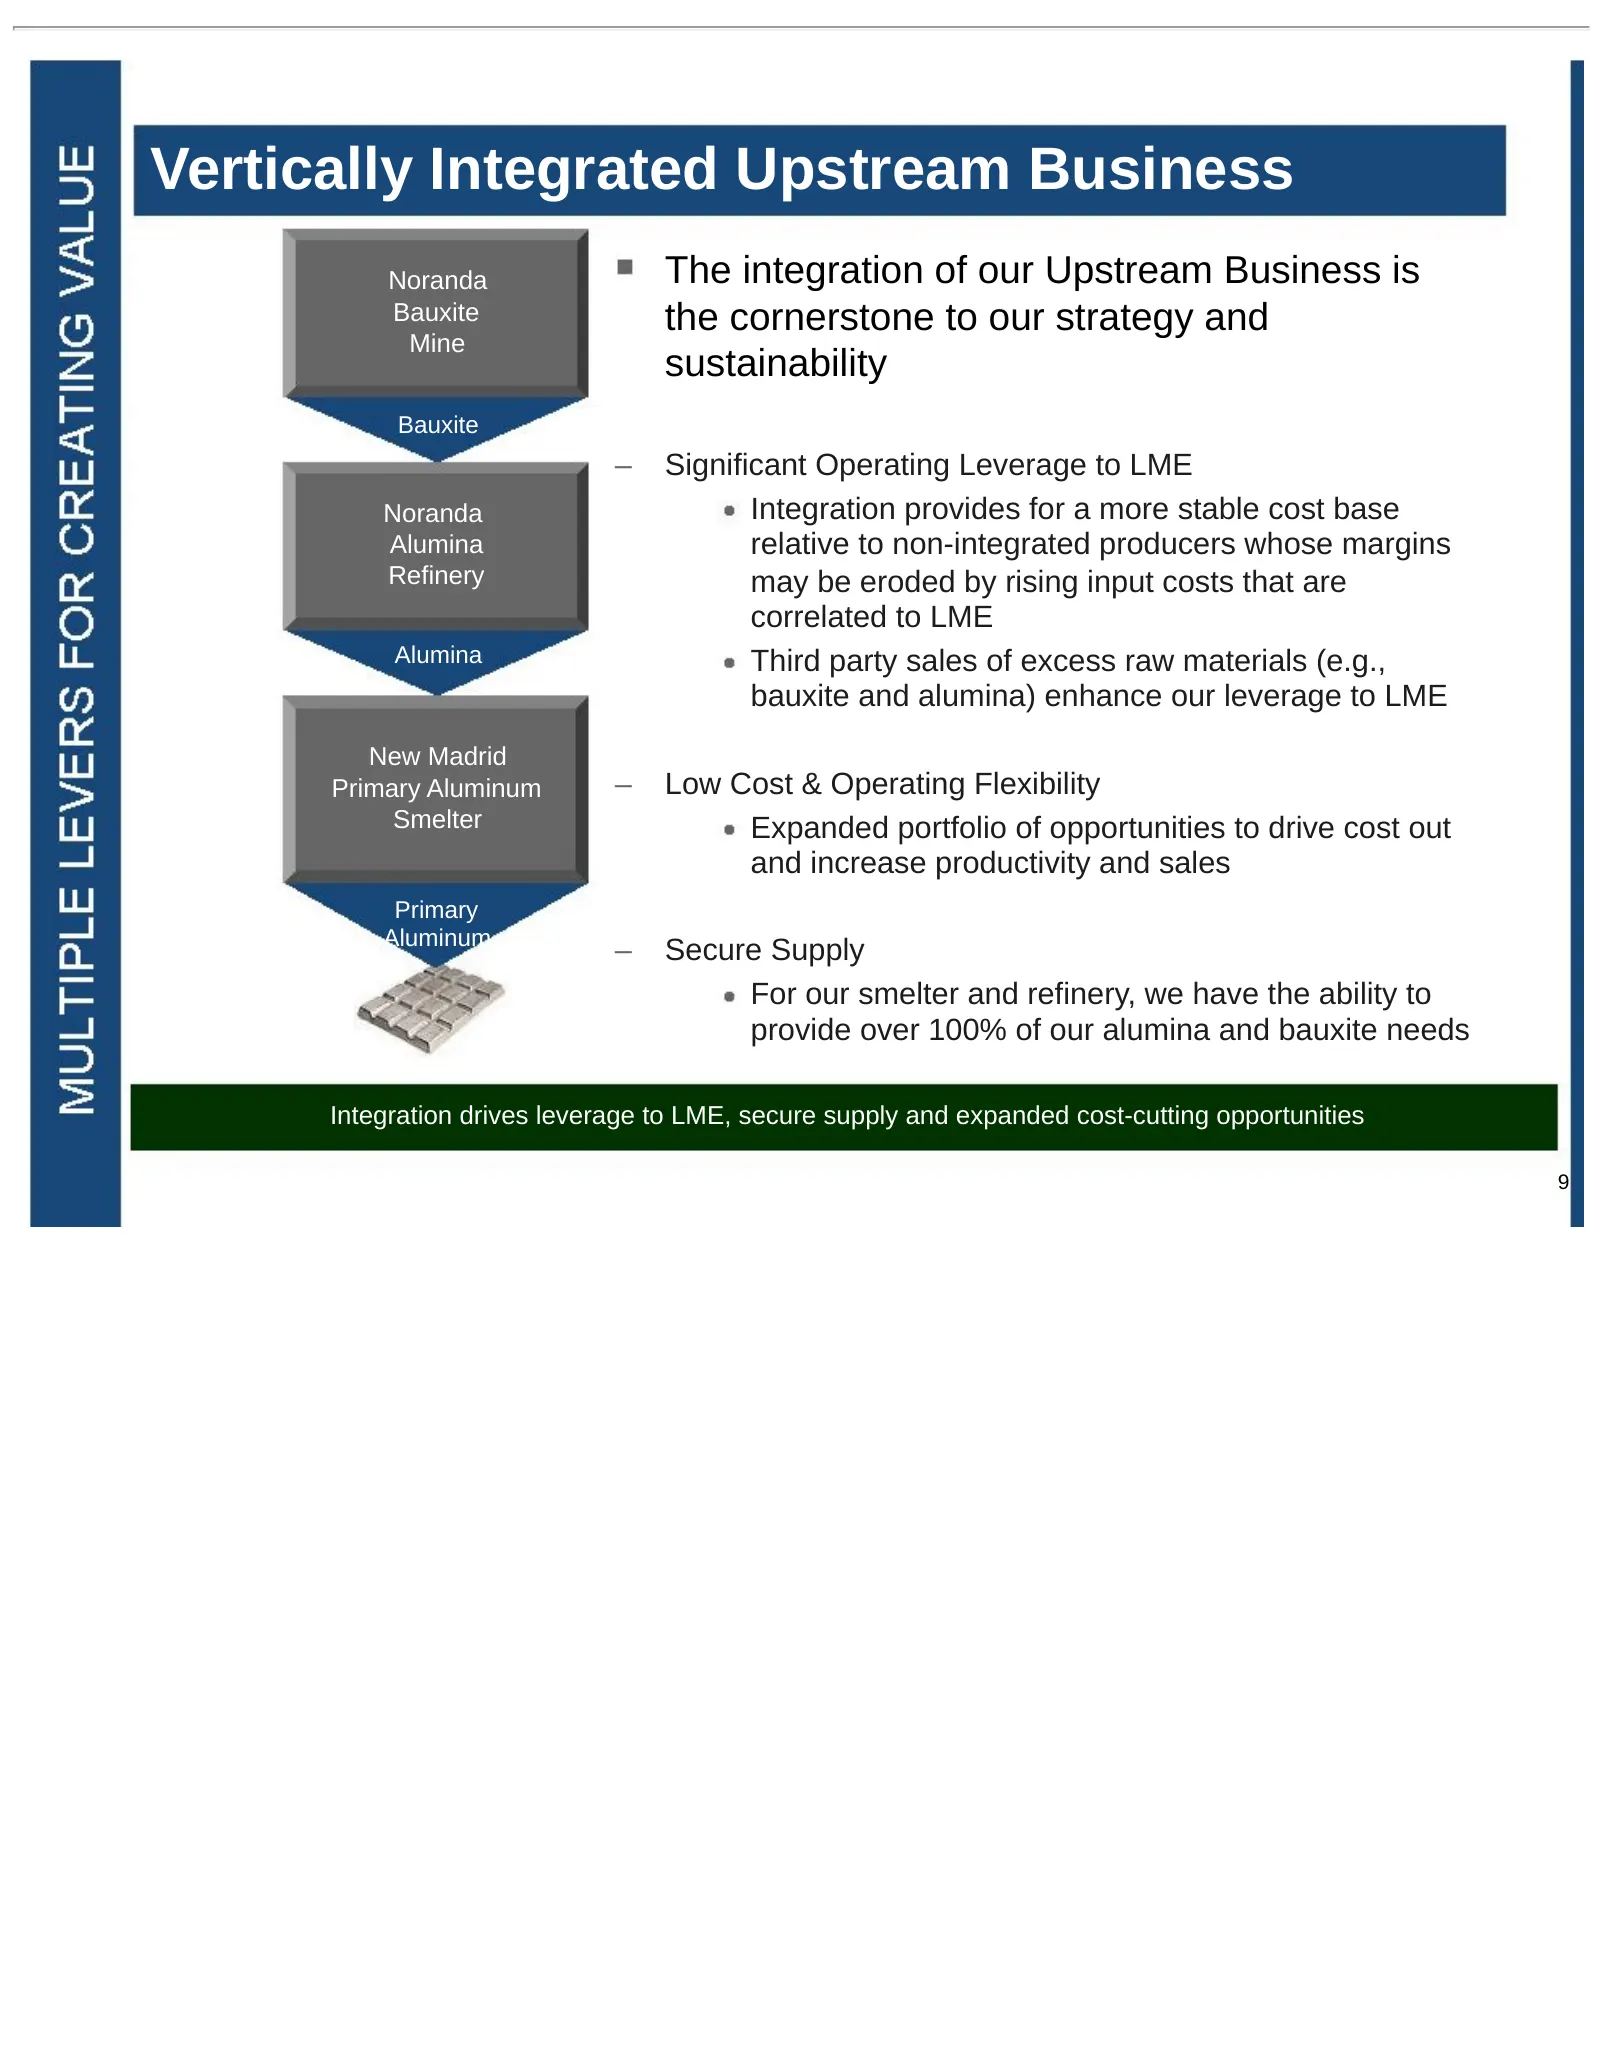
Vertically Integrated Upstream Business Noranda The integration of our Upstream Business is Bauxite the cornerstone to our strategy and Mine sustainability Bauxite – Significant Operating Leverage to LME Noranda Integration provides for a more stable cost base Alumina relative to non-integrated prod
Slide 10: YTD 2010 cash cost is $0.71/lb
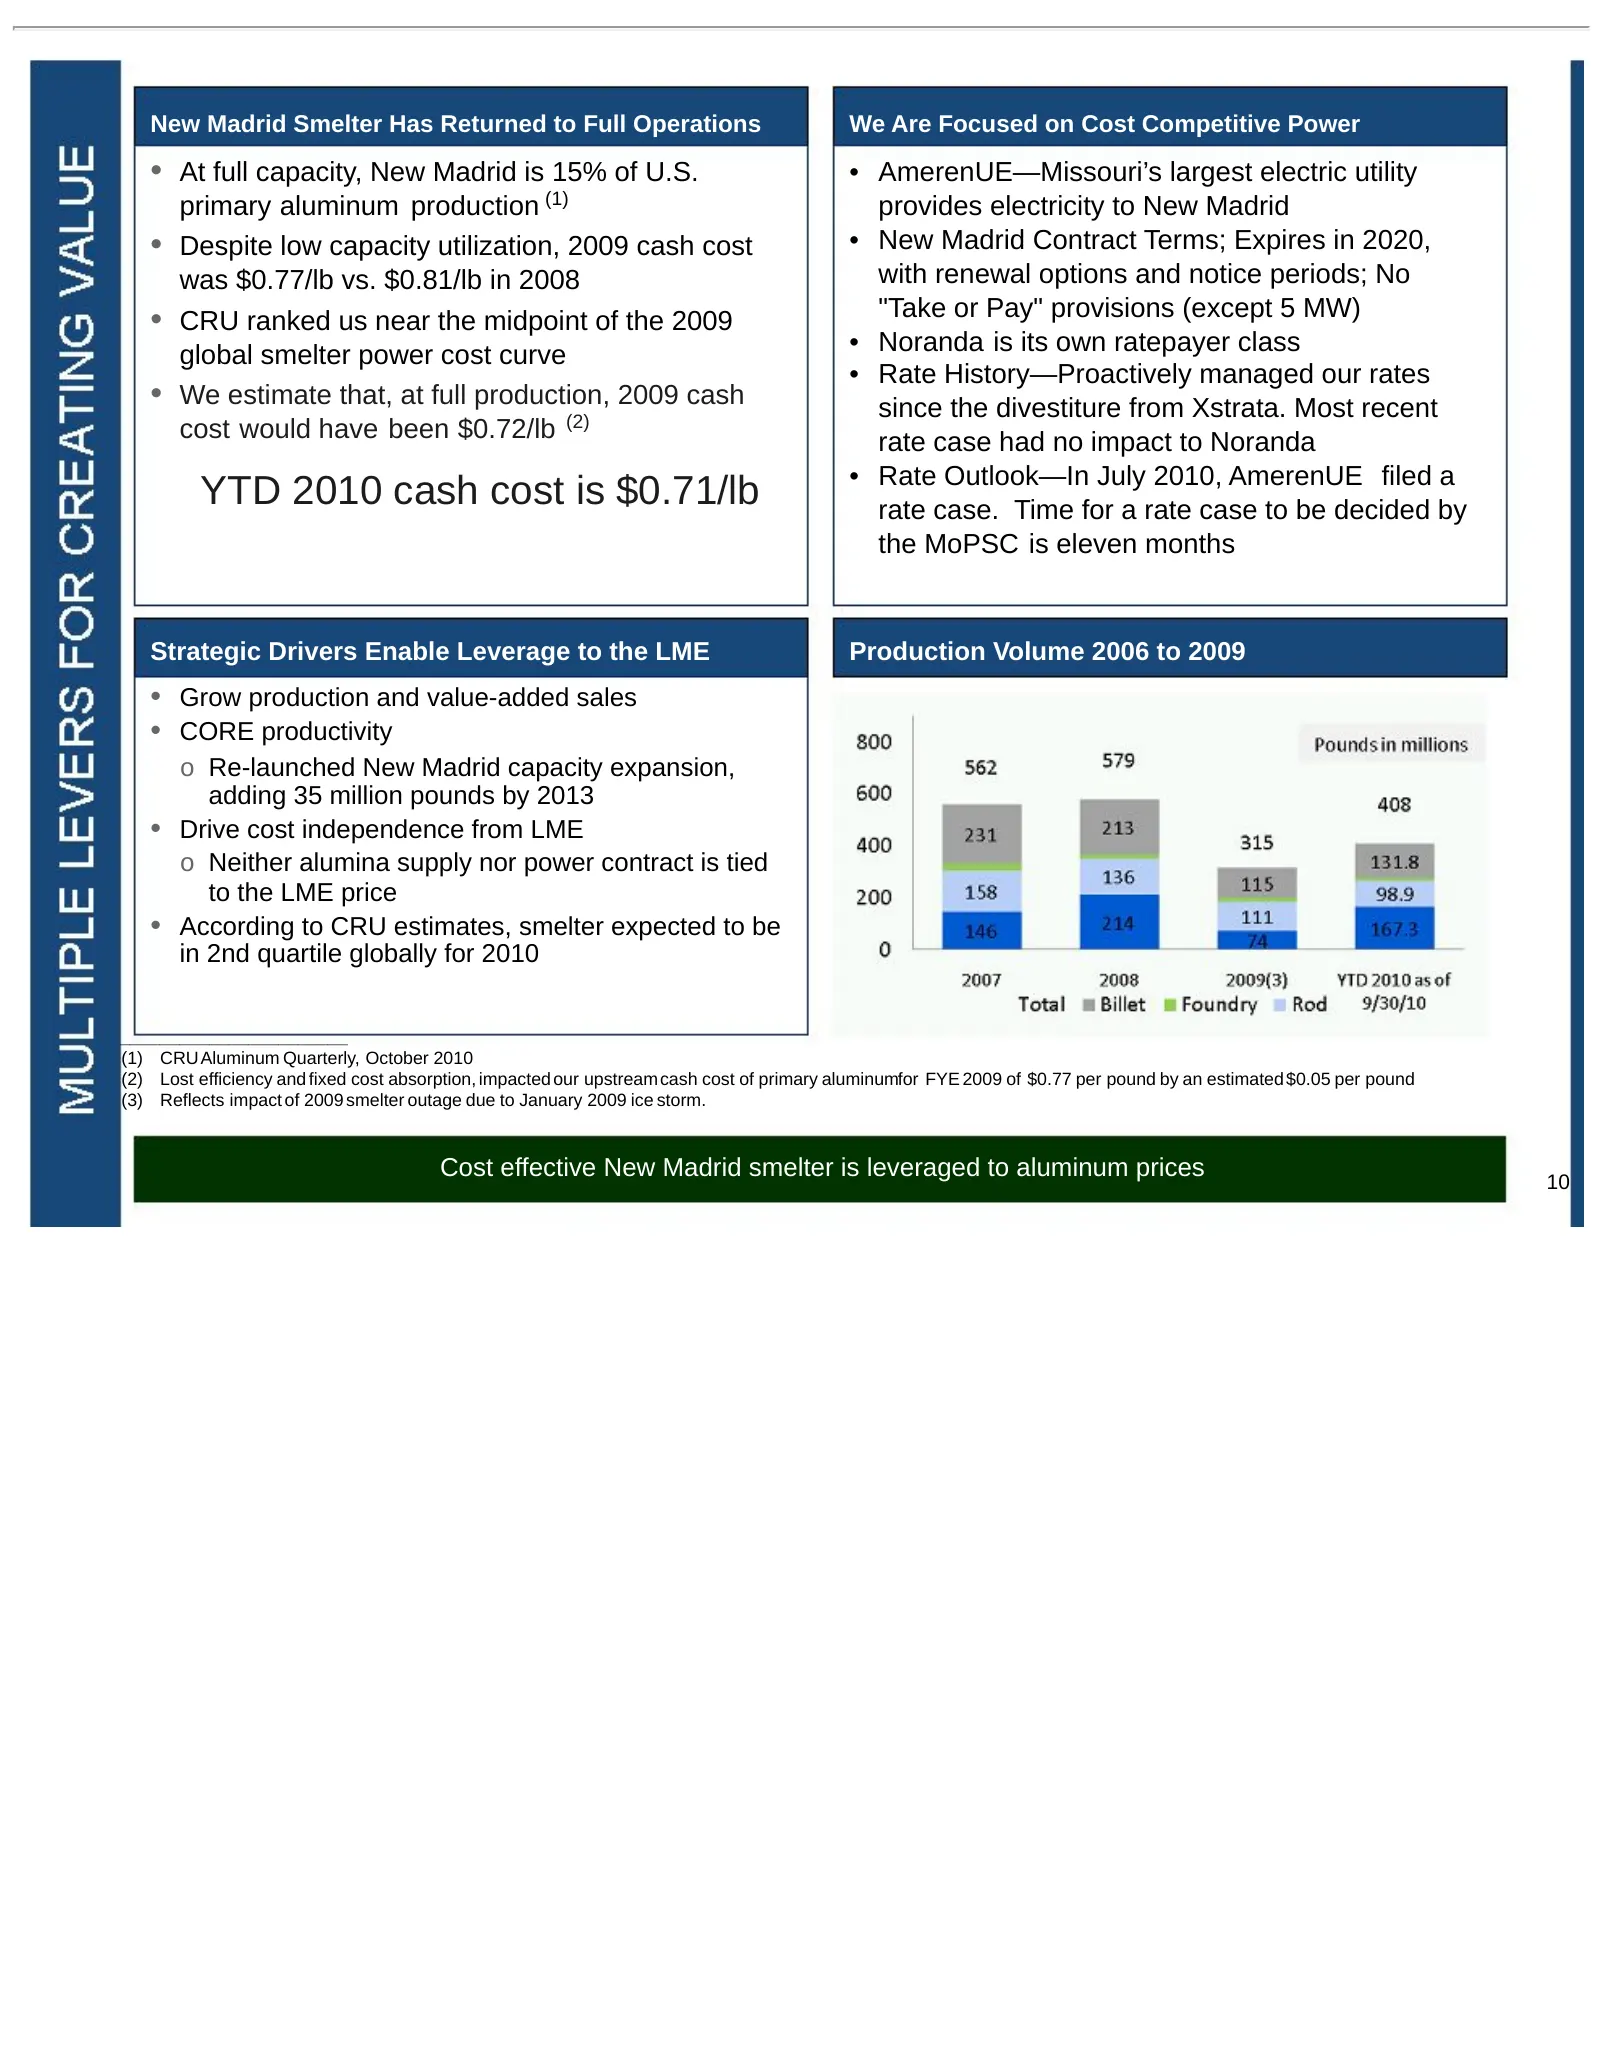
New Madrid Smelter Has Returned to Full Operations We Are Focused on Cost Competitive Power • At full capacity, New Madrid is 15% of U.S. • AmerenUE—Missouri’s largest electric utility primary aluminum production (1) provides electricity to New Madrid • Despite low capacity utilization, 2009 cash co
Slide 11: Low Cost, Leading Rolling Mill Operations
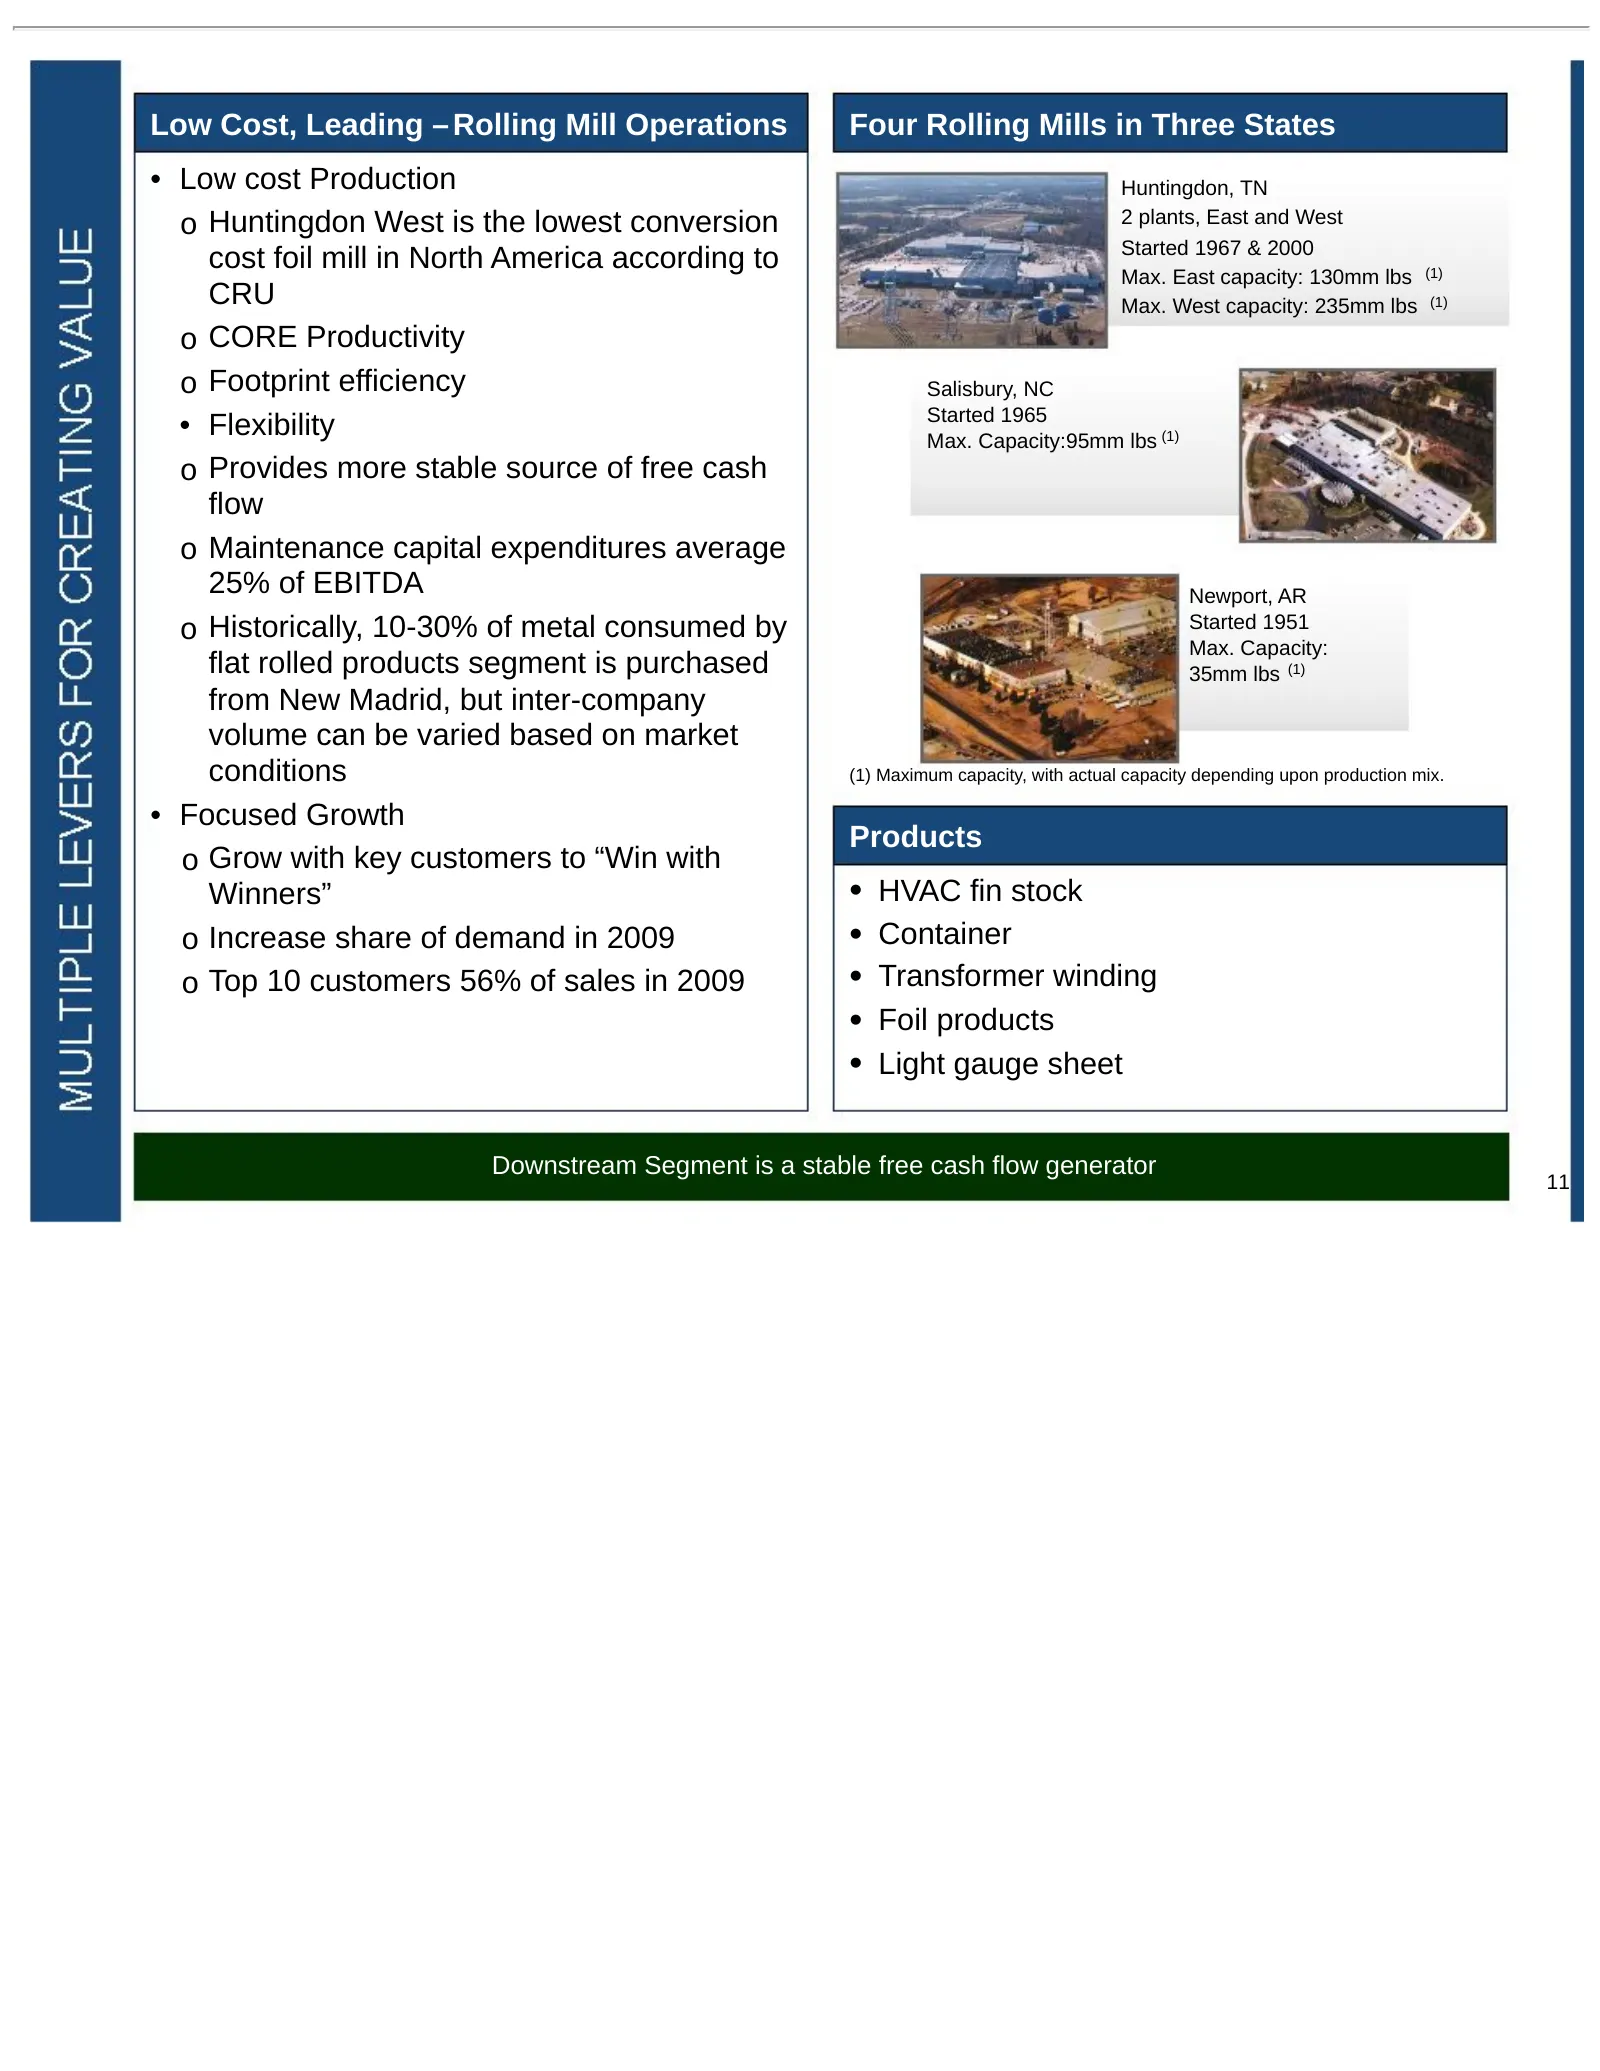
Low Cost, Leading – Rolling Mill Operations Four Rolling Mills in Three States • Low cost Production Huntingdon, TN o Huntingdon West is the lowest conversion 2 plants, East and West Started 1967 & 2000 cost foil mill in North America according to Max. East capacity: 130mm lbs (1) CRU Max. West capa
Slide 12: Strong Record of Productivity (CORE savings)
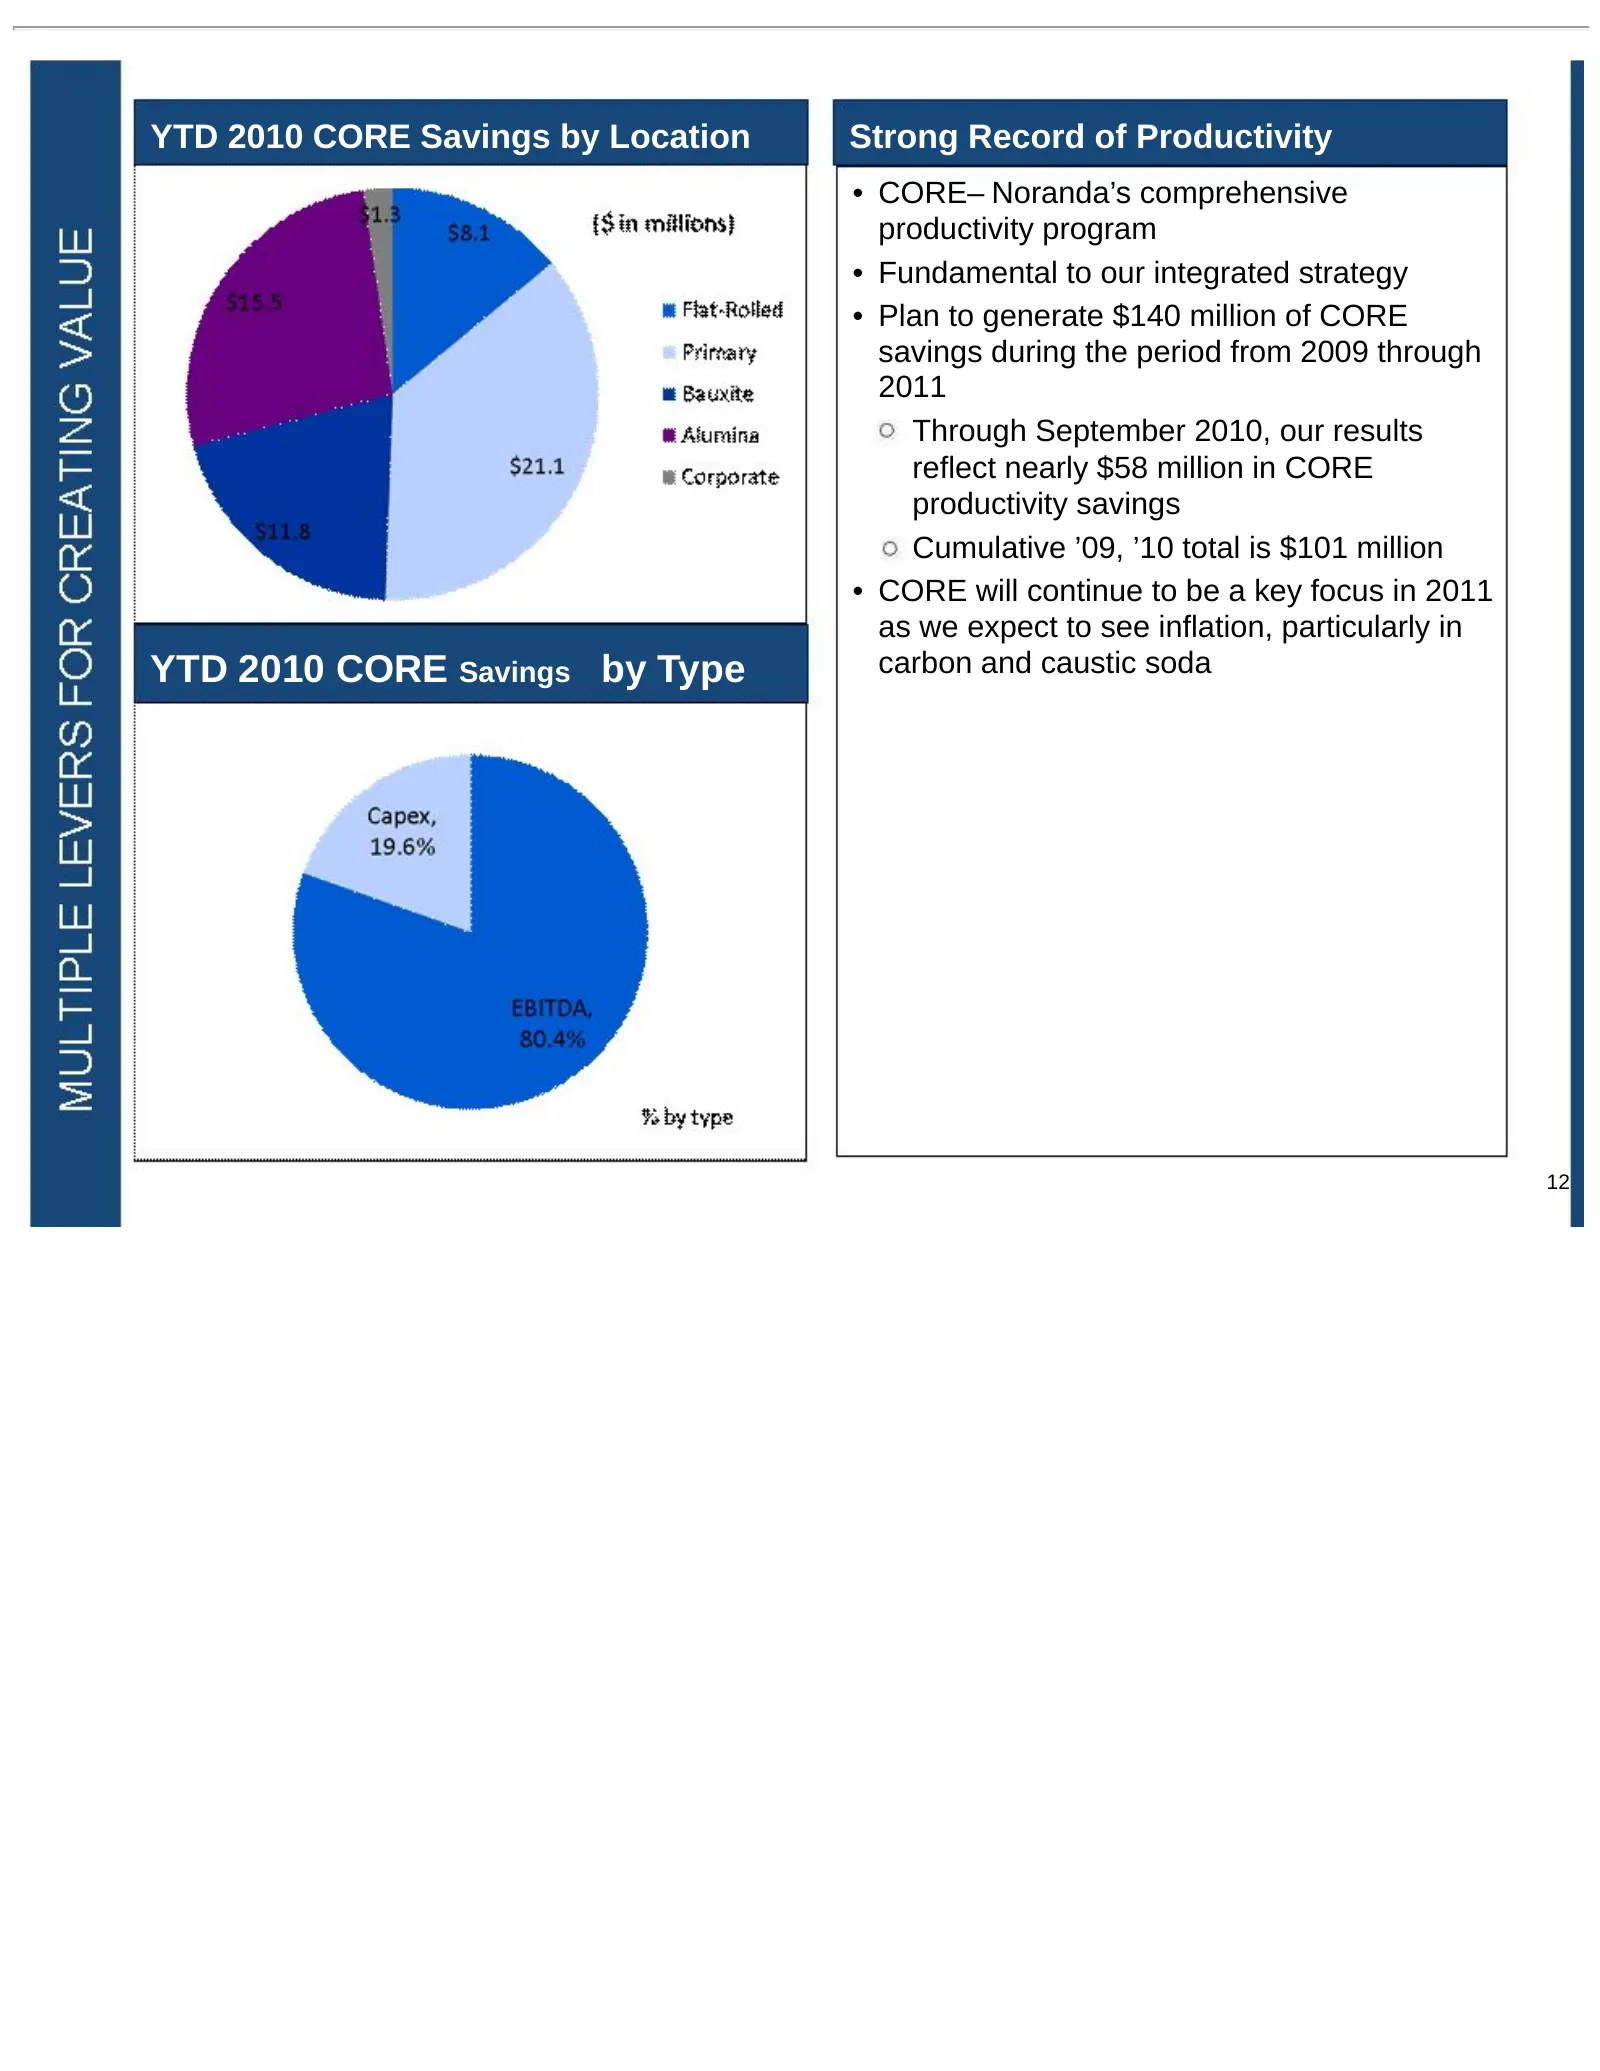
YTD 2010 CORE Savings by Location Strong Record of Productivity • CORE– Noranda’s comprehensive productivity program • Fundamental to our integrated strategy • Plan to generate $140 million of CORE savings during the period from 2009 through 2011 Through September 2010, our results reflect nearly $5
Slide 13: Track Record of Growth
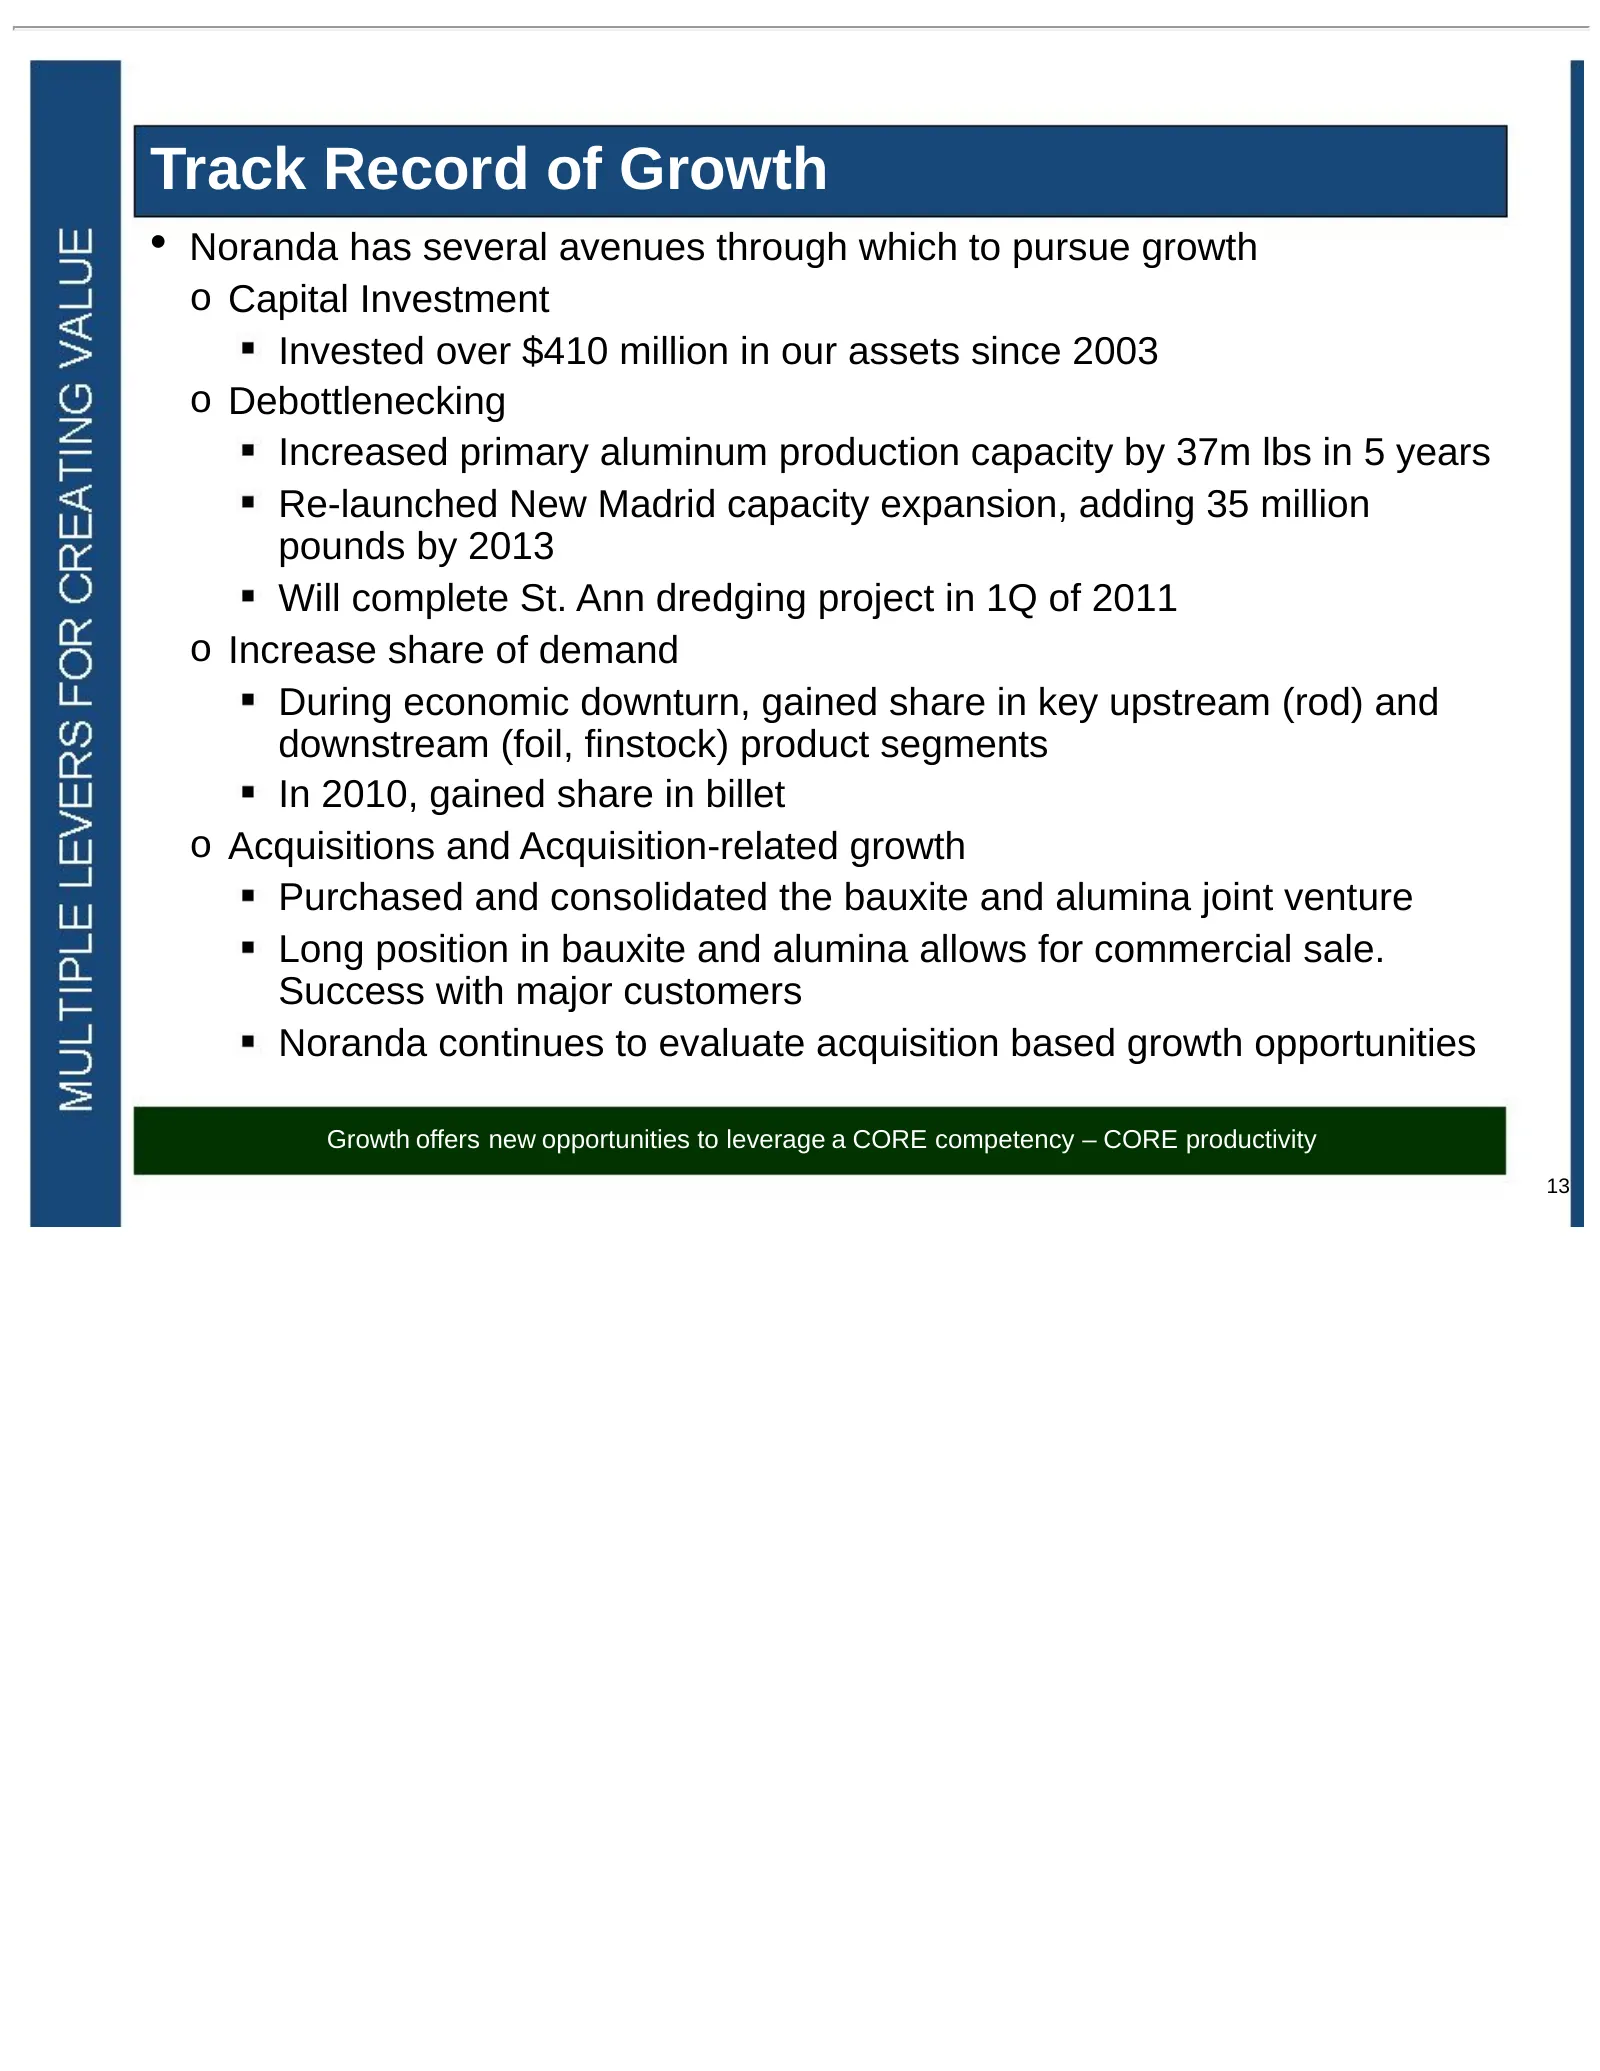
Track Record of Growth • Noranda has several avenues through which to pursue growth o Capital Investment Invested over $410 million in our assets since 2003 o Debottlenecking Increased primary aluminum production capacity by 37m lbs in 5 years Re-launched New Madrid capacity expansion, adding 35 mil
Slide 14: Debt Balances Trend; We Have Deleveraged Substantially
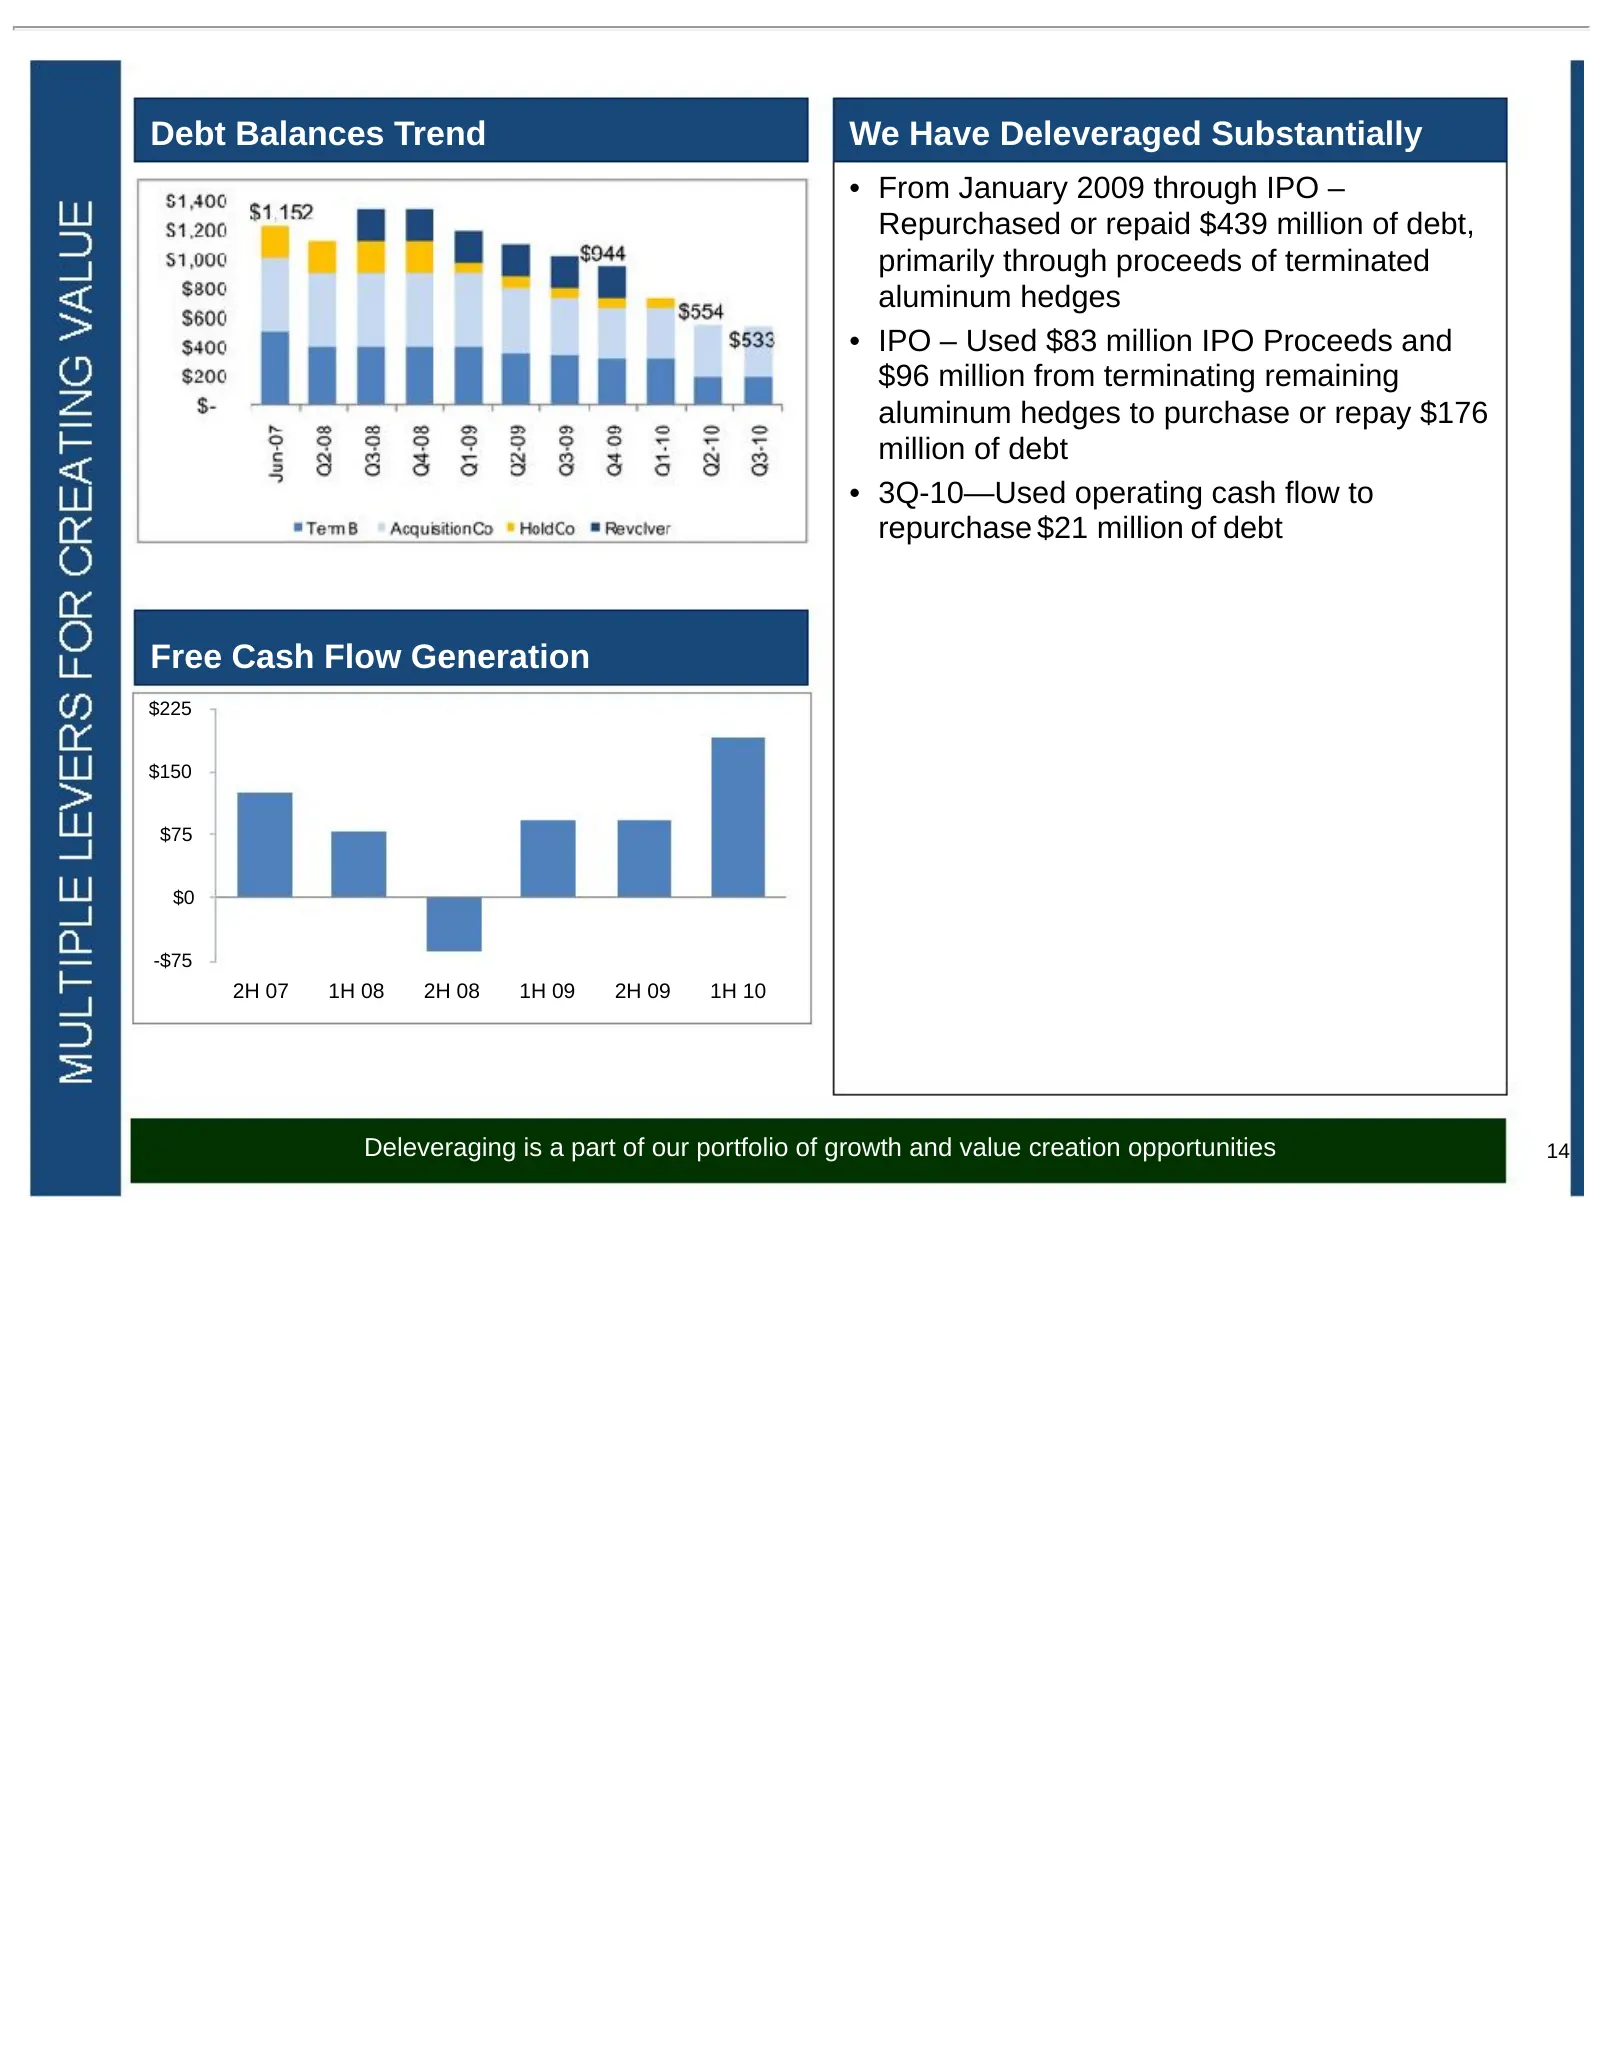
Debt Balances Trend We Have Deleveraged Substantially • From January 2009 through IPO – Repurchased or repaid $439 million of debt, primarily through proceeds of terminated aluminum hedges • IPO – Used $83 million IPO Proceeds and $96 million from terminating remaining aluminum hedges to purchase or
Slide 15: Post-IPO, we've done the right things the right way
Post-IPO, we’ve done the right things the right way, and we’ve achieved results 15
Slide 16: Third Quarter Highlights
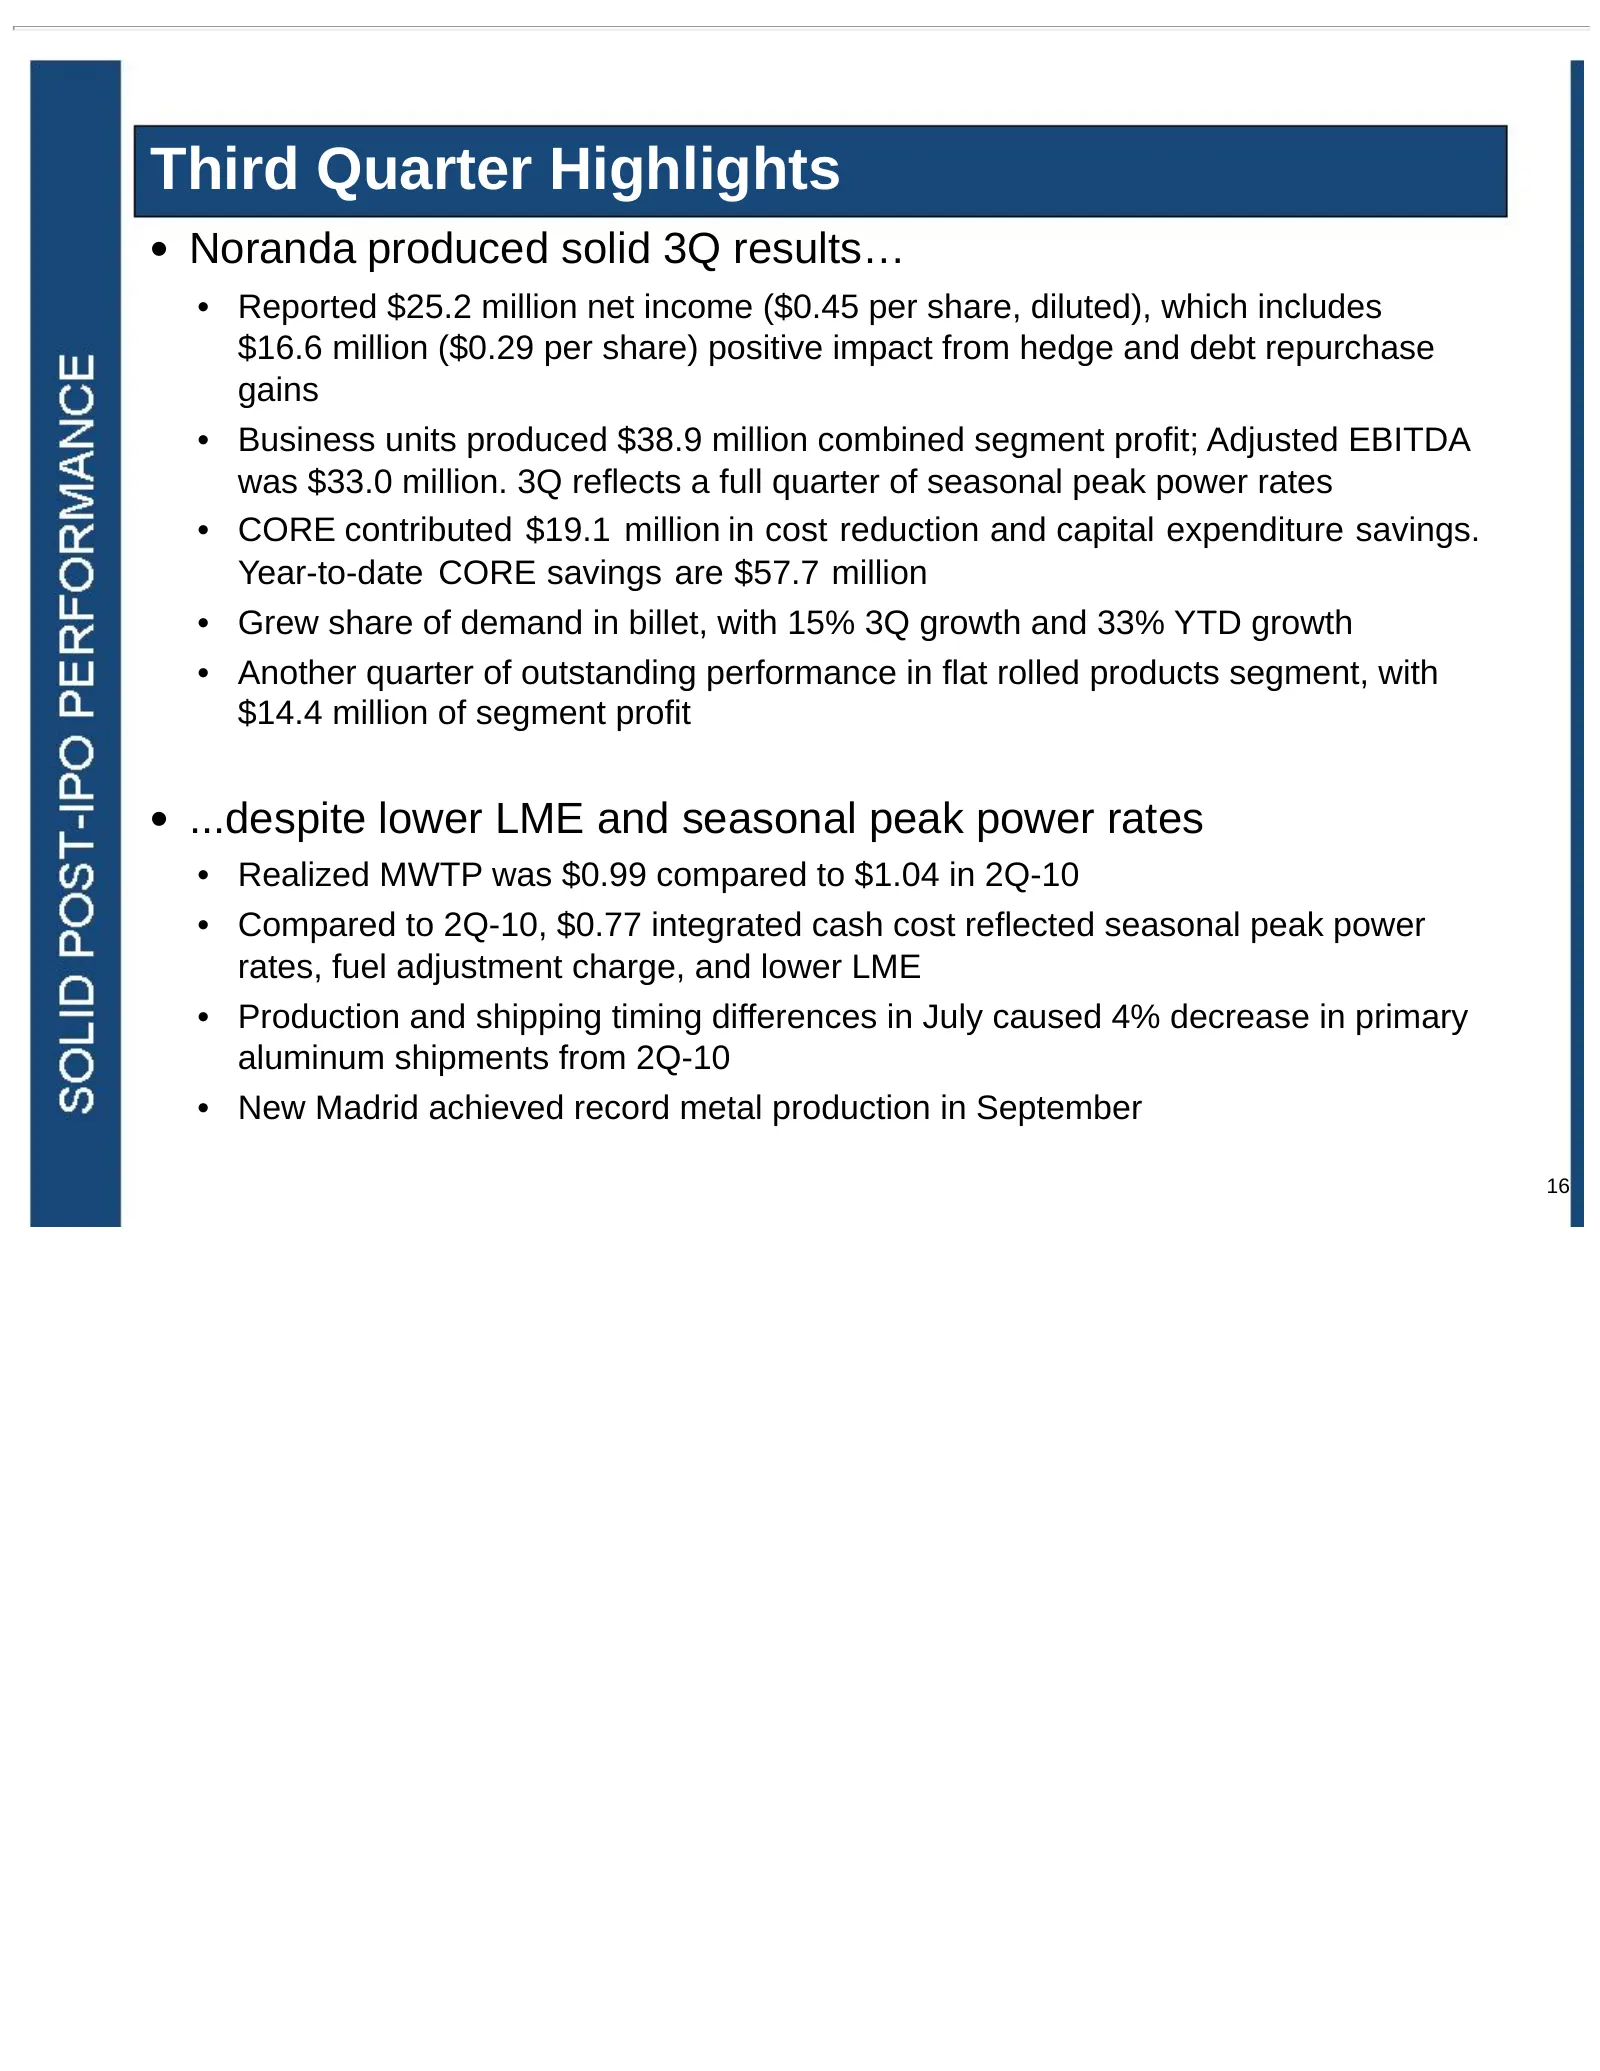
Third Quarter Highlights • Noranda produced solid 3Q results… • Reported $25.2 million net income ($0.45 per share, diluted), which includes $16.6 million ($0.29 per share) positive impact from hedge and debt repurchase gains • Business units produced $38.9 million combined segment profit; Adjusted
Slide 17: Third Quarter Highlights
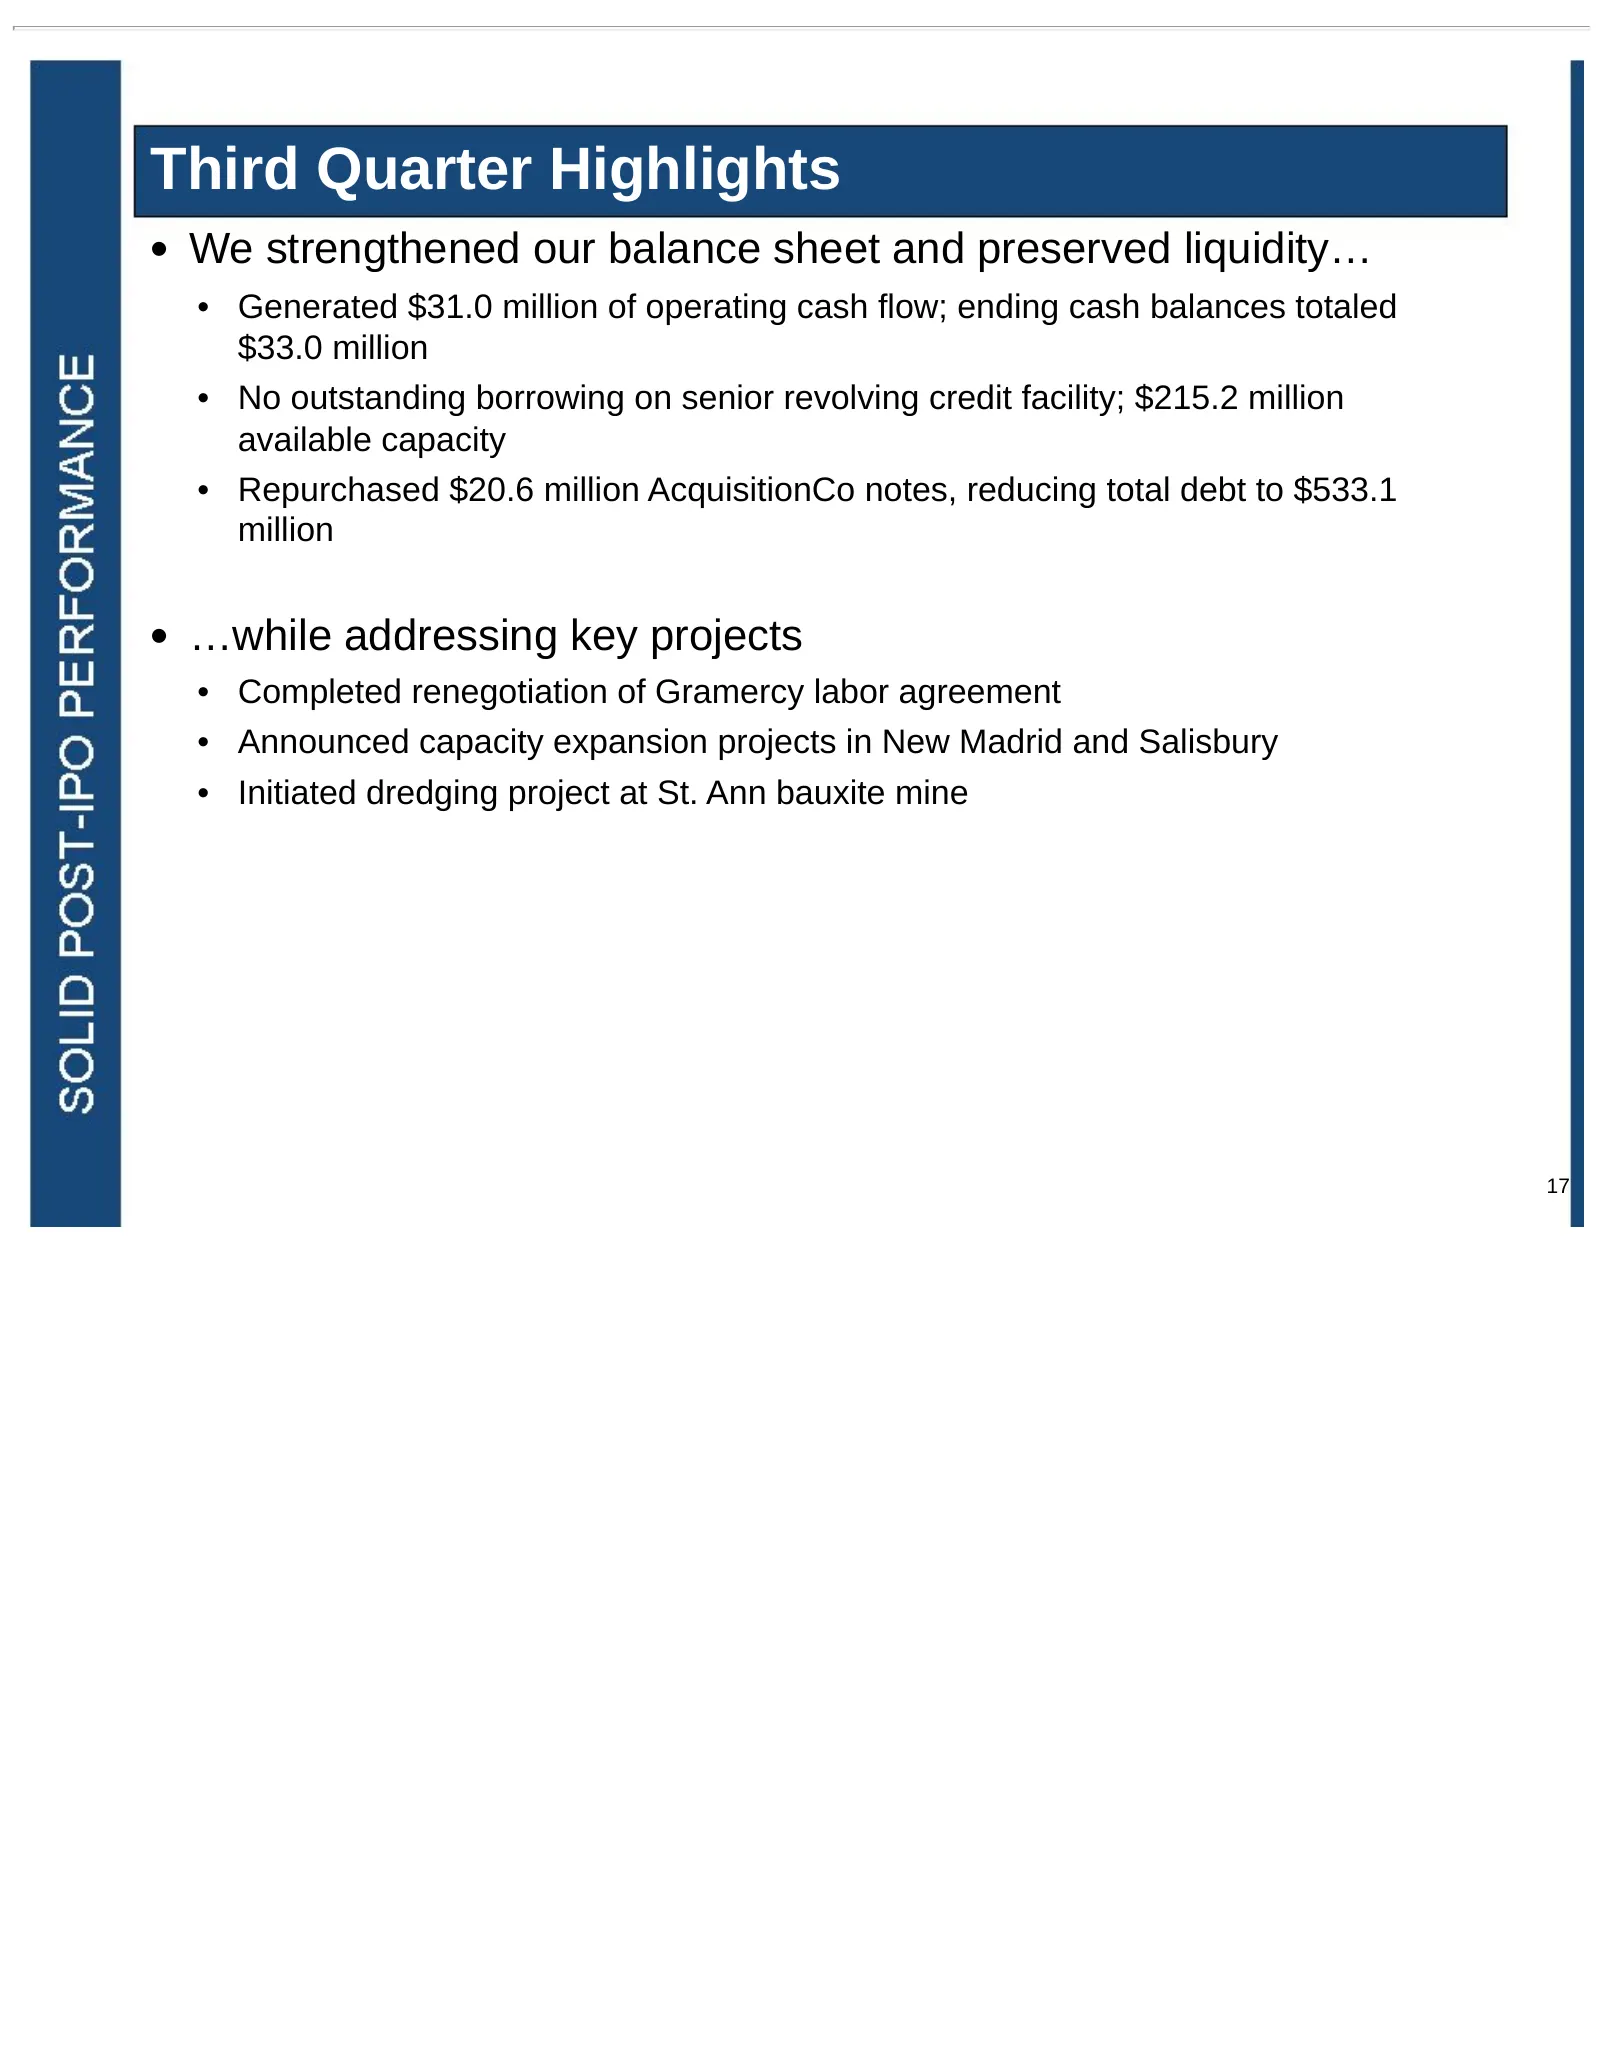
Third Quarter Highlights • We strengthened our balance sheet and preserved liquidity… • Generated $31.0 million of operating cash flow; ending cash balances totaled $33.0 million • No outstanding borrowing on senior revolving credit facility; $215.2 million available capacity • Repurchased $20.6 mil
Slide 18: Corporate Overview: Upstream and Flat Rolled Products
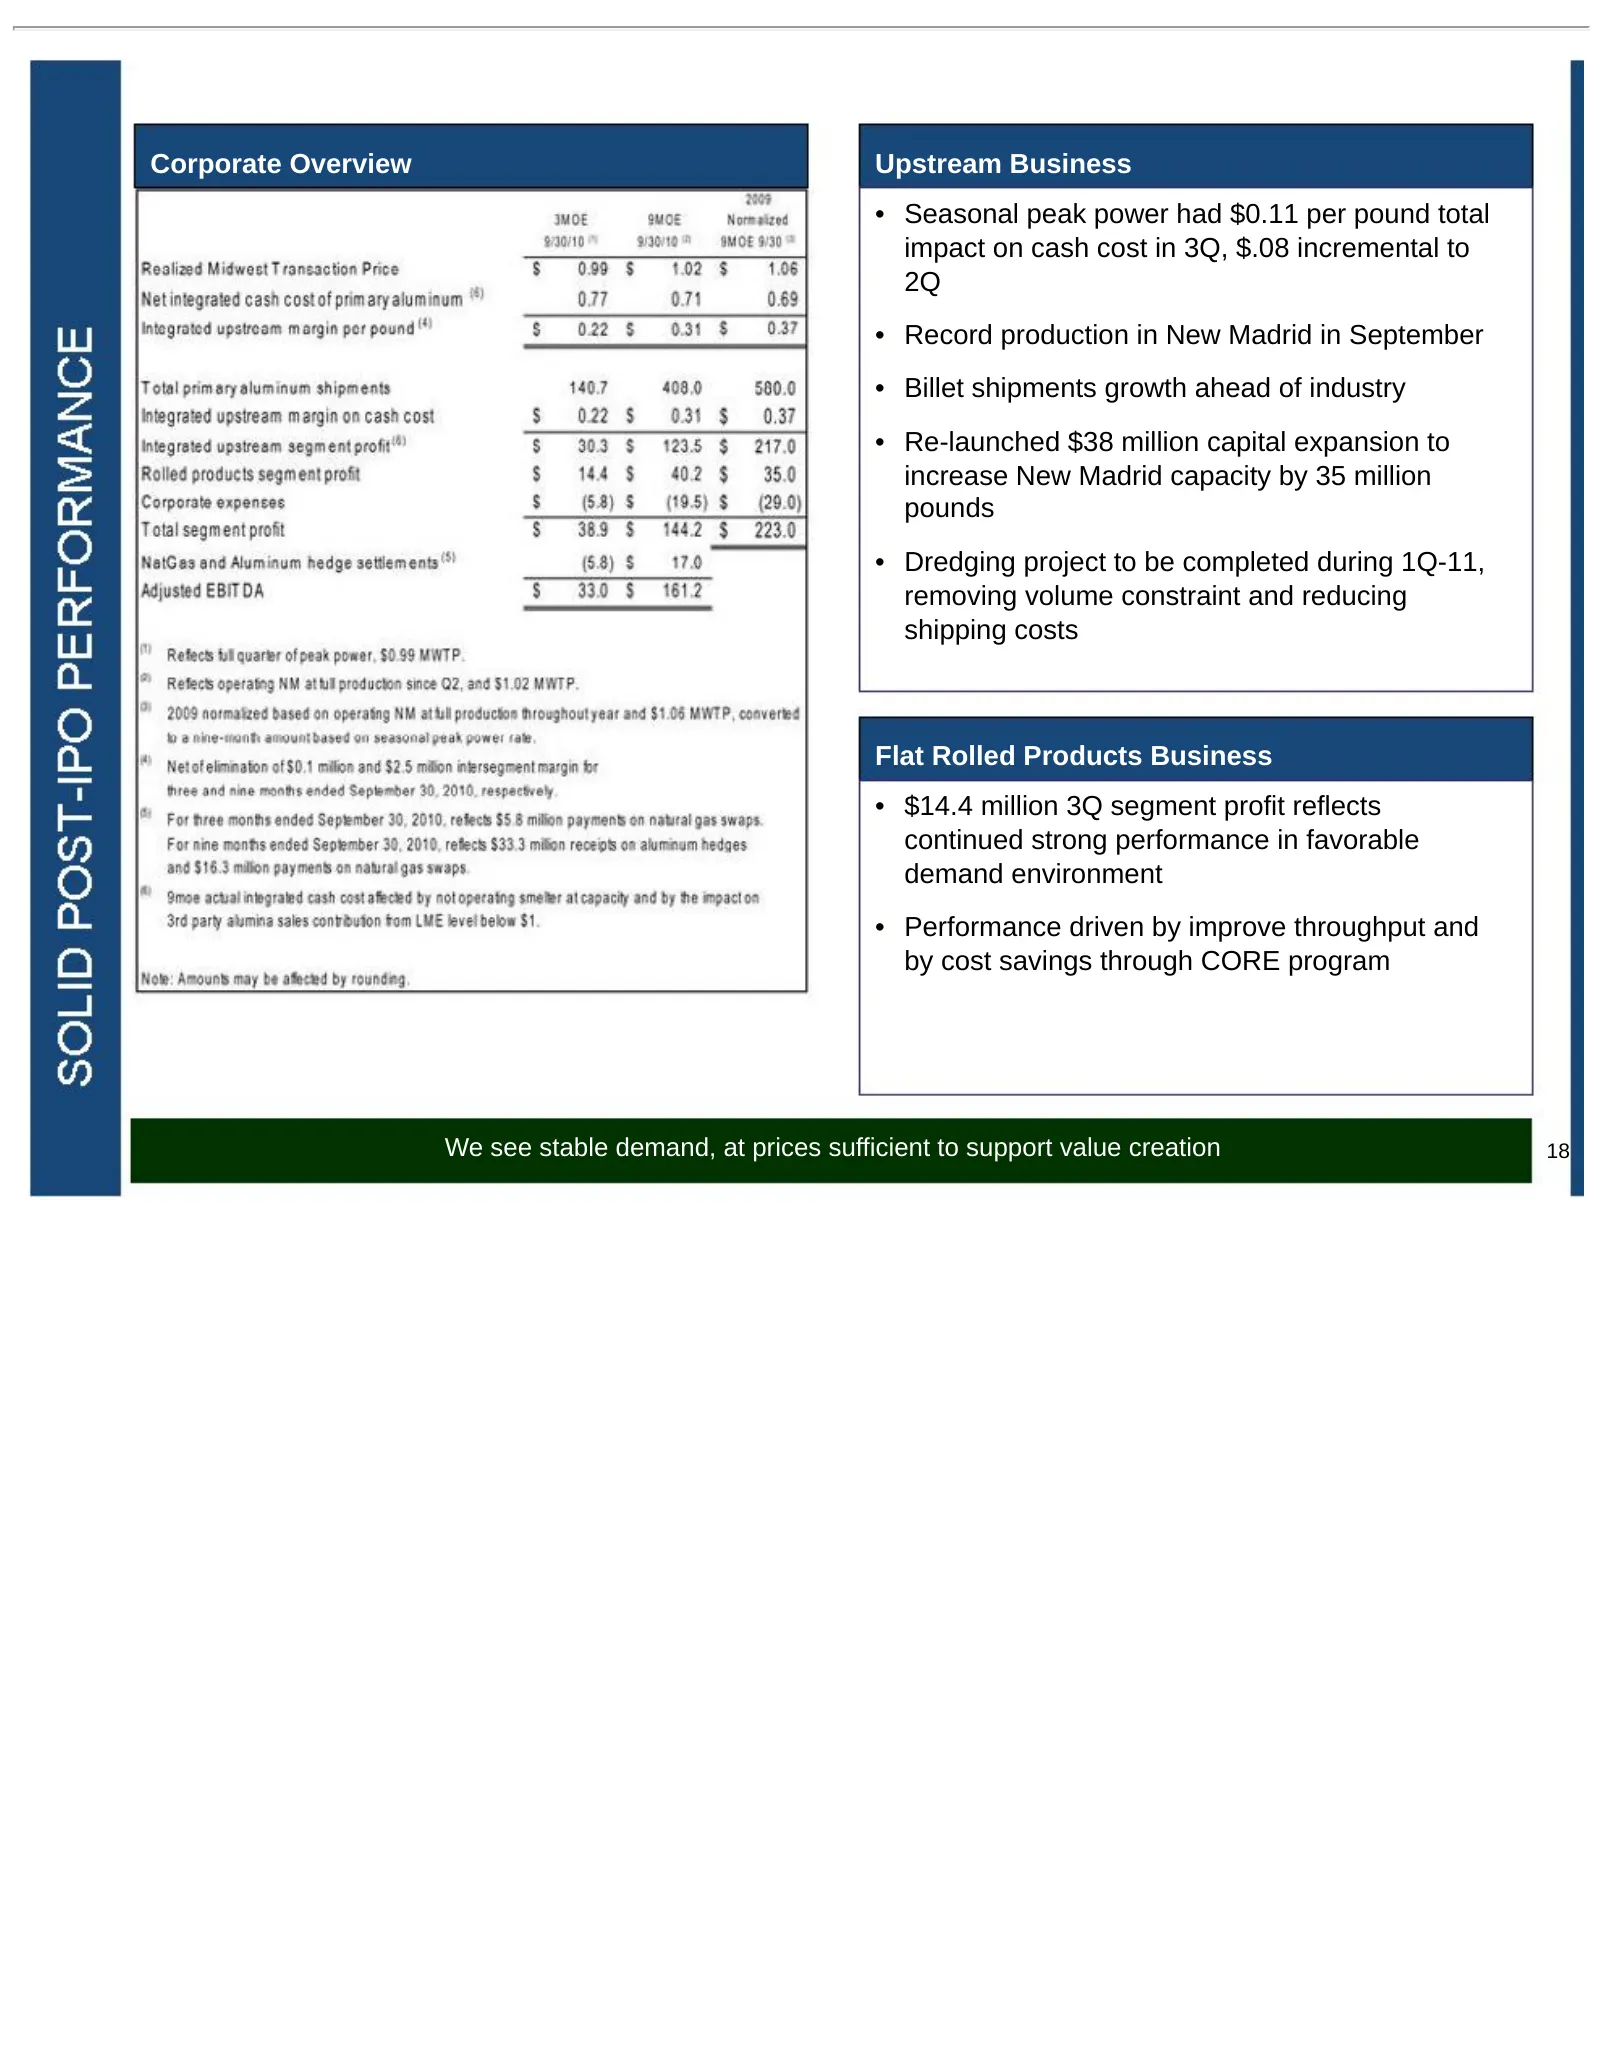
Corporate Overview Upstream Business • Seasonal peak power had $0.11 per pound total impact on cash cost in 3Q, $.08 incremental to 2Q • Record production in New Madrid in September • Billet shipments growth ahead of industry • Re-launched $38 million capital expansion to increase New Madrid capacit
Slide 19: We have two #1 Priorities
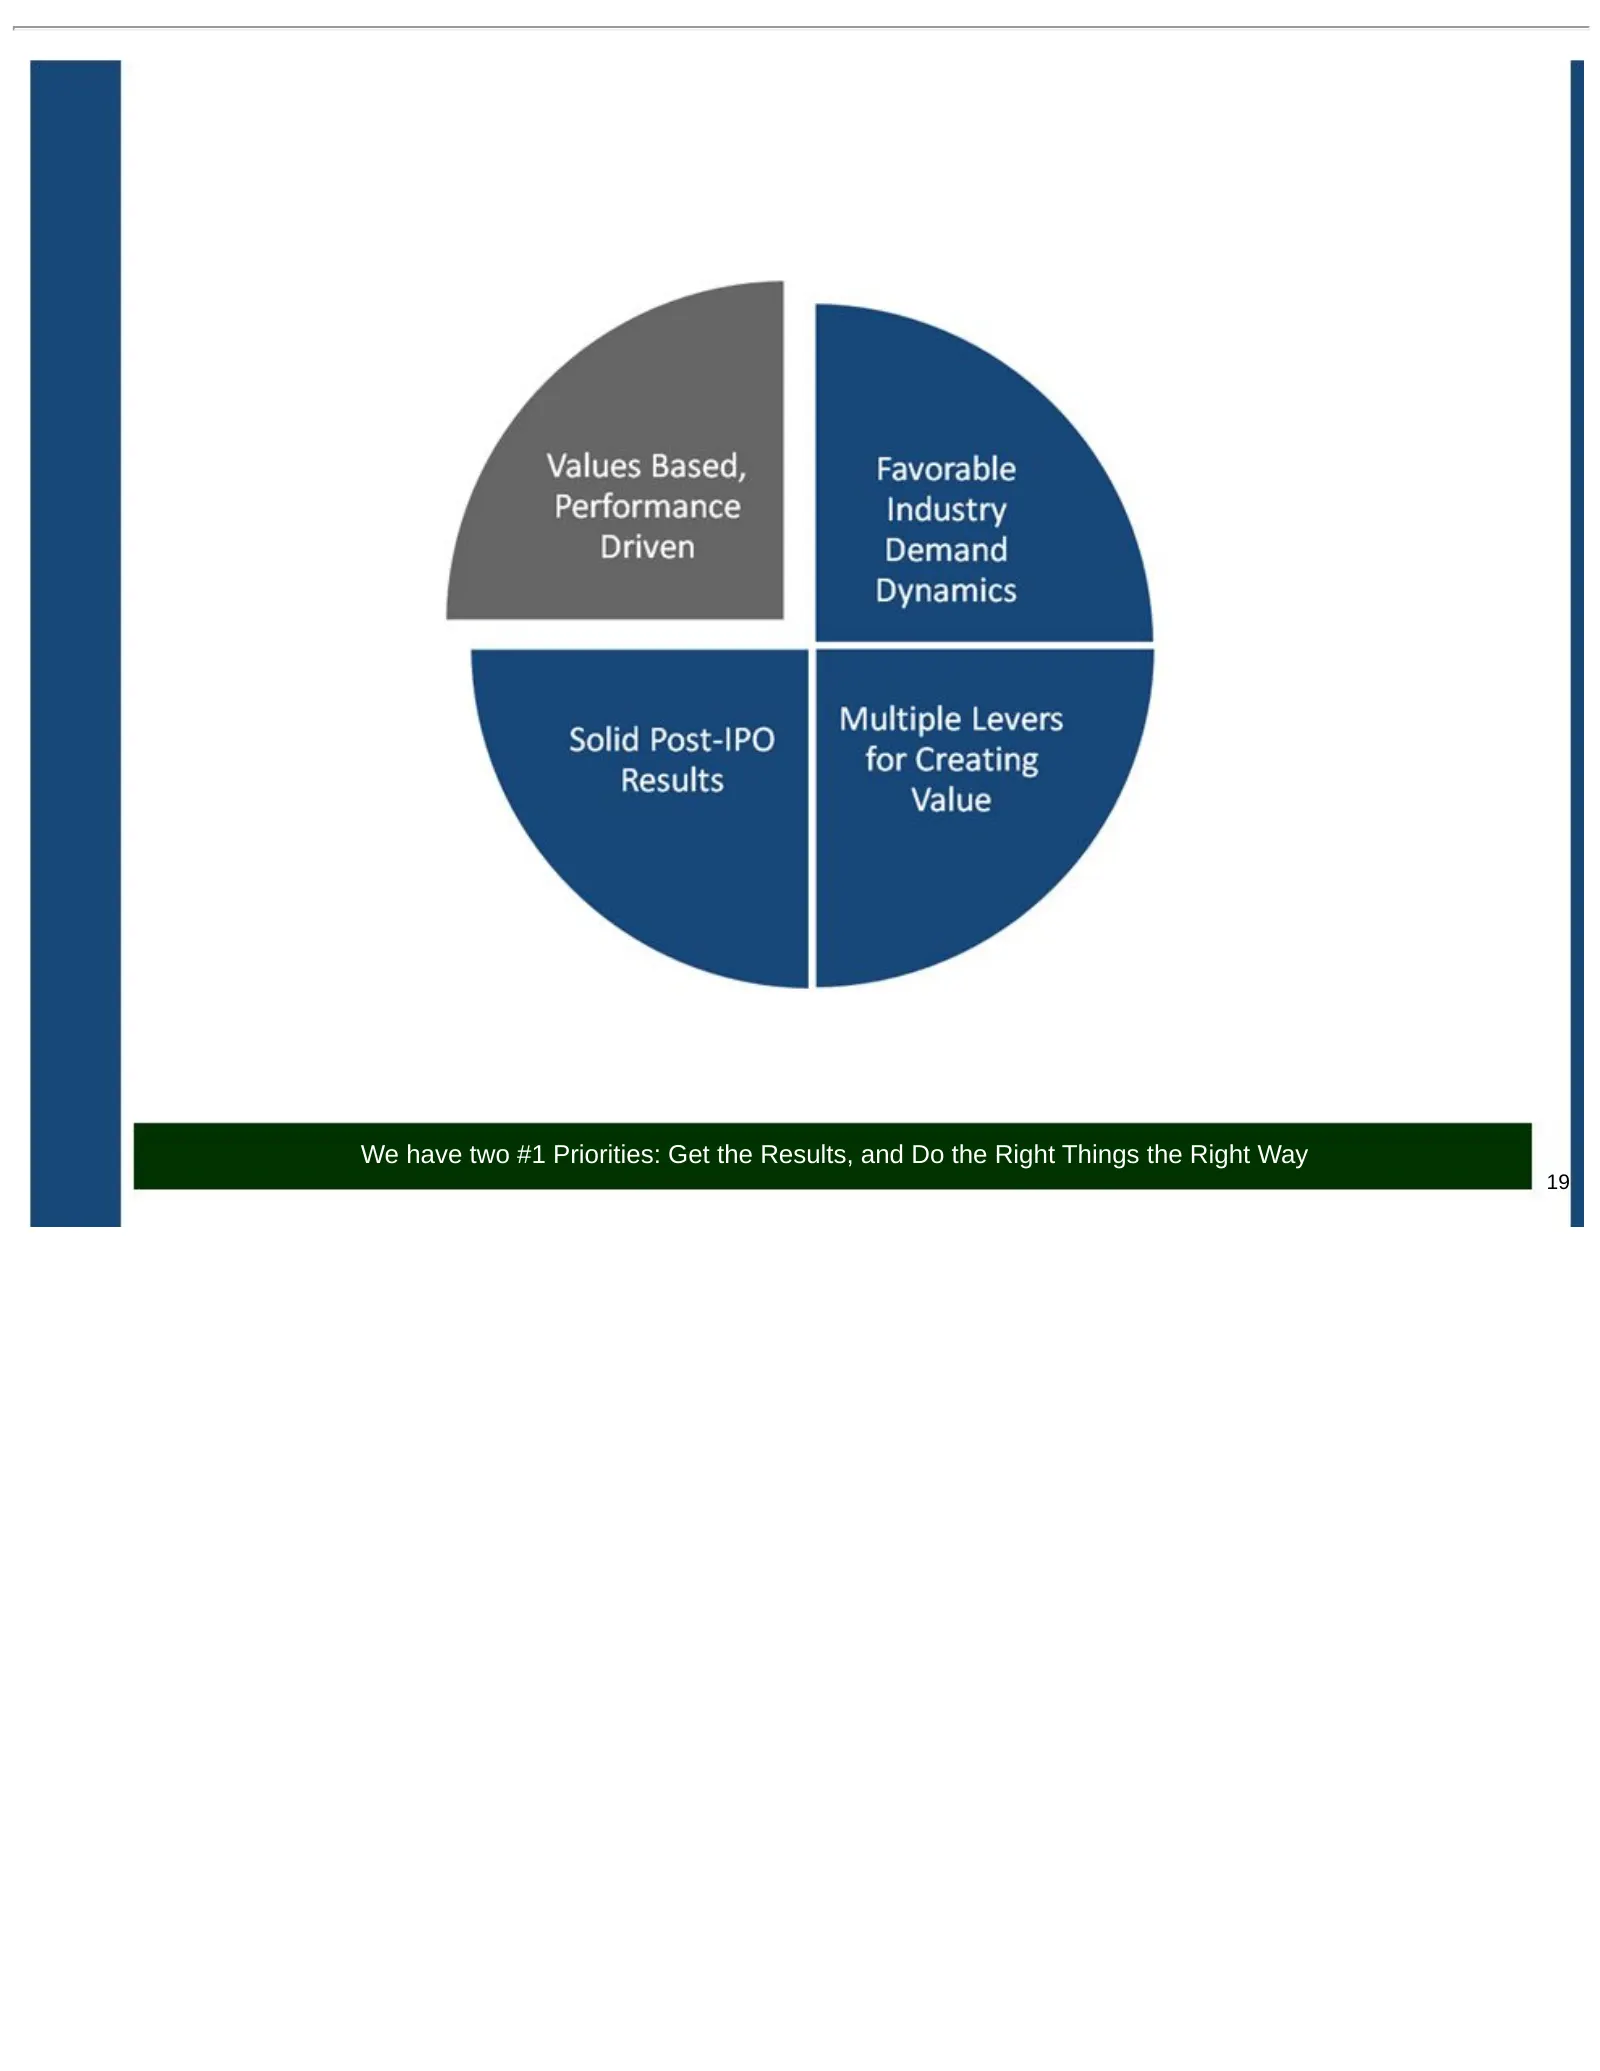
We have two #1 Priorities: Get the Results, and Do the Right Things the Right Way 19
Slide 20: Noranda Mission
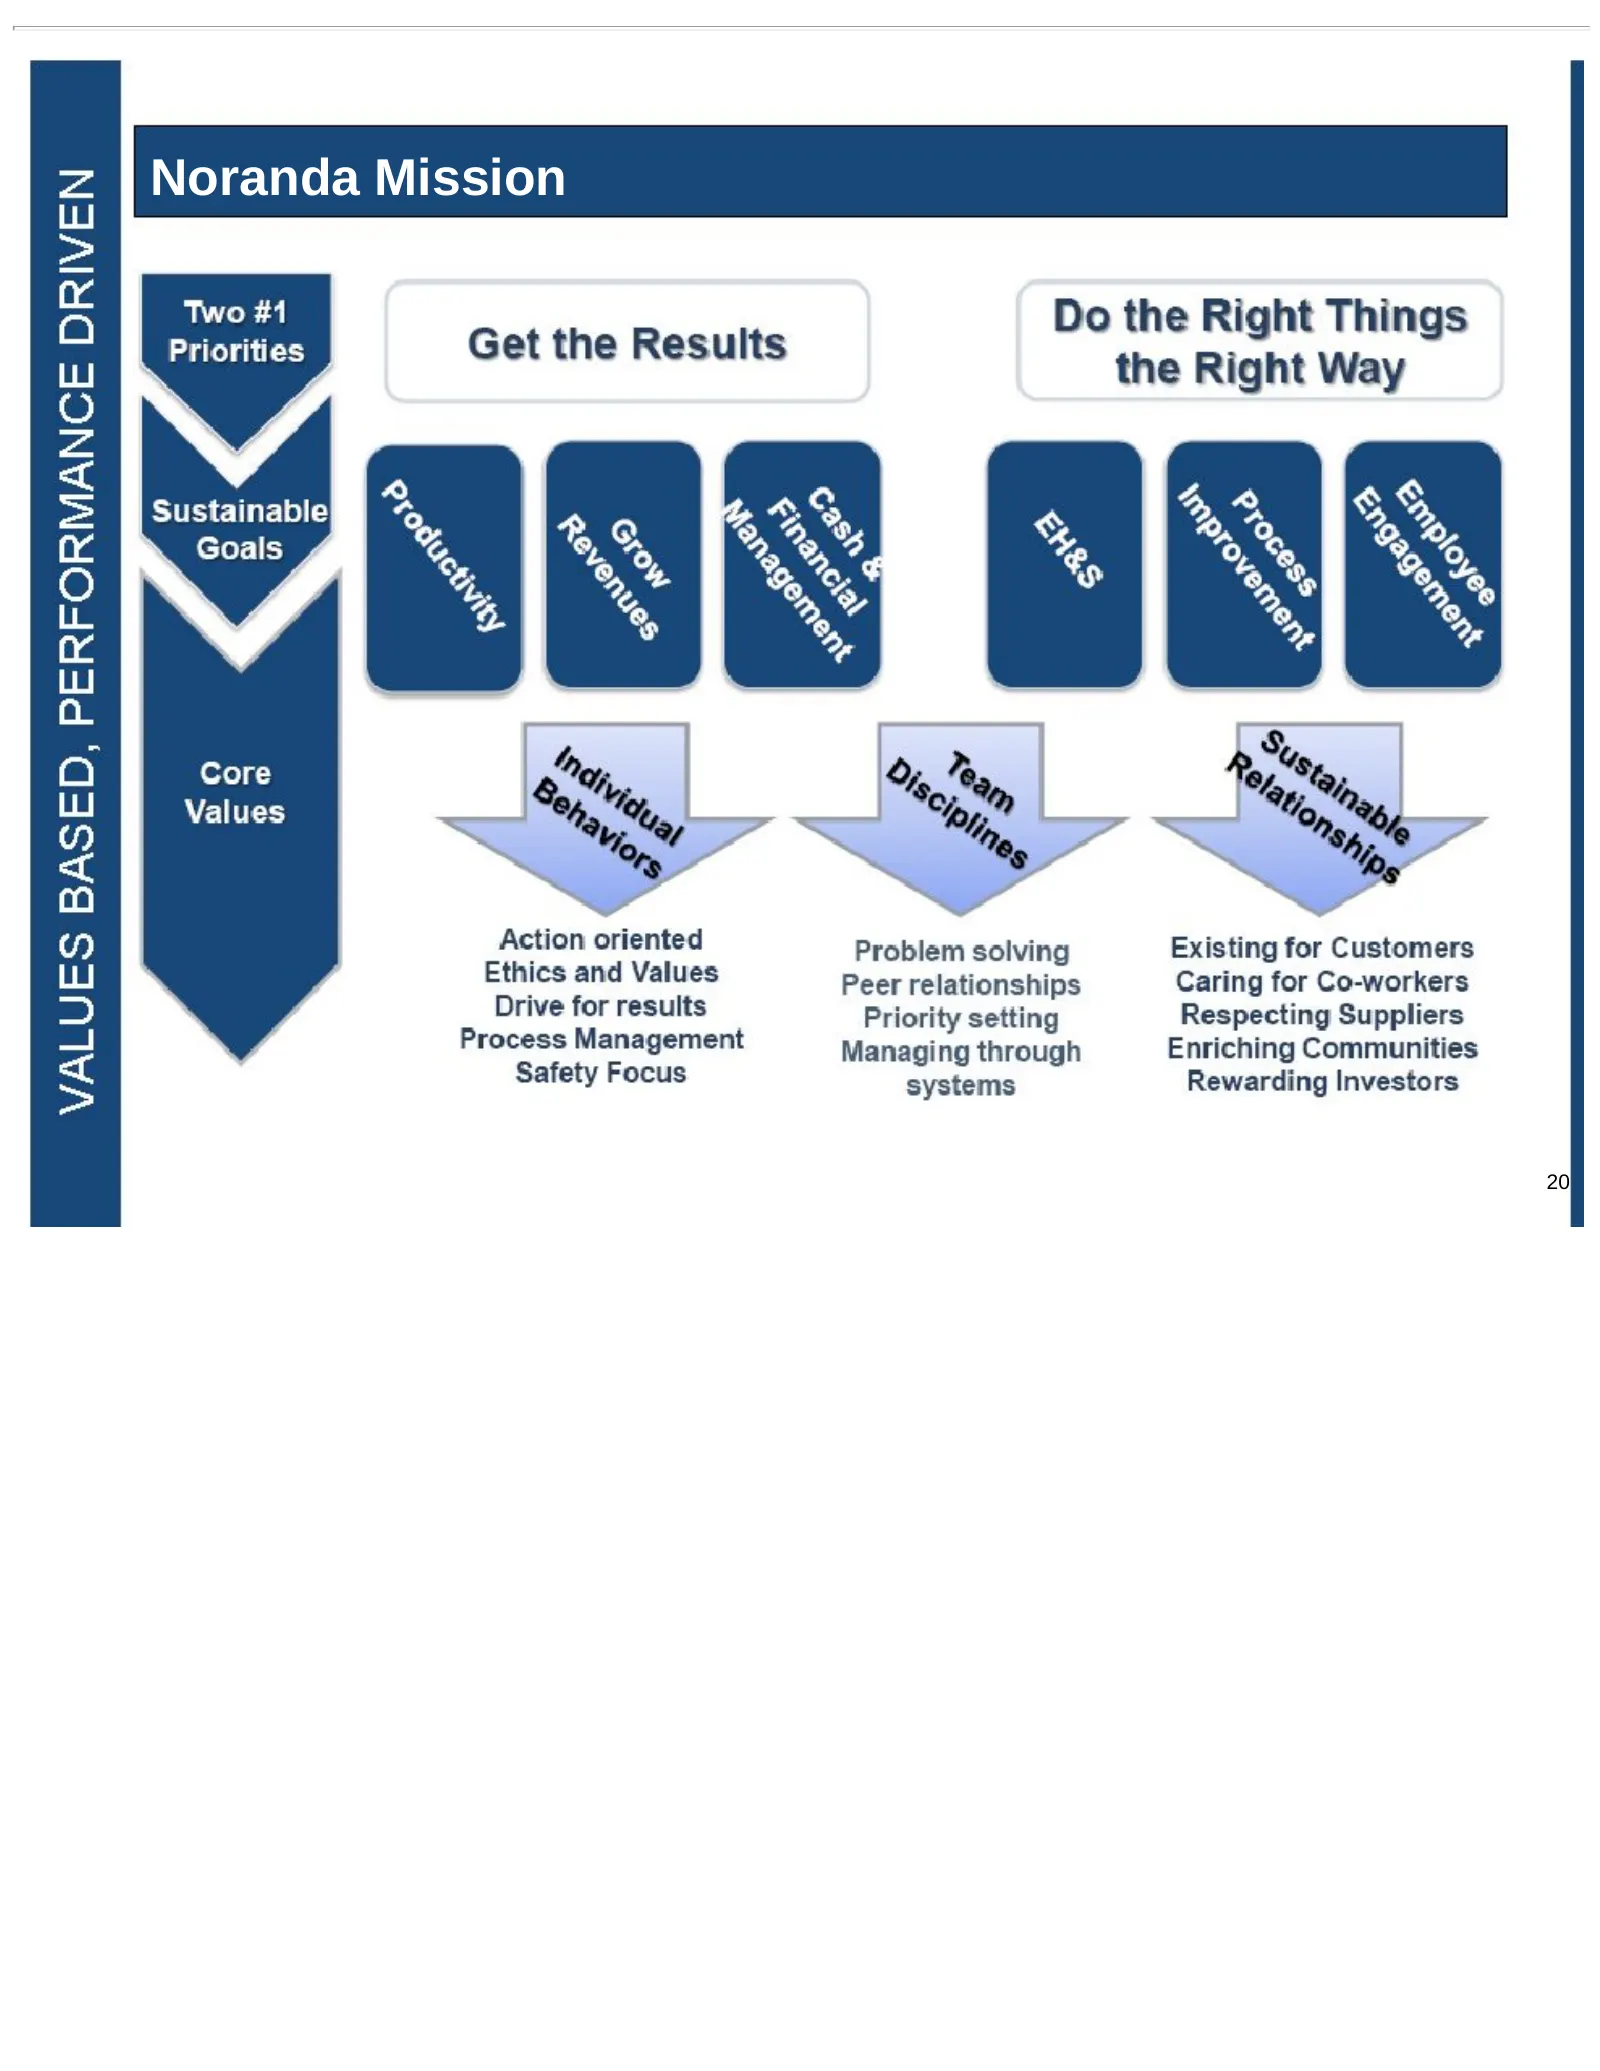
a Lu = ow a) Lu O Zz <f = oO O iL (aa im o Q Lu %) <f ra) ) uw > a > Noranda Mission Do the Right Things the Right Way Two #1 Priorities Values Get the Results Action oriented Problem solving Existing for Customers Ethics and Values Peer relationships Caring for Co-workers Drive for results Priority
Slide 21: Experienced Management Team
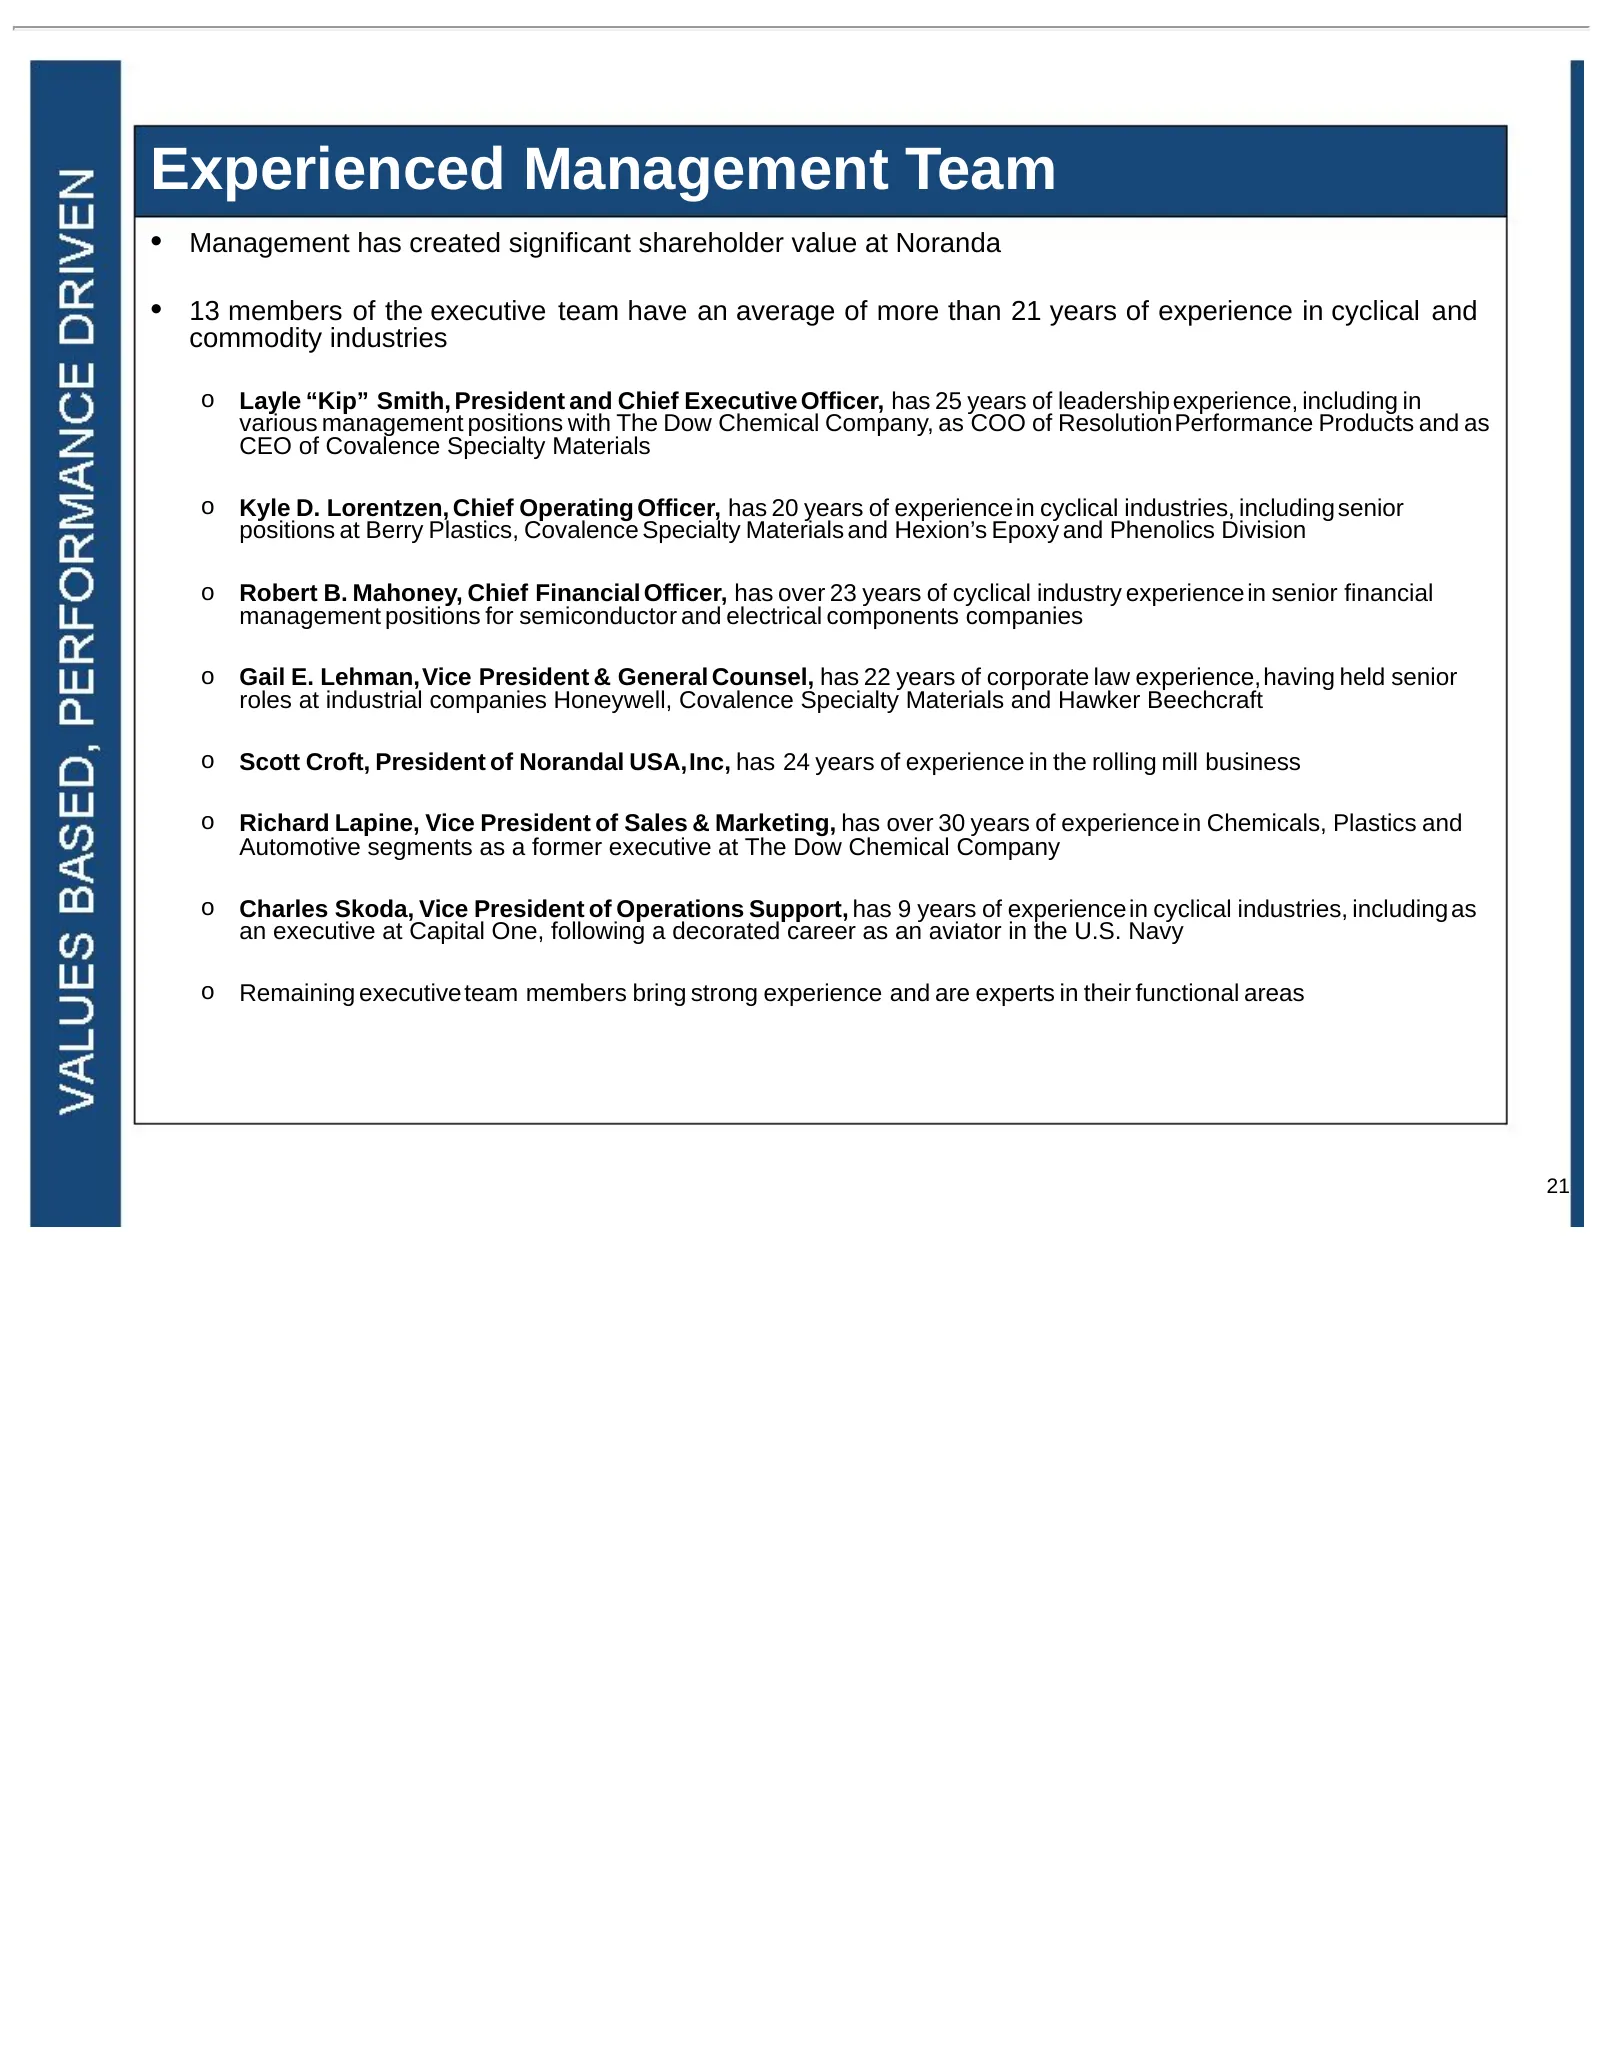
Experienced Management Team • Management has created significant shareholder value at Noranda • 13 members of the executive team have an average of more than 21 years of experience in cyclical and commodity industries o Layle “Kip” Smith, President and Chief Executive Officer, has 25 years of leader
Slide 22: Values Based, Performance Driven
Values Based, Performance Driven Solid Post-IPO Results Favorable Industry Demand Dynamics Multiple Levers for Creating Value 22|
Slide 23: Appendices
APPENDICES al noranda
Slide 24: Non-GAAP Financial Measures
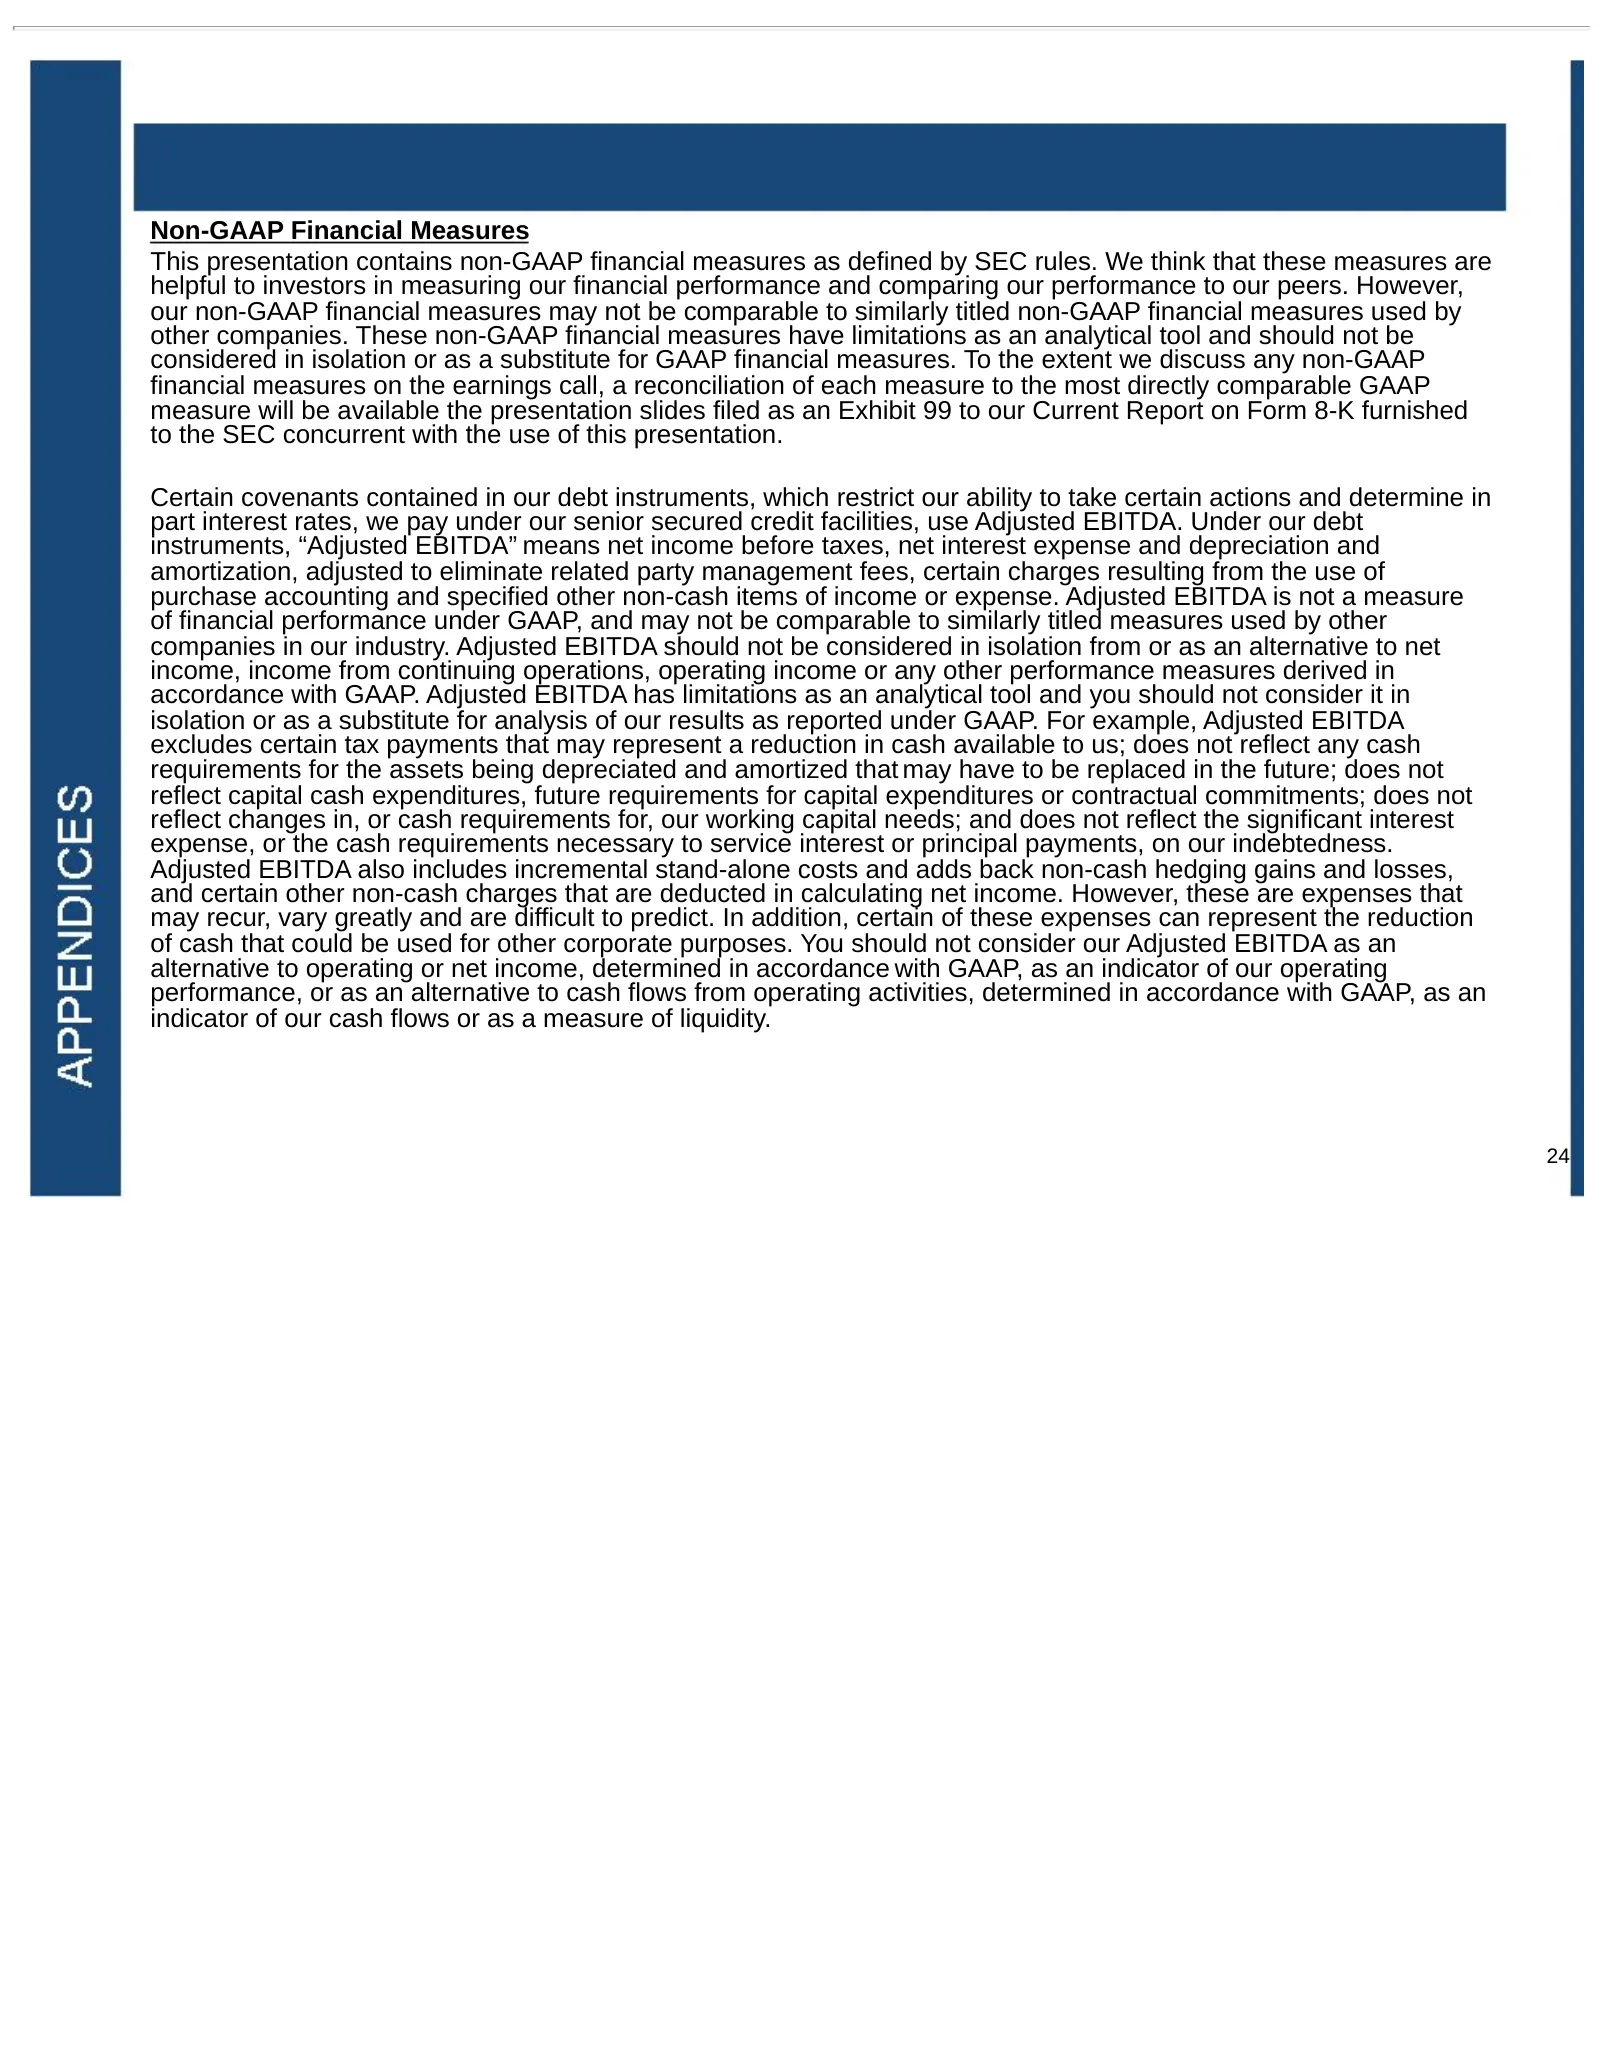
Non-GAAP Financial Measures This presentation contains non-GAAP financial measures as defined by SEC rules. We think that these measures are helpful to investors in measuring our financial performance and comparing our performance to our peers. However, our non-GAAP financial measures may not be com
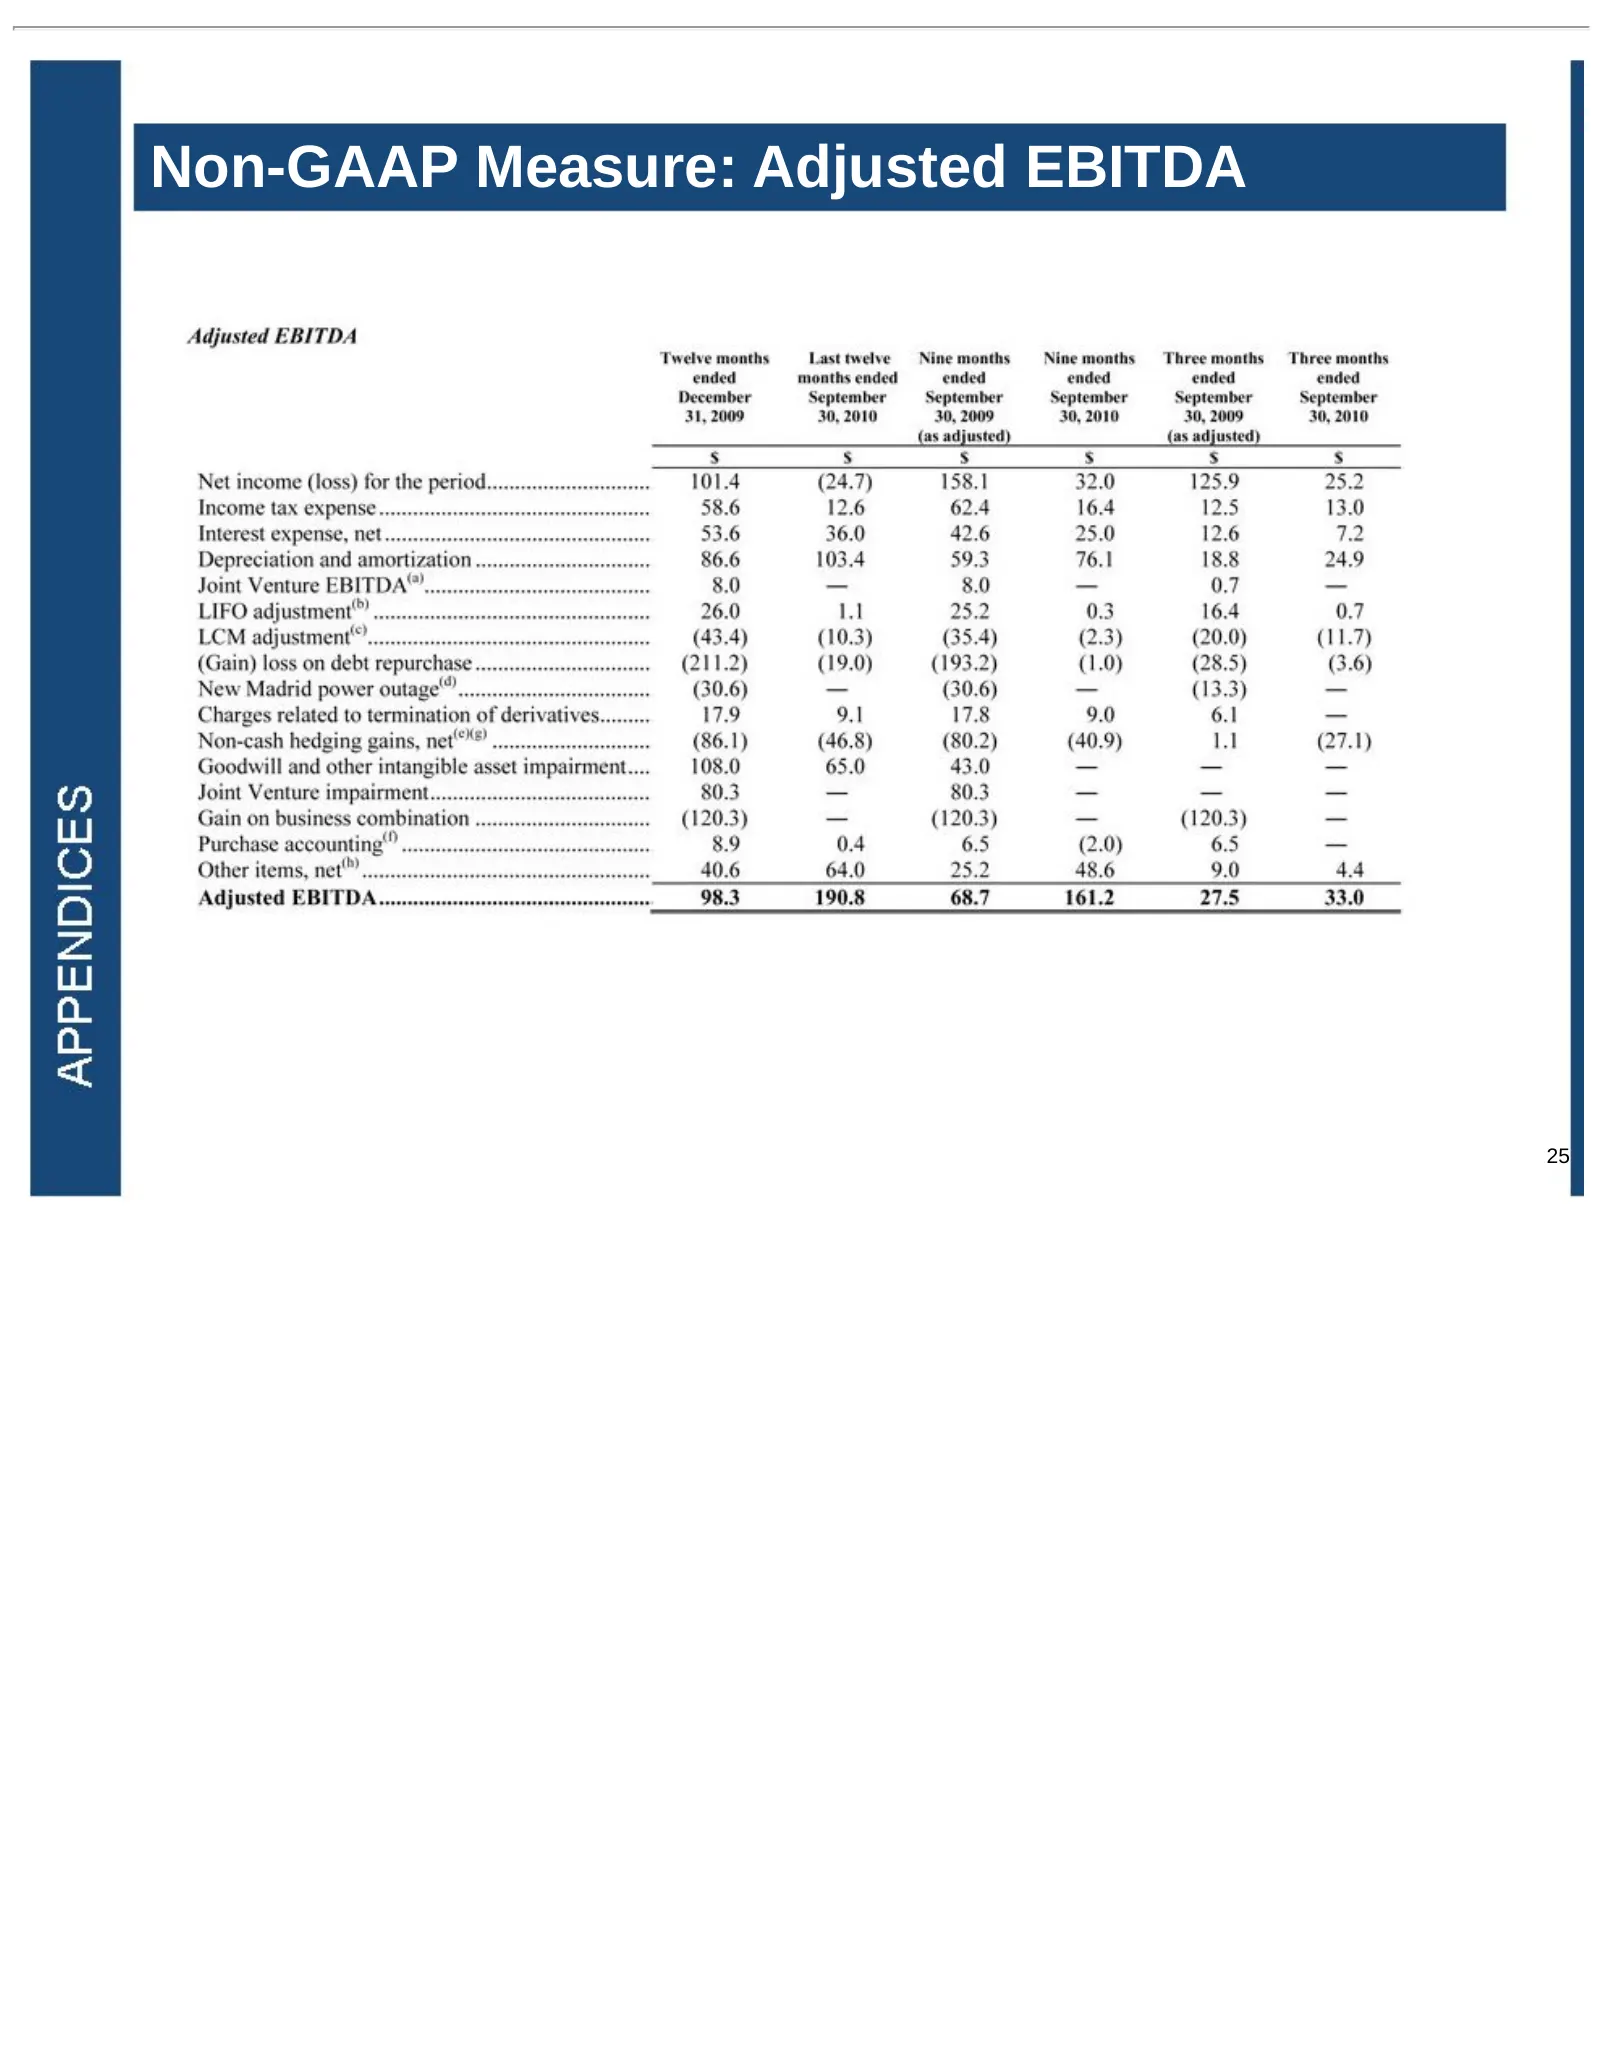
Slide 25: Non-GAAP Measure: Adjusted EBITDA
Non-GAAP Measure: Adjusted EBITDA 25
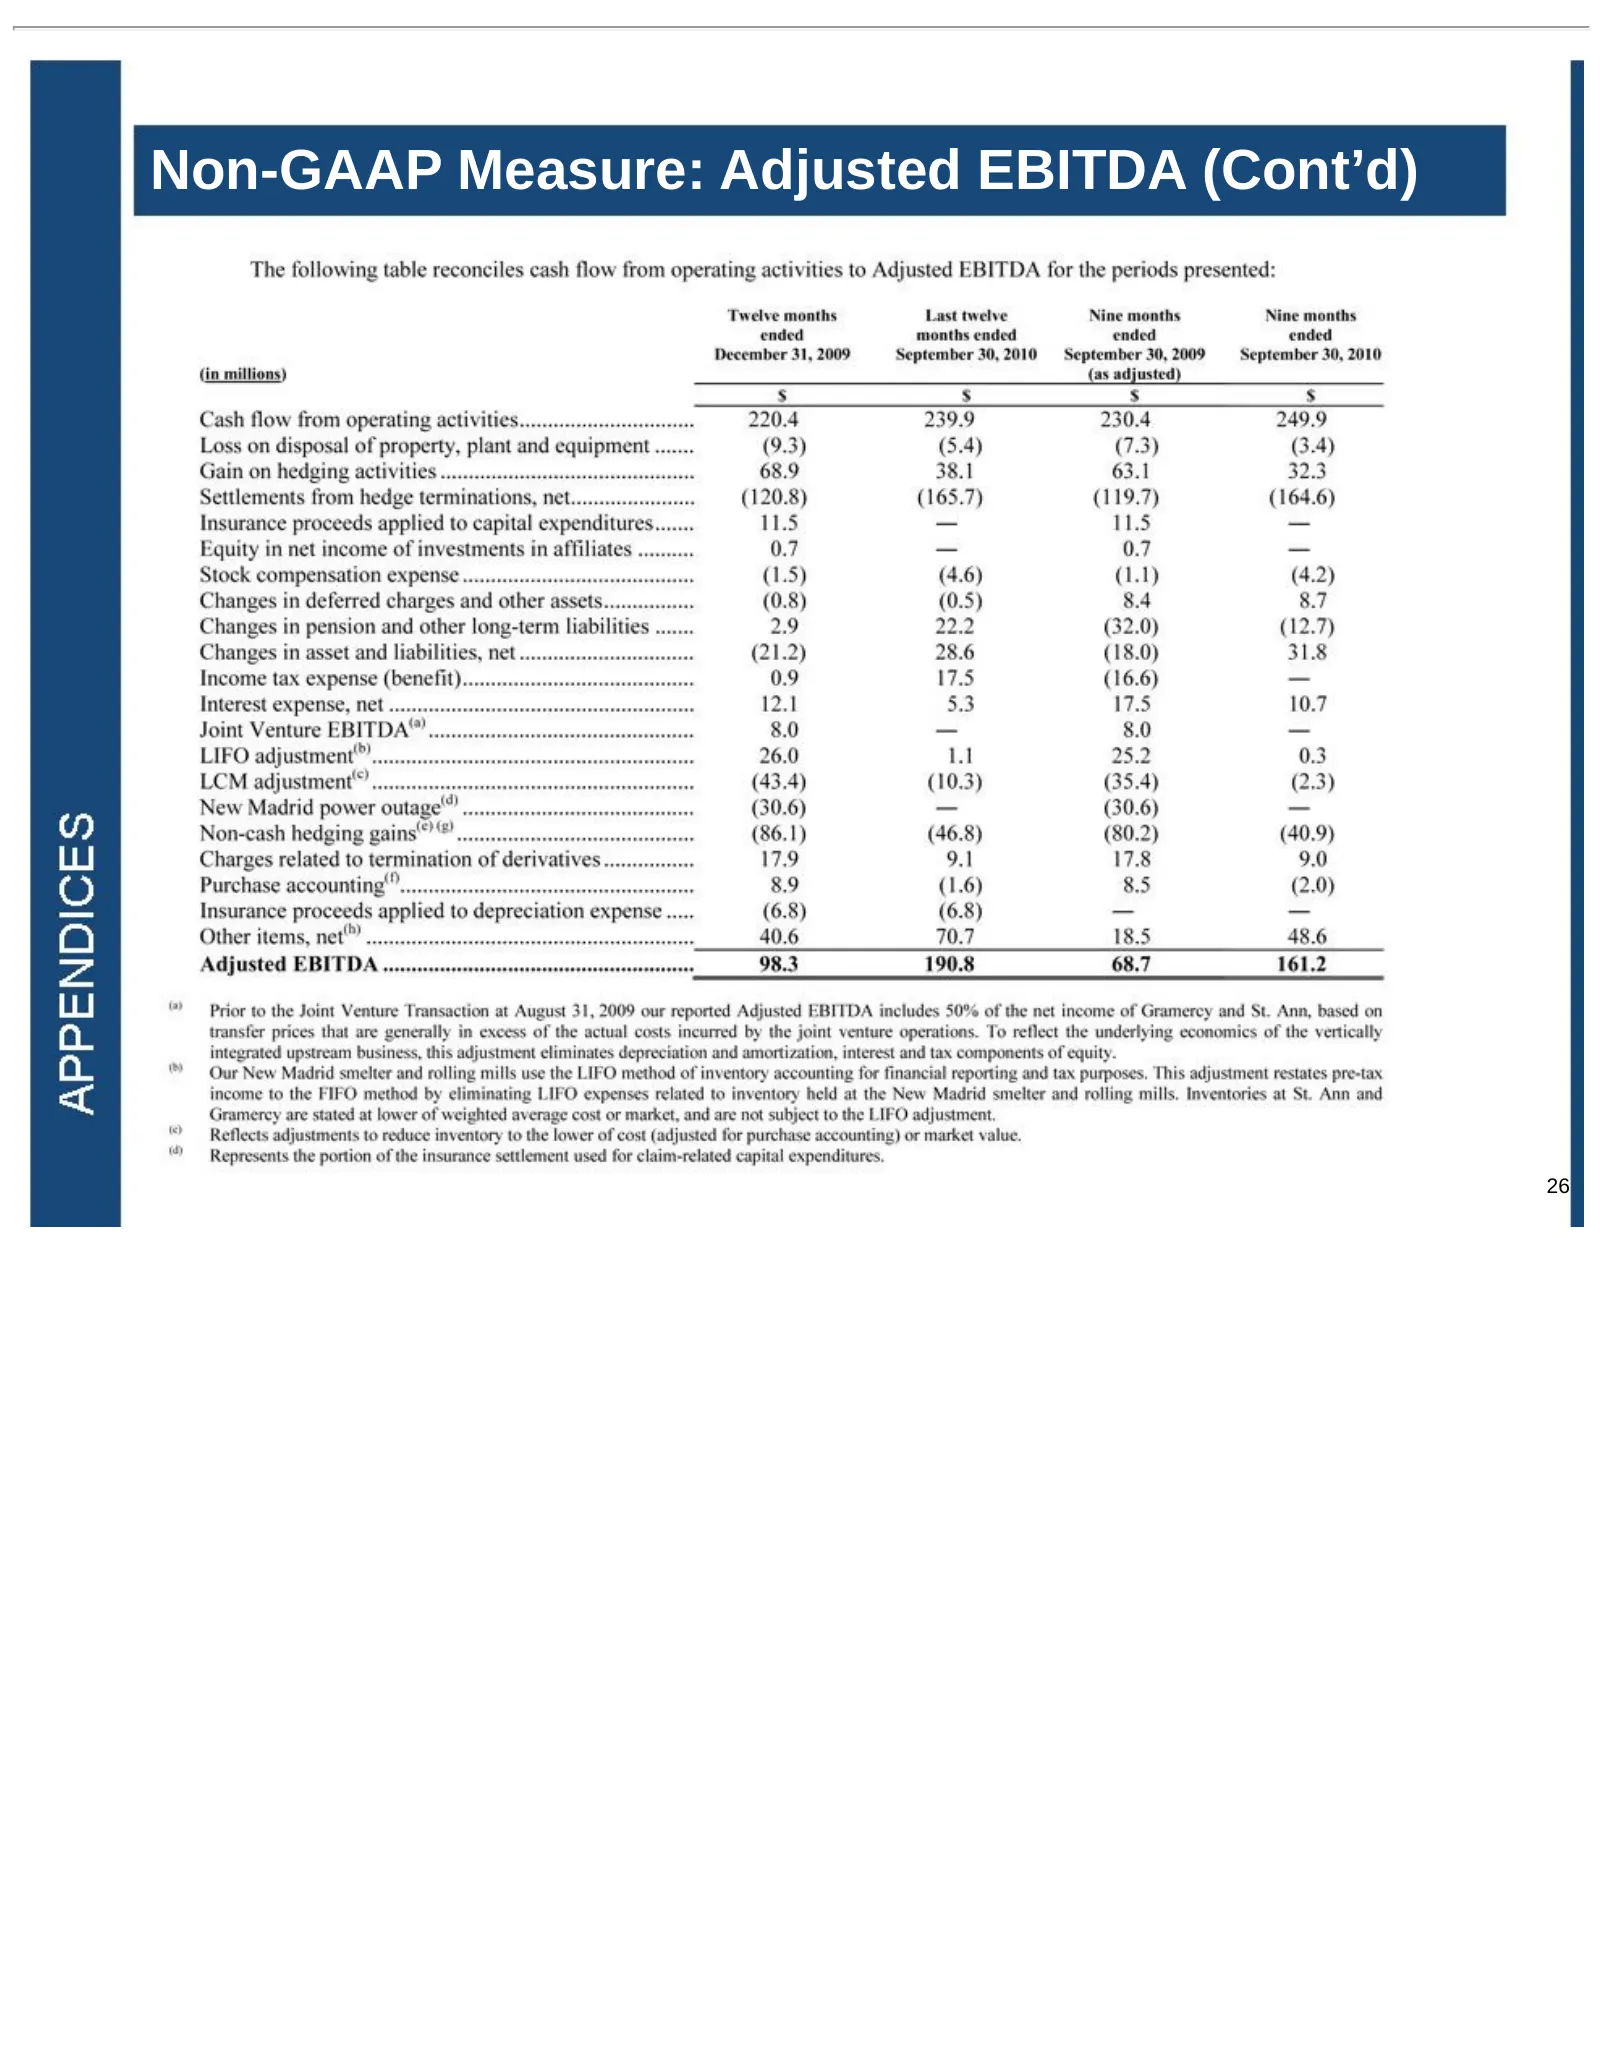
Slide 26: Non-GAAP Measure: Adjusted EBITDA (Cont'd)
Non-GAAP Measure: Adjusted EBITDA (Cont’d) 26
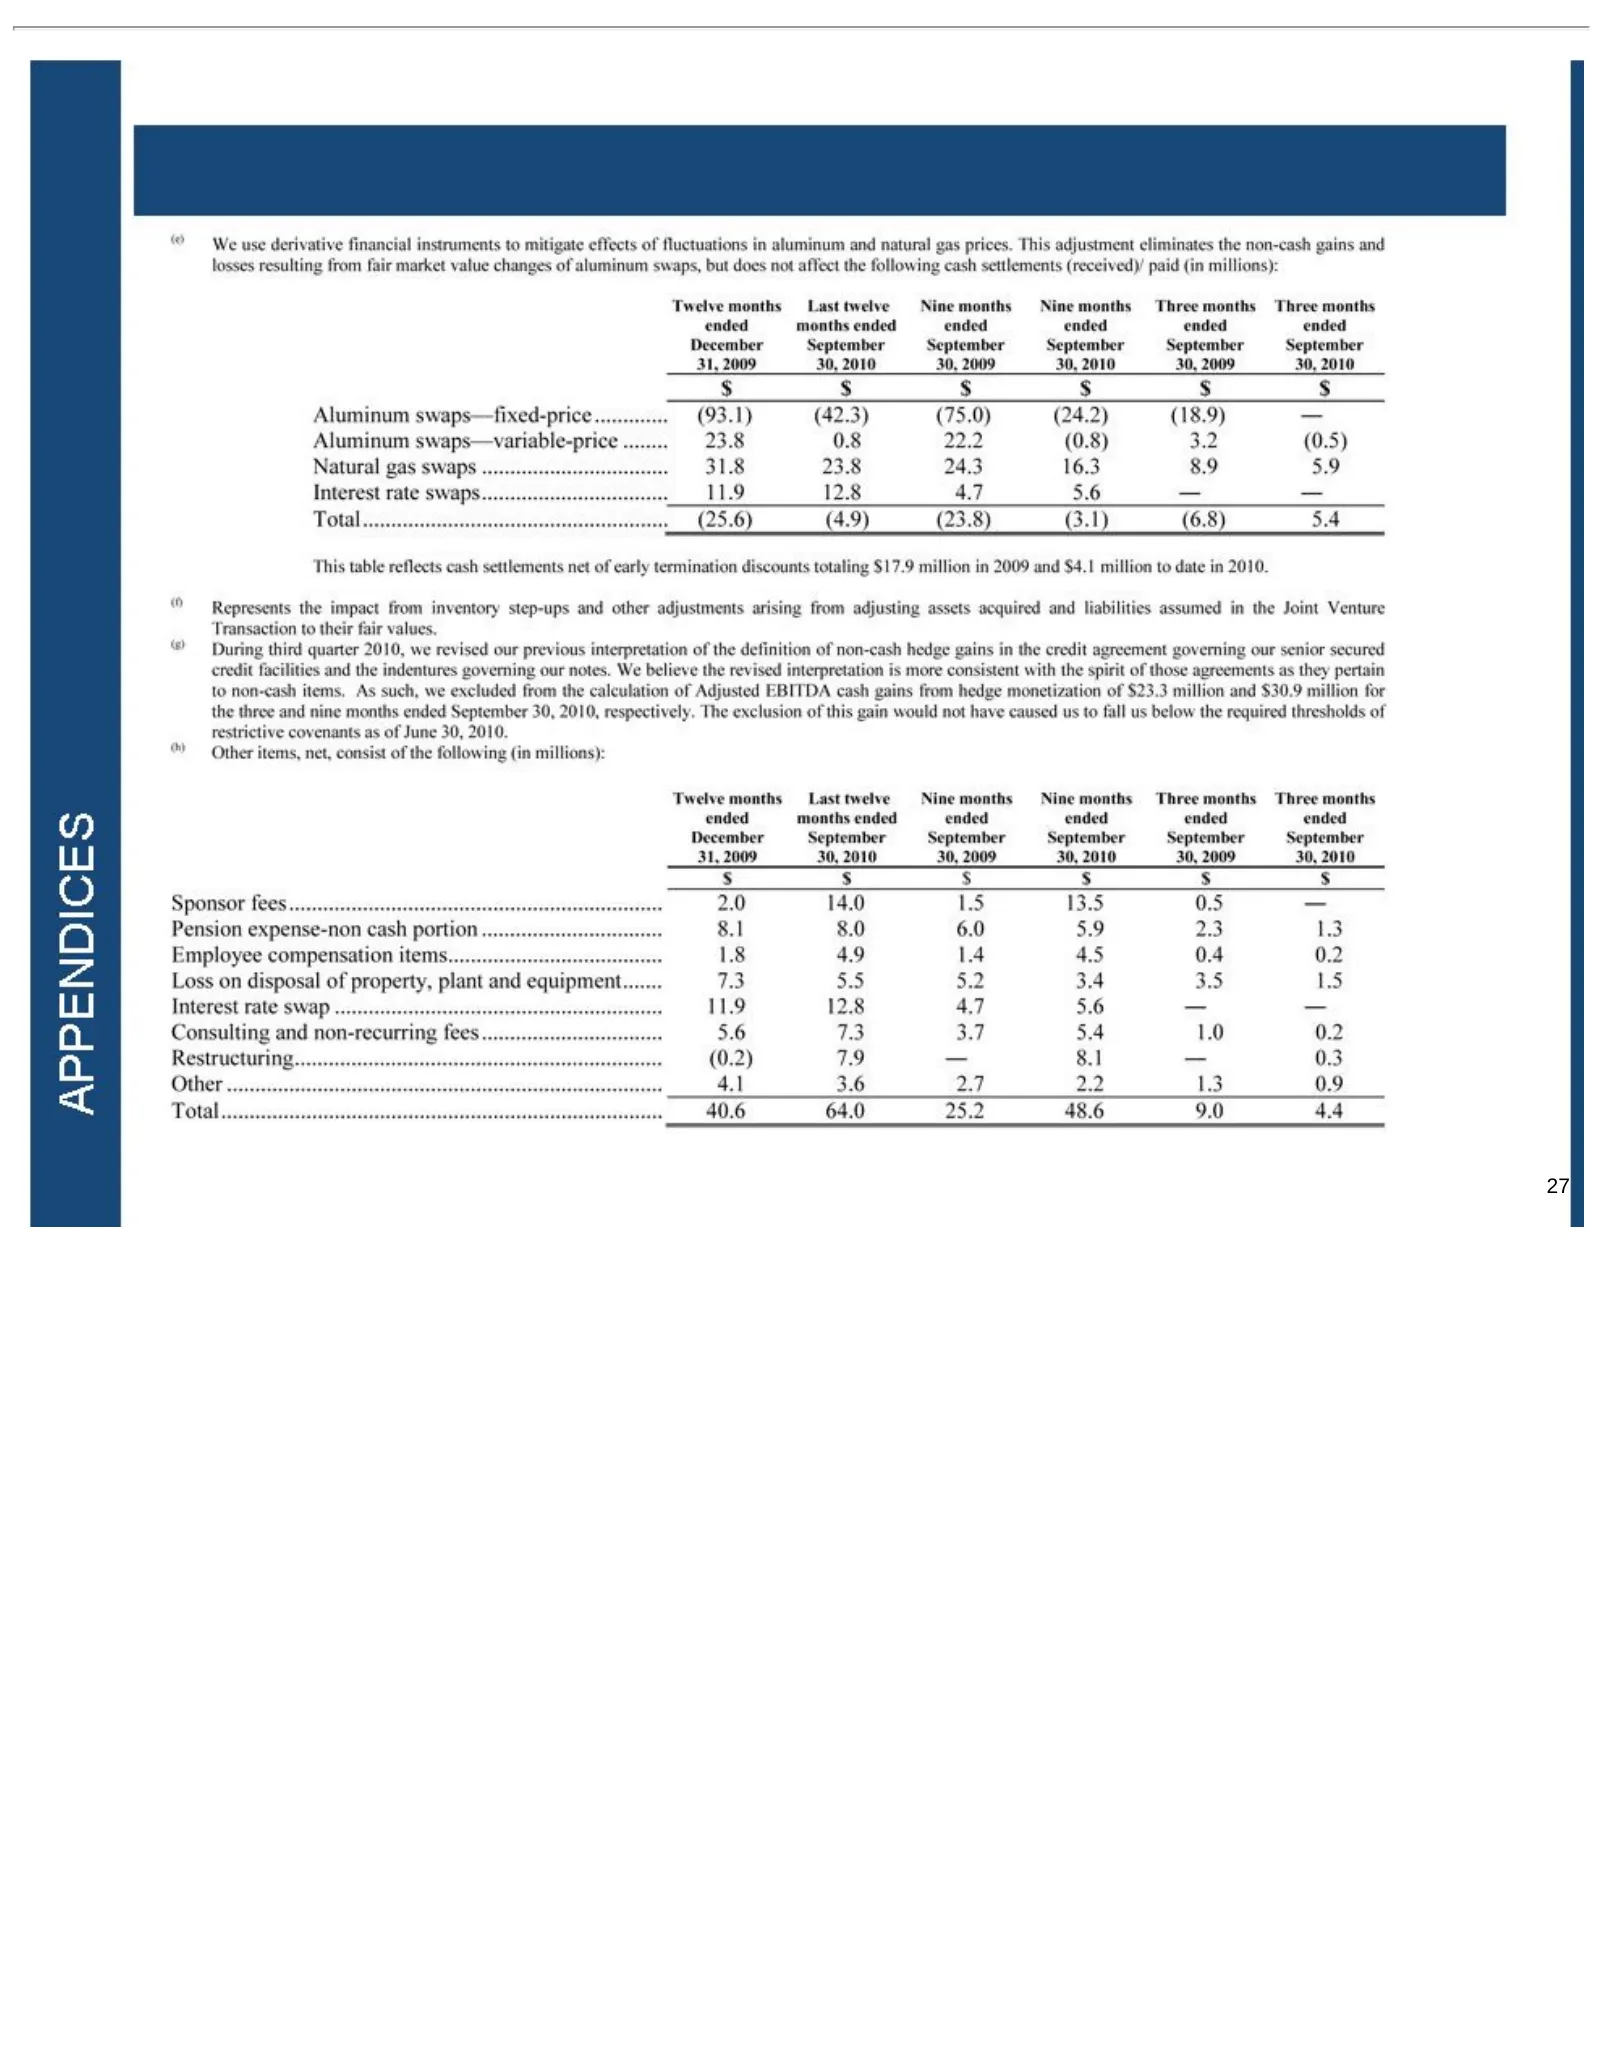
Slide 27: Appendices: derivative cash settlements
APPENDICES “We use derivative financial instruments to mitigate effects of fluctuations in aluminum and natural gas prices. This adjustment eliminates the non-cash gains and losses resulting from fair market value changes of aluminum swaps, but does not affect the following cash settlements (receive
Slide 28: NOILVaOddOo ONITTIOH WANIAIN TY VONVYON
28 NOILVaOddOo ONITTIOH WANIAIN TY VONVYON
Source: SEC EDGAR · 8-K filed Nov 2, 2010
More decks from Noranda Aluminum Holding Corp
 Q3 2015 Earnings Presentation10 slides · Nov 9, 2015
 Q2 2015 Earnings Presentation11 slides · Jul 22, 2015
 Q1 2015 Earnings Presentation15 slides · May 6, 2015
 Q4 2014 Earnings Presentation15 slides · Feb 18, 2015
 Q3 2014 Earnings Presentation15 slides · Nov 3, 2014
 Q2 2014 Earnings Presentation16 slides · Aug 11, 2014