Susquehanna Bancshares — Investor Presentation (February 2013)
37 slides from Susquehanna Bancshares's investor presentation, Feb 6, 2013
Slide 1: Susquehanna Bancshares, Inc. Investor Presentation 1st Quarter 2013
Exhibit 99.1 Susquehanna Bancshares, Inc. Investor Presentation st 1 Quarter 2013
Slide 2: Forward-Looking Statements
Forward-Looking Statements During the course of this presentation, we may make projections and other forward-looking statements regarding priorities and strategic objectives of Susquehanna Bancshares, Inc., as well as projected capital ratios, efficiency ratios, net income and earnings. We encourage
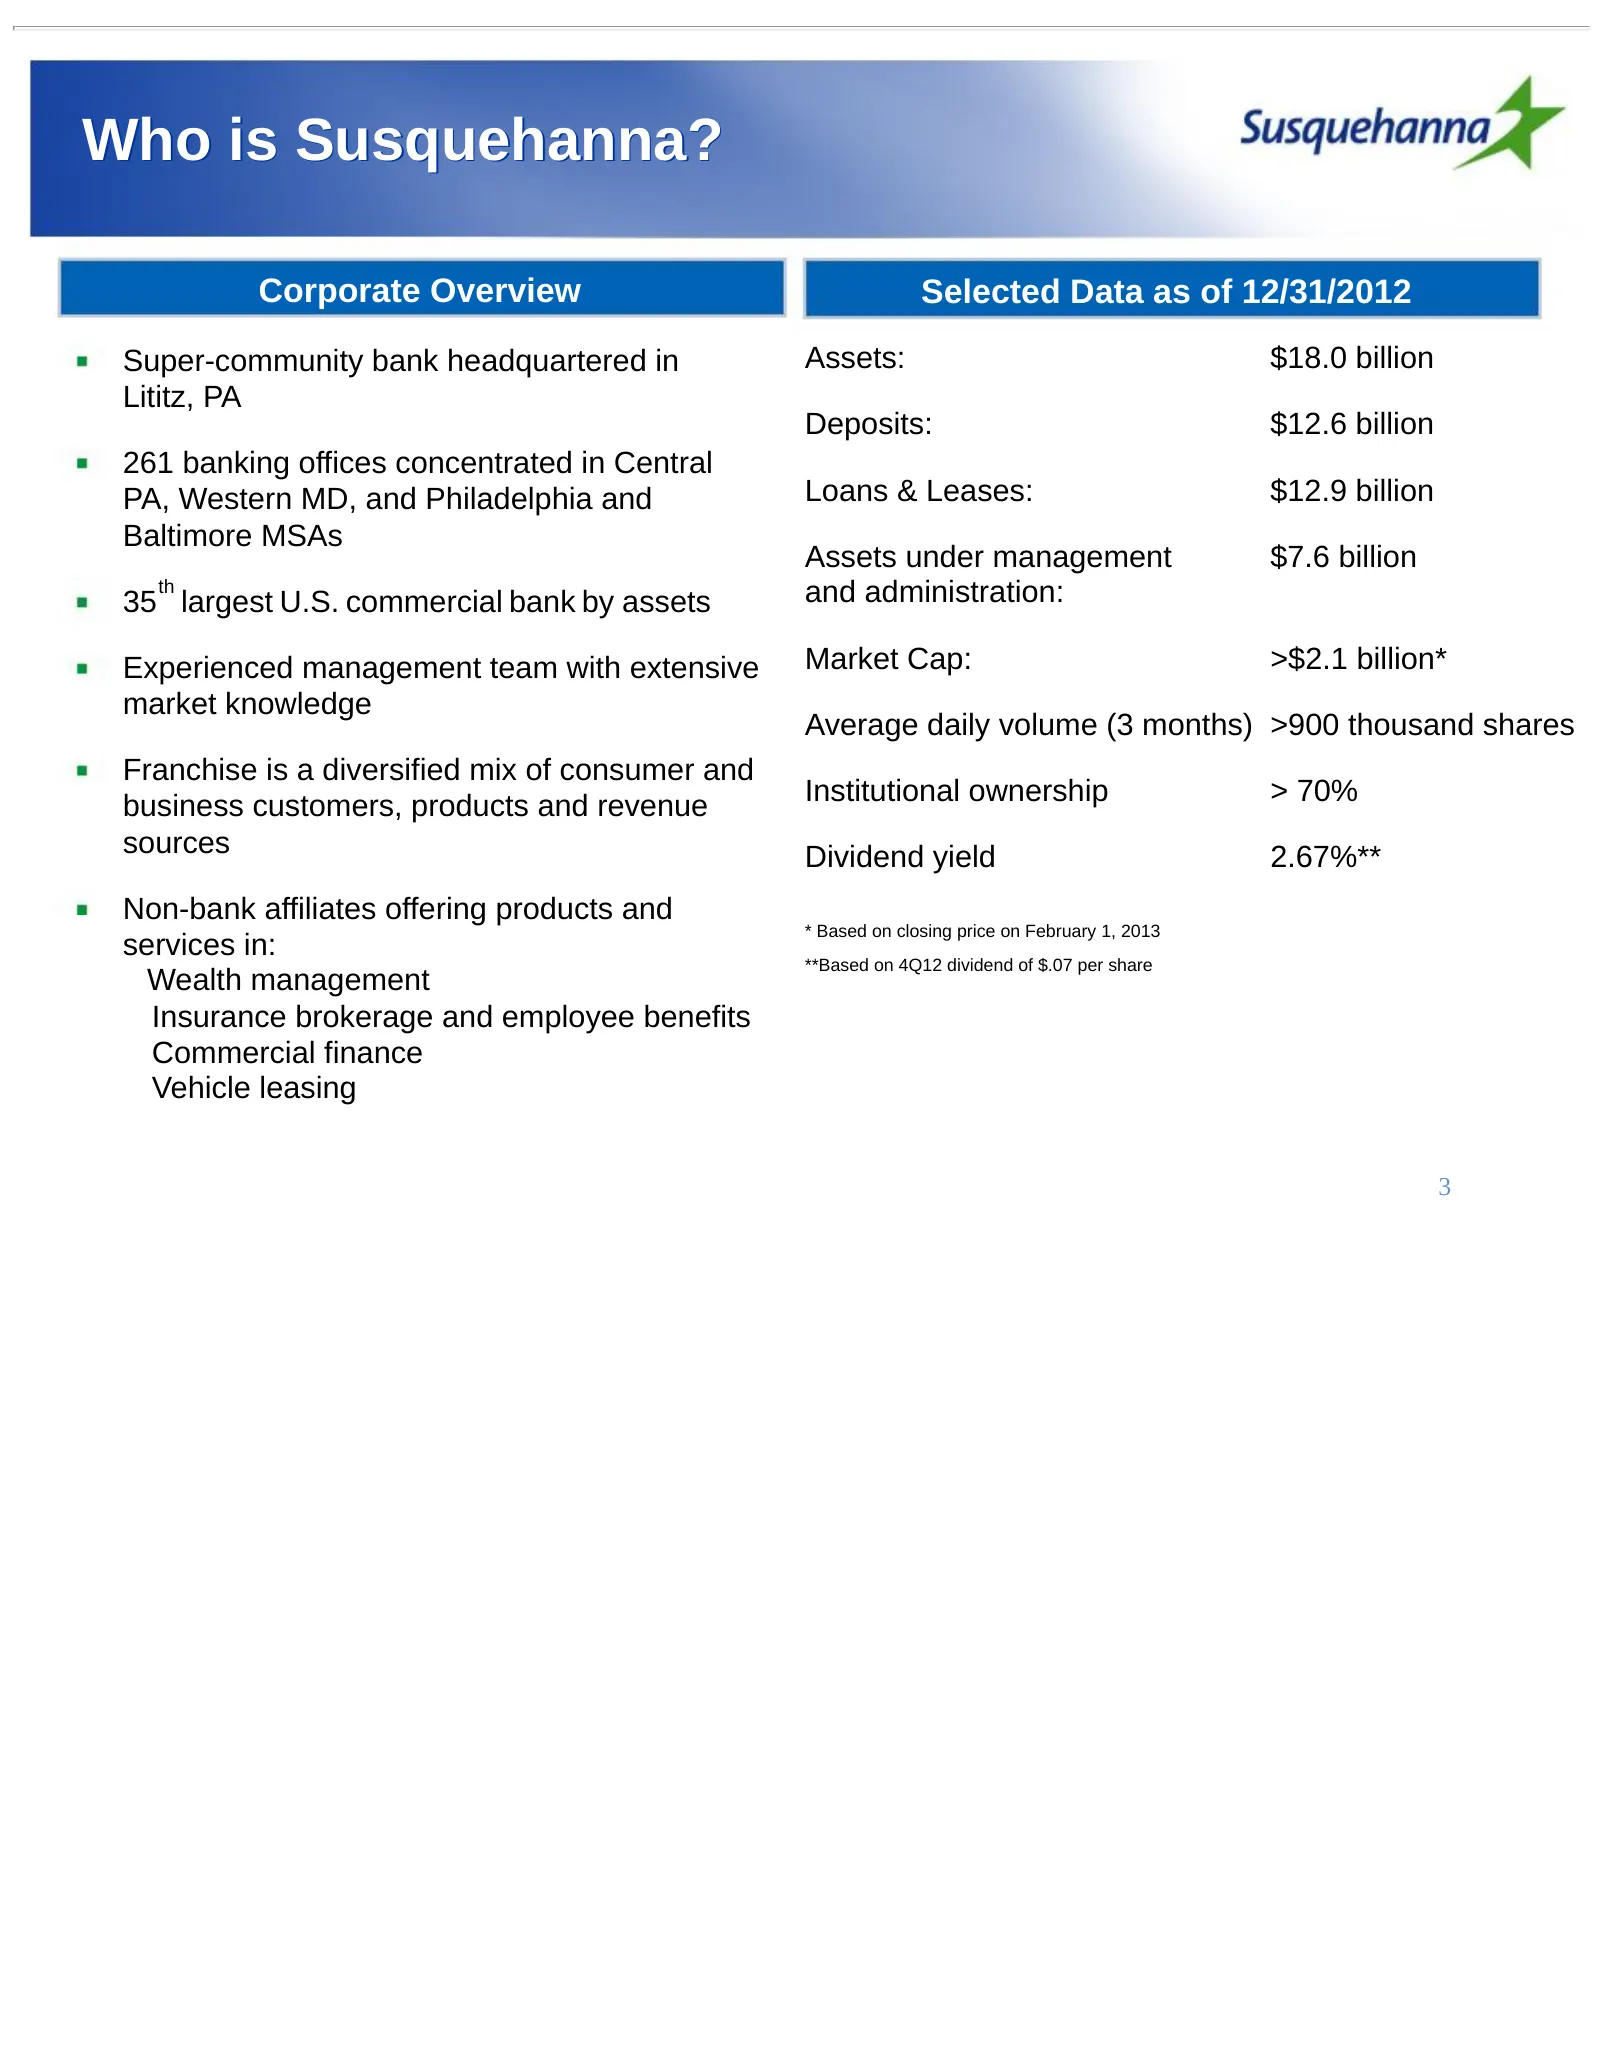
Slide 3: Who is Susquehanna?
Who is Susquehanna? Corporate Overview Selected Data as of 12/31/2012 Super-community bank headquartered in Assets: $18.0 billion Lititz, PA Deposits: $12.6 billion 261 banking offices concentrated in Central PA, Western MD, and Philadelphia and Loans & Leases: $12.9 billion Baltimore MSAs Assets un
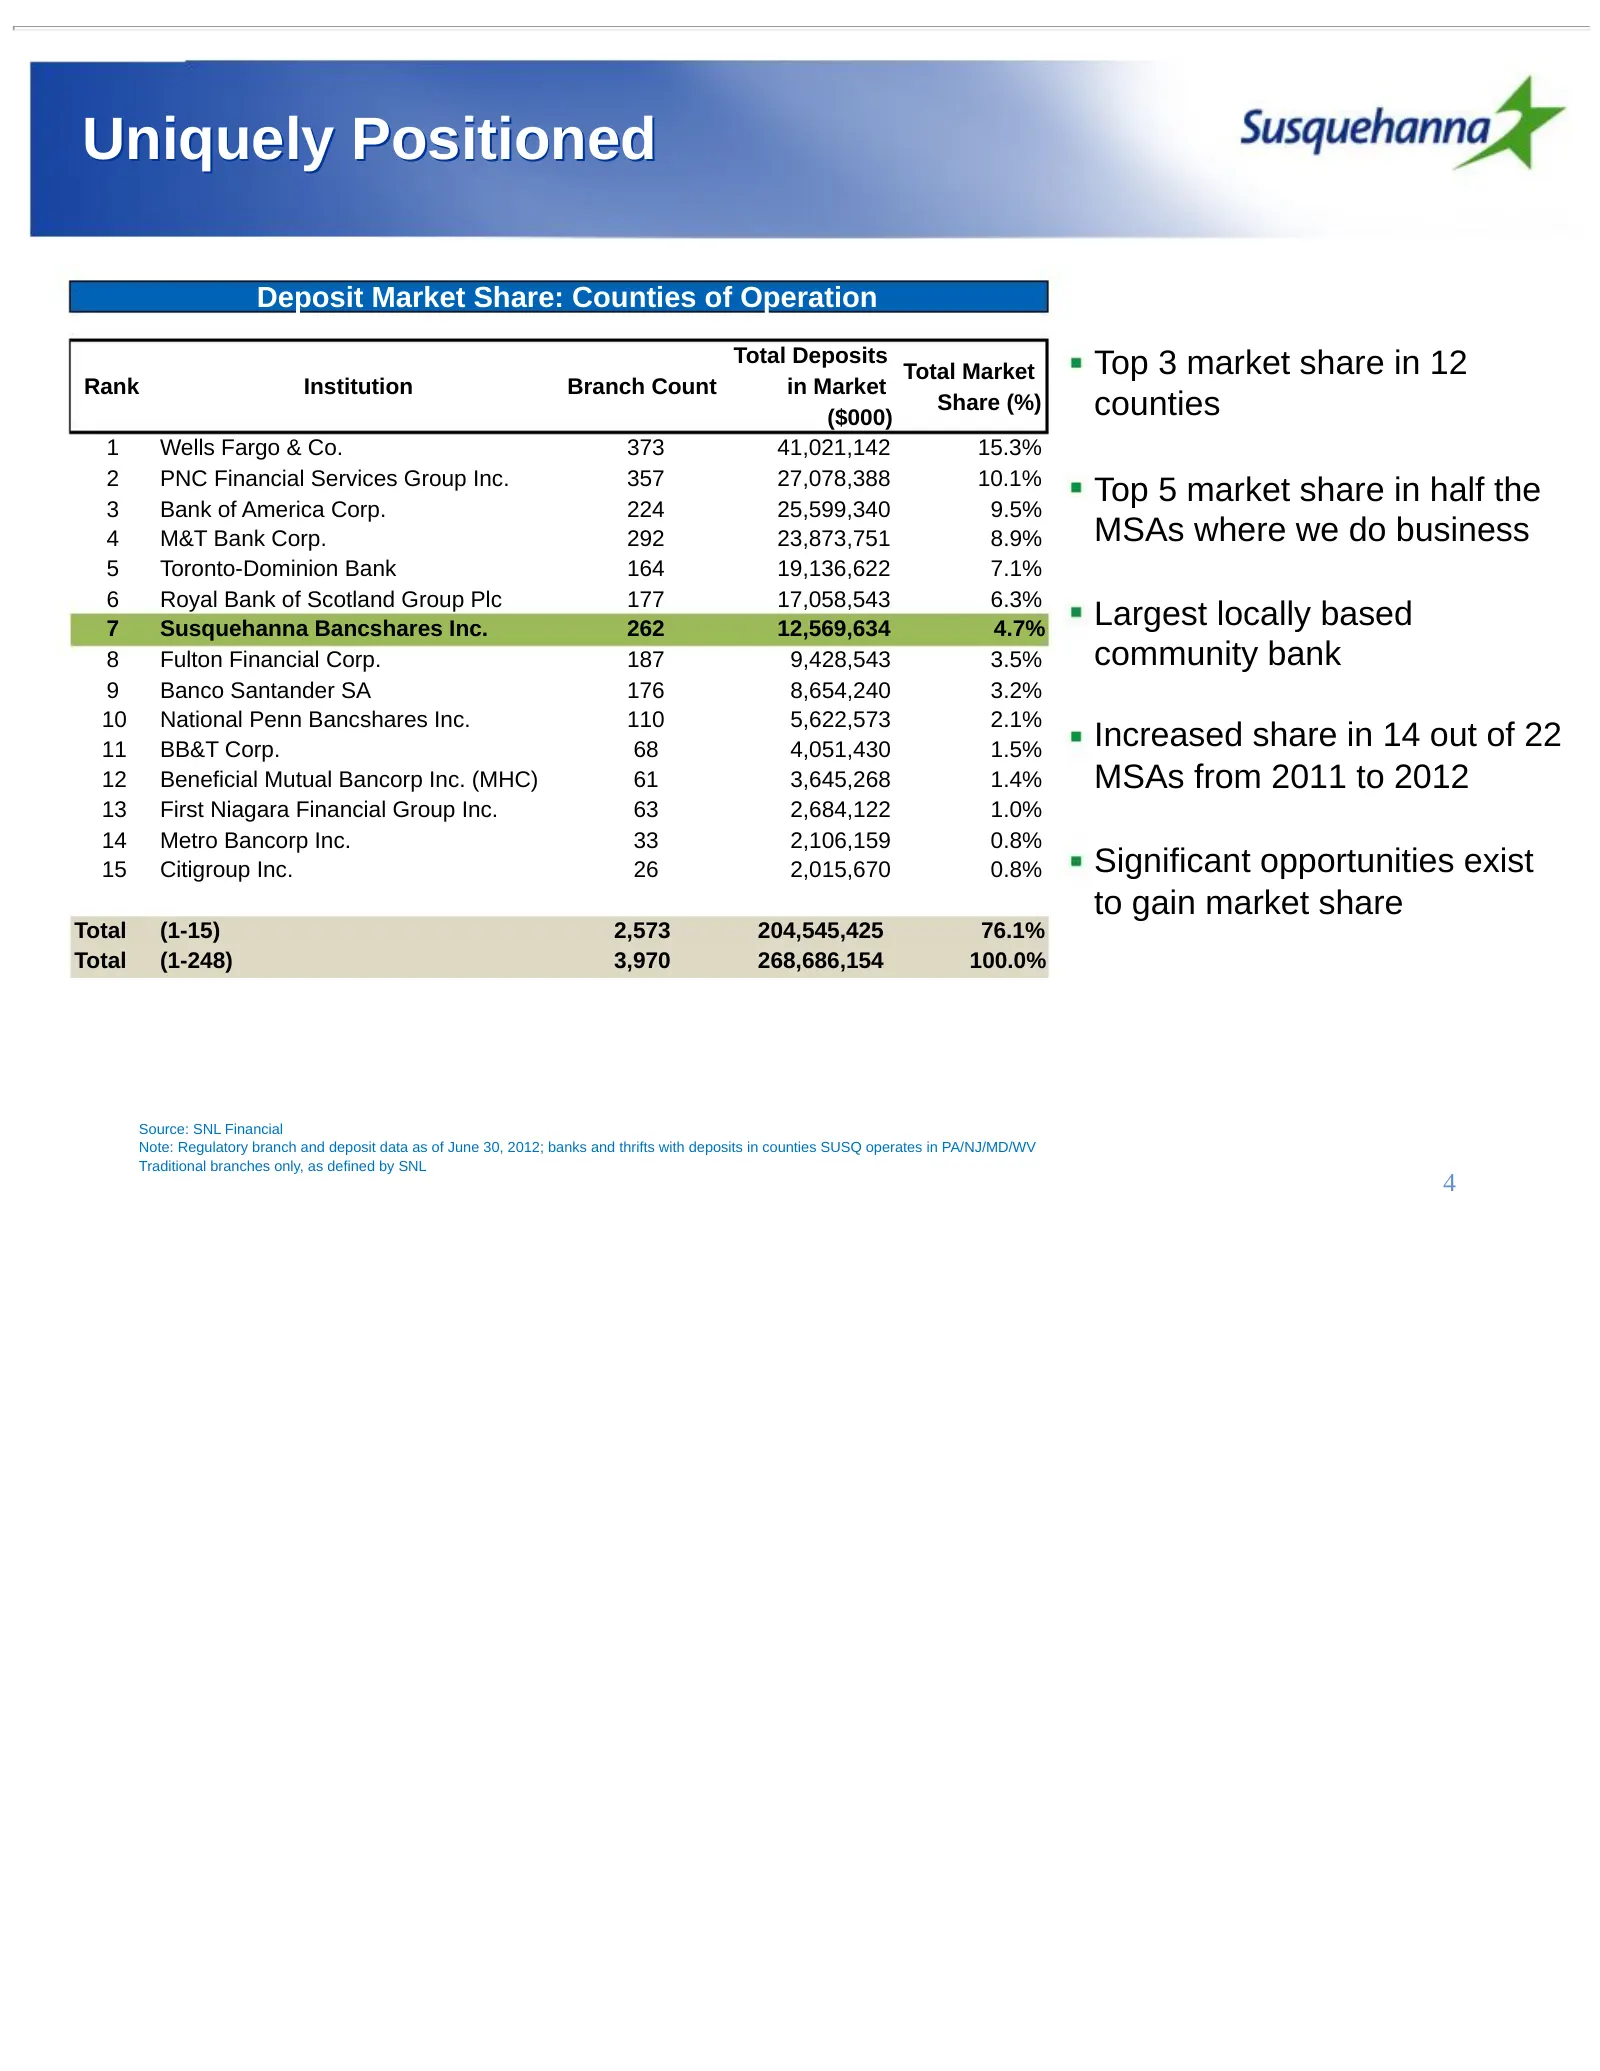
Slide 4: Uniquely Positioned
Uniquely Positioned Deposit Market Share: Counties of Operation Total Deposits Top 3 market share in 12 Total Market Rank Institution Branch Count in Market ($000) Share (%) counties 1 Wells Fargo & Co. 373 41,021,142 15.3% 2 PNC Financial Services Group Inc. 357 27,078,388 10.1% 3 Bank of America C
Slide 5: 2012 in Review: Delivering on our Commitments
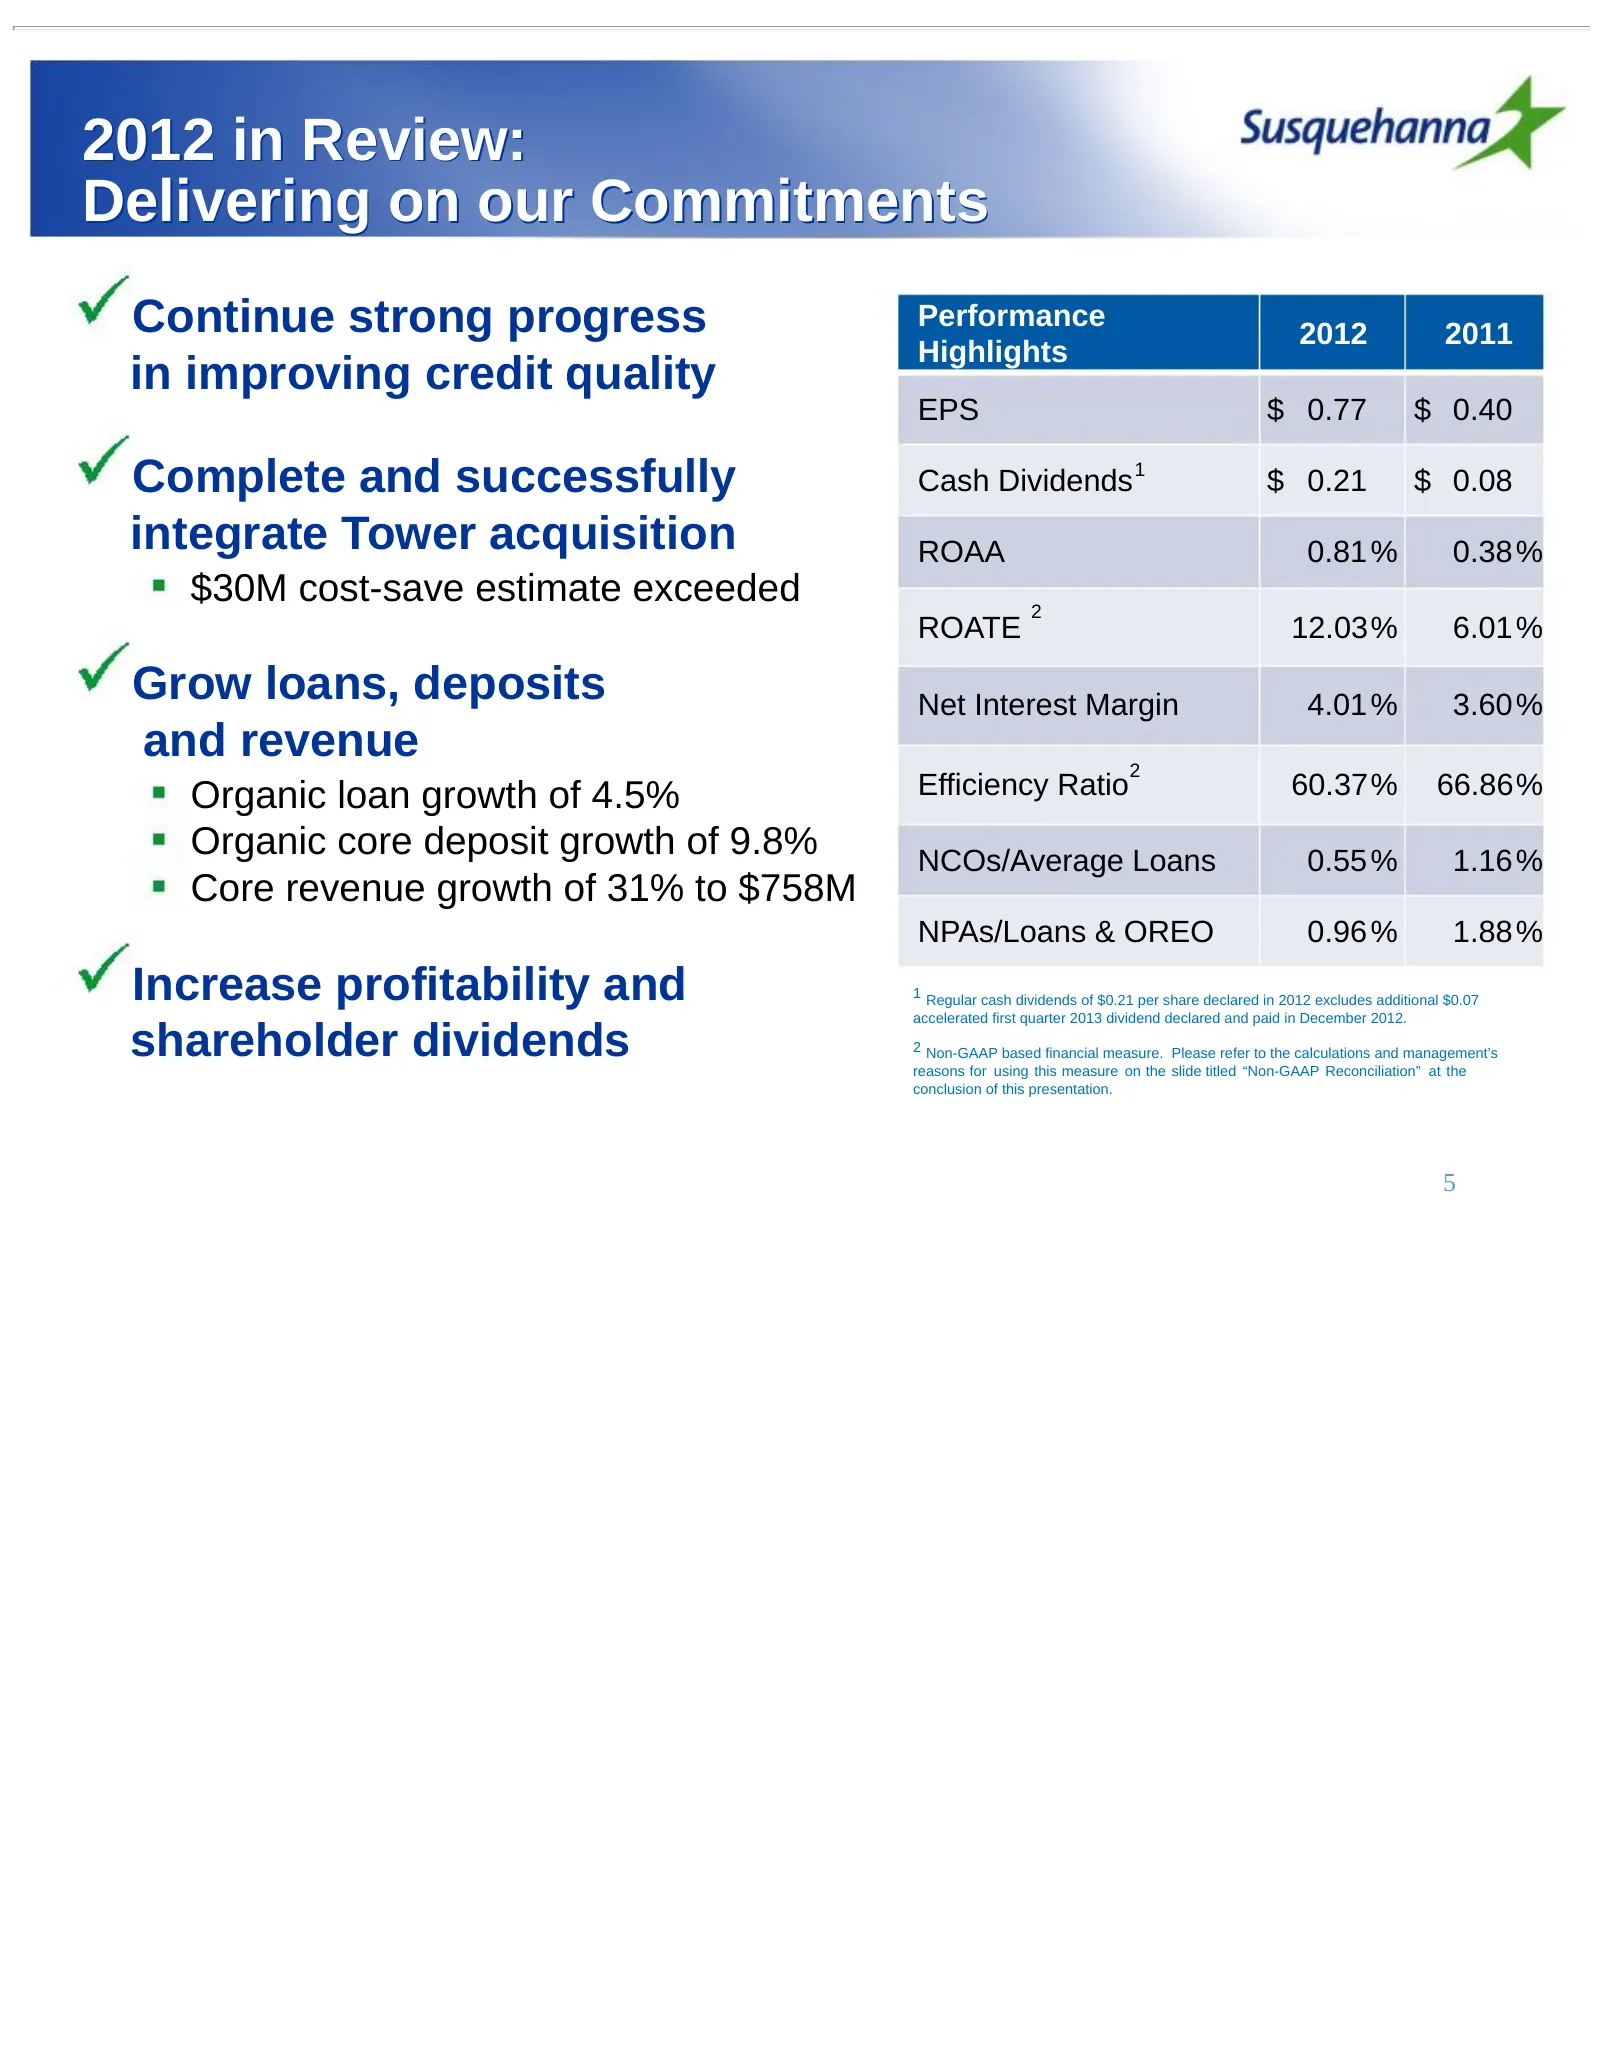
2012 in Review: Delivering on our Commitments Continue strong progress Performance 2012 2011 Highlights in improving credit quality EPS $ 0.77 $ 0.40 Complete and successfully Cash Dividends 1 $ 0.21 $ 0.08 integrate Tower acquisition ROAA 0.81 % 0.38 % $30M cost-save estimate exceeded 2 ROATE 12.03
Slide 6: 4th Quarter 2012 Highlights
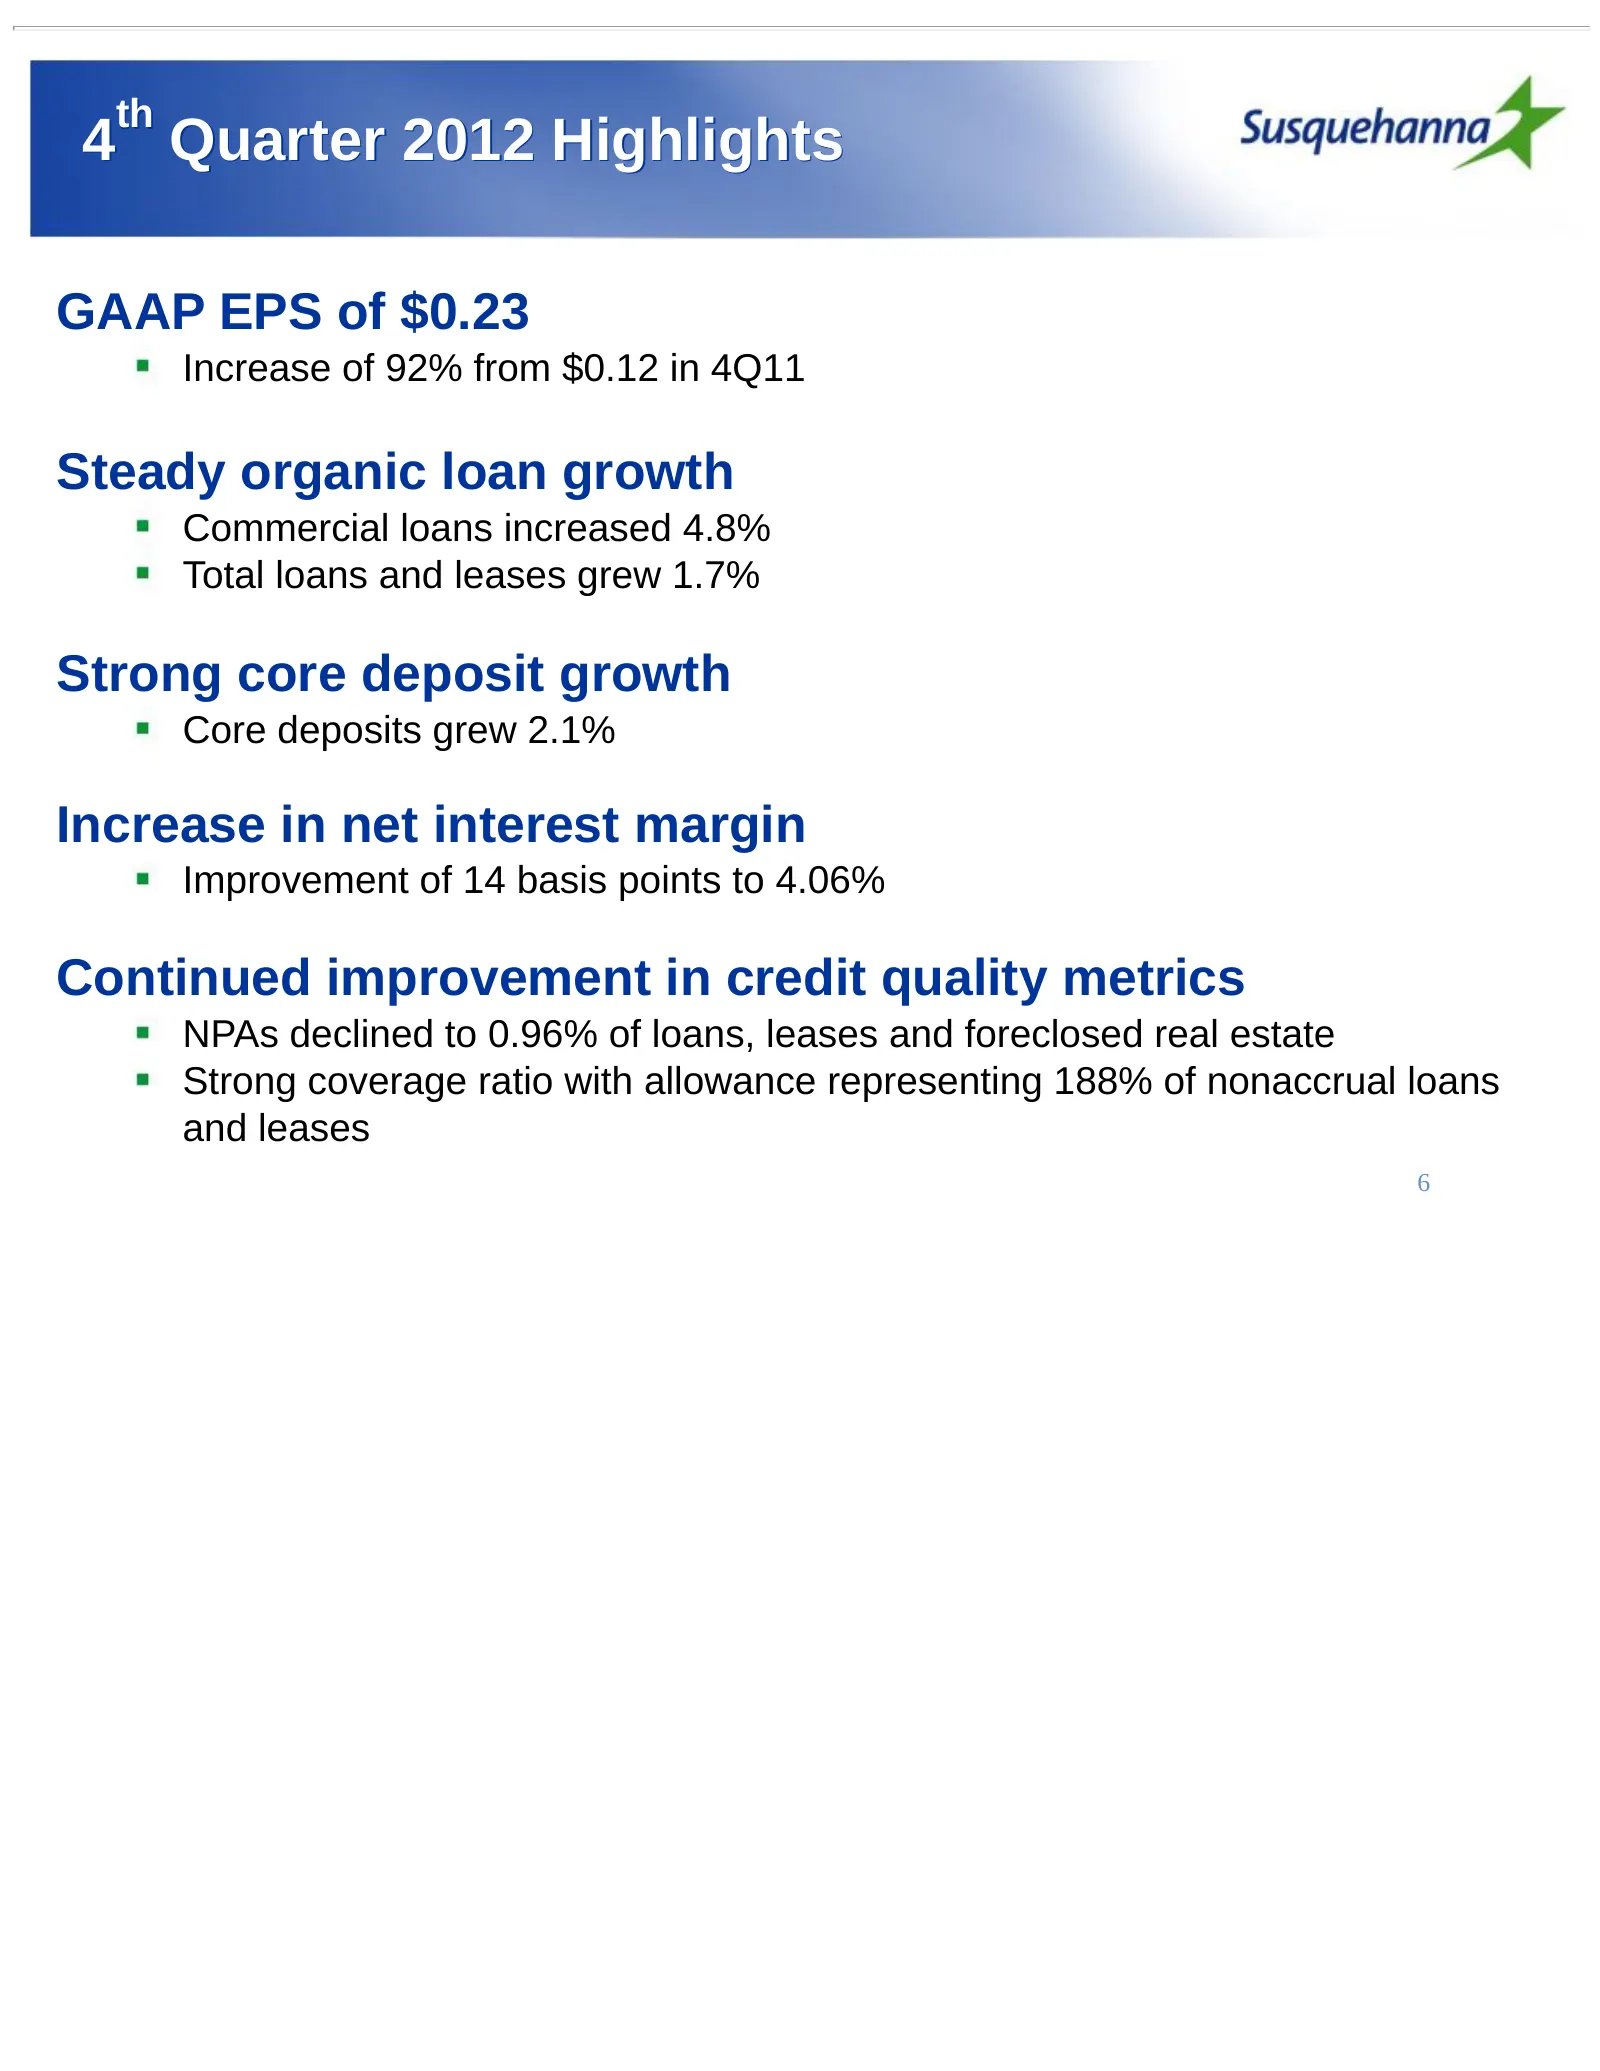
th 4 Quarter 2012 Highlights GAAP EPS of $0.23 Increase of 92% from $0.12 in 4Q11 Steady organic loan growth Commercial loans increased 4.8% Total loans and leases grew 1.7% Strong core deposit growth Core deposits grew 2.1% Increase in net interest margin Improvement of 14 basis points to 4.06% Con
Slide 7: Building on Momentum
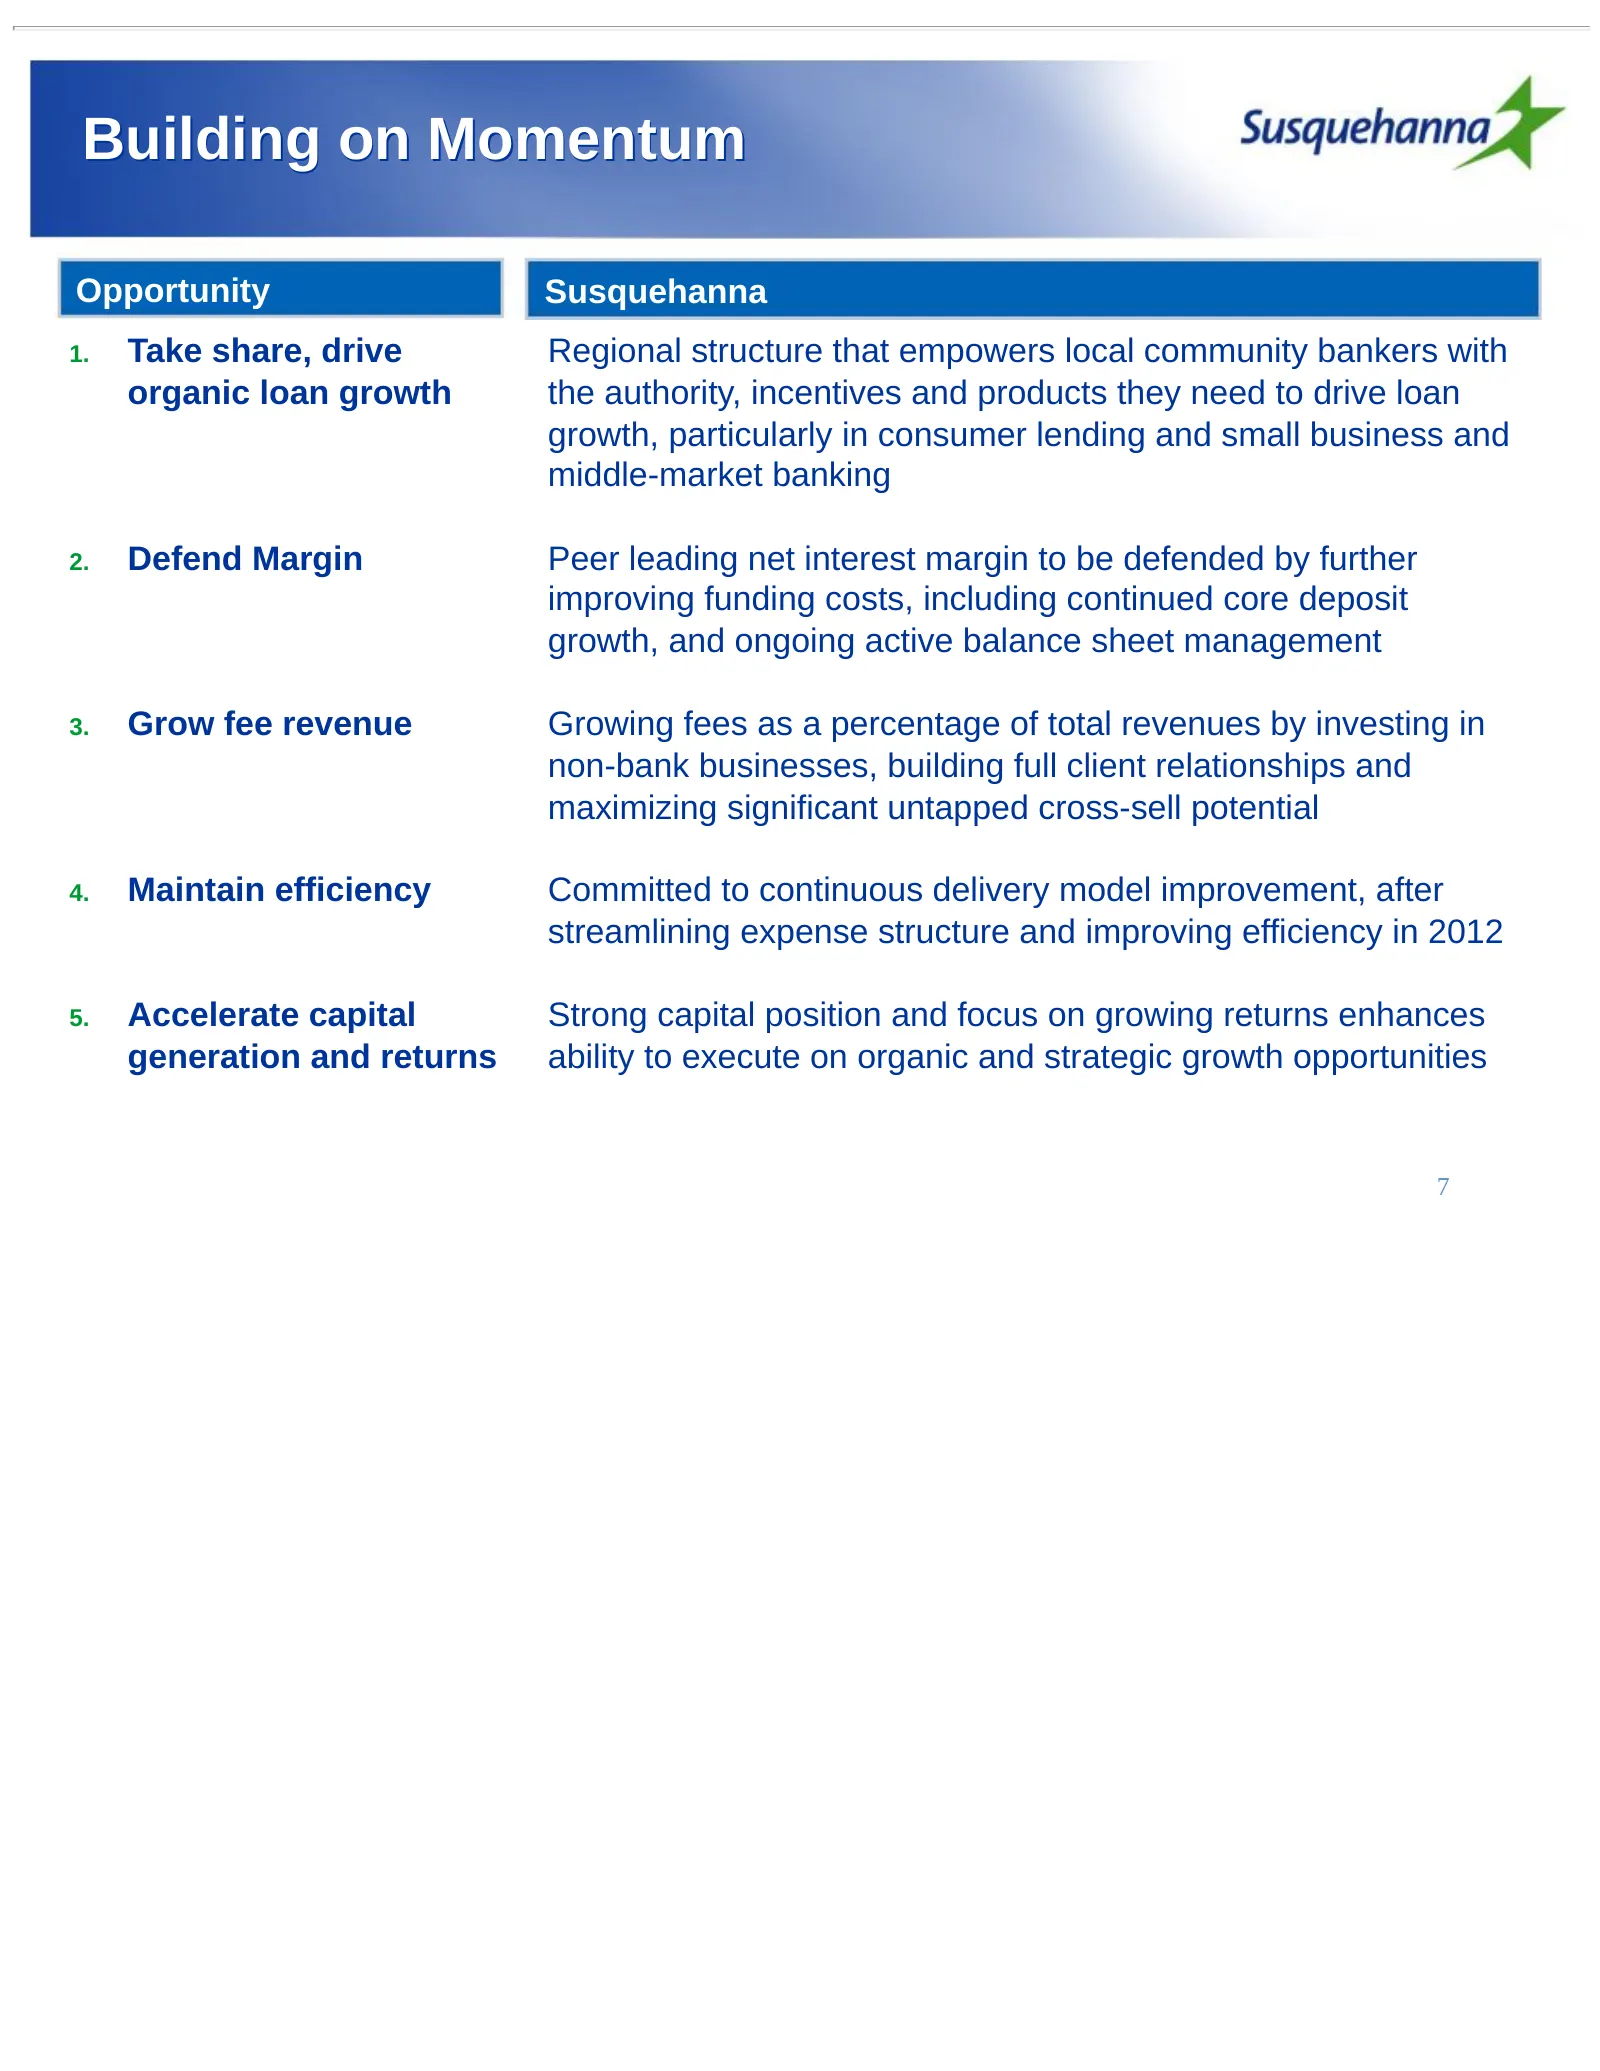
Building on Momentum Opportunity Susquehanna 1. Take share, drive Regional structure that empowers local community bankers with organic loan growth the authority, incentives and products they need to drive loan growth, particularly in consumer lending and small business and middle-market banking 2.
Slide 8: Focus for 2013
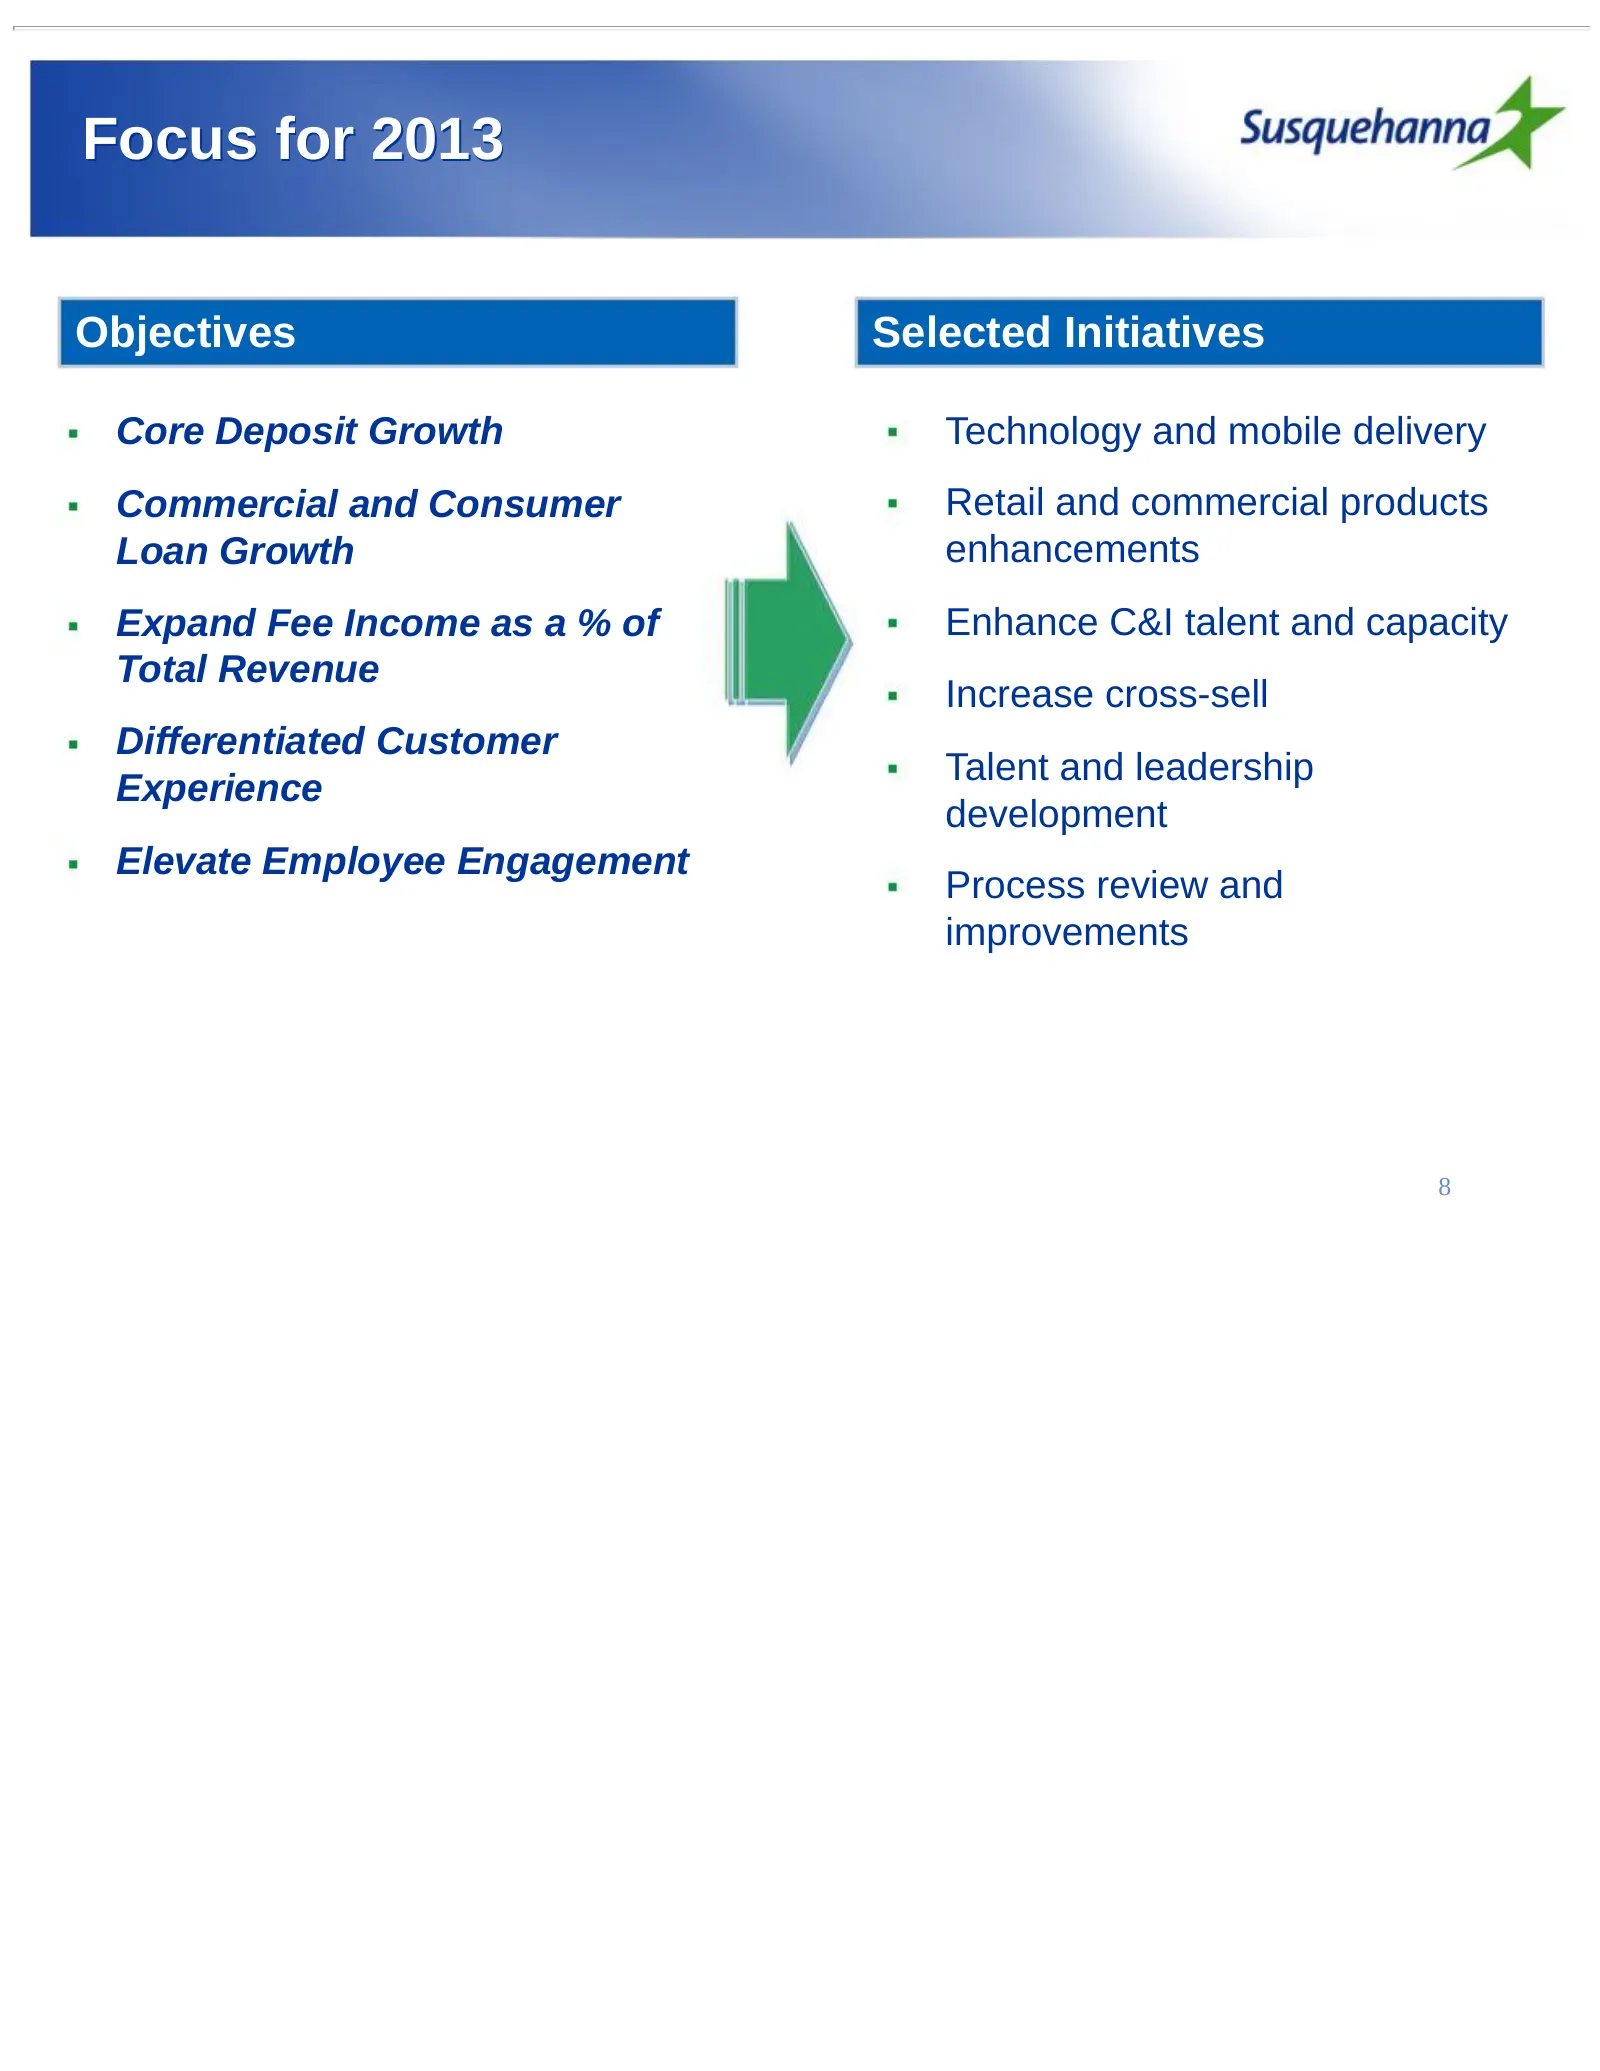
Focus for 2013 Objectives Selected Initiatives Core Deposit Growth Technology and mobile delivery Commercial and Consumer Retail and commercial products Loan Growth enhancements Expand Fee Income as a % of Enhance C&I talent and capacity Total Revenue Increase cross-sell Differentiated Customer Tale
Slide 9: Loan Growth
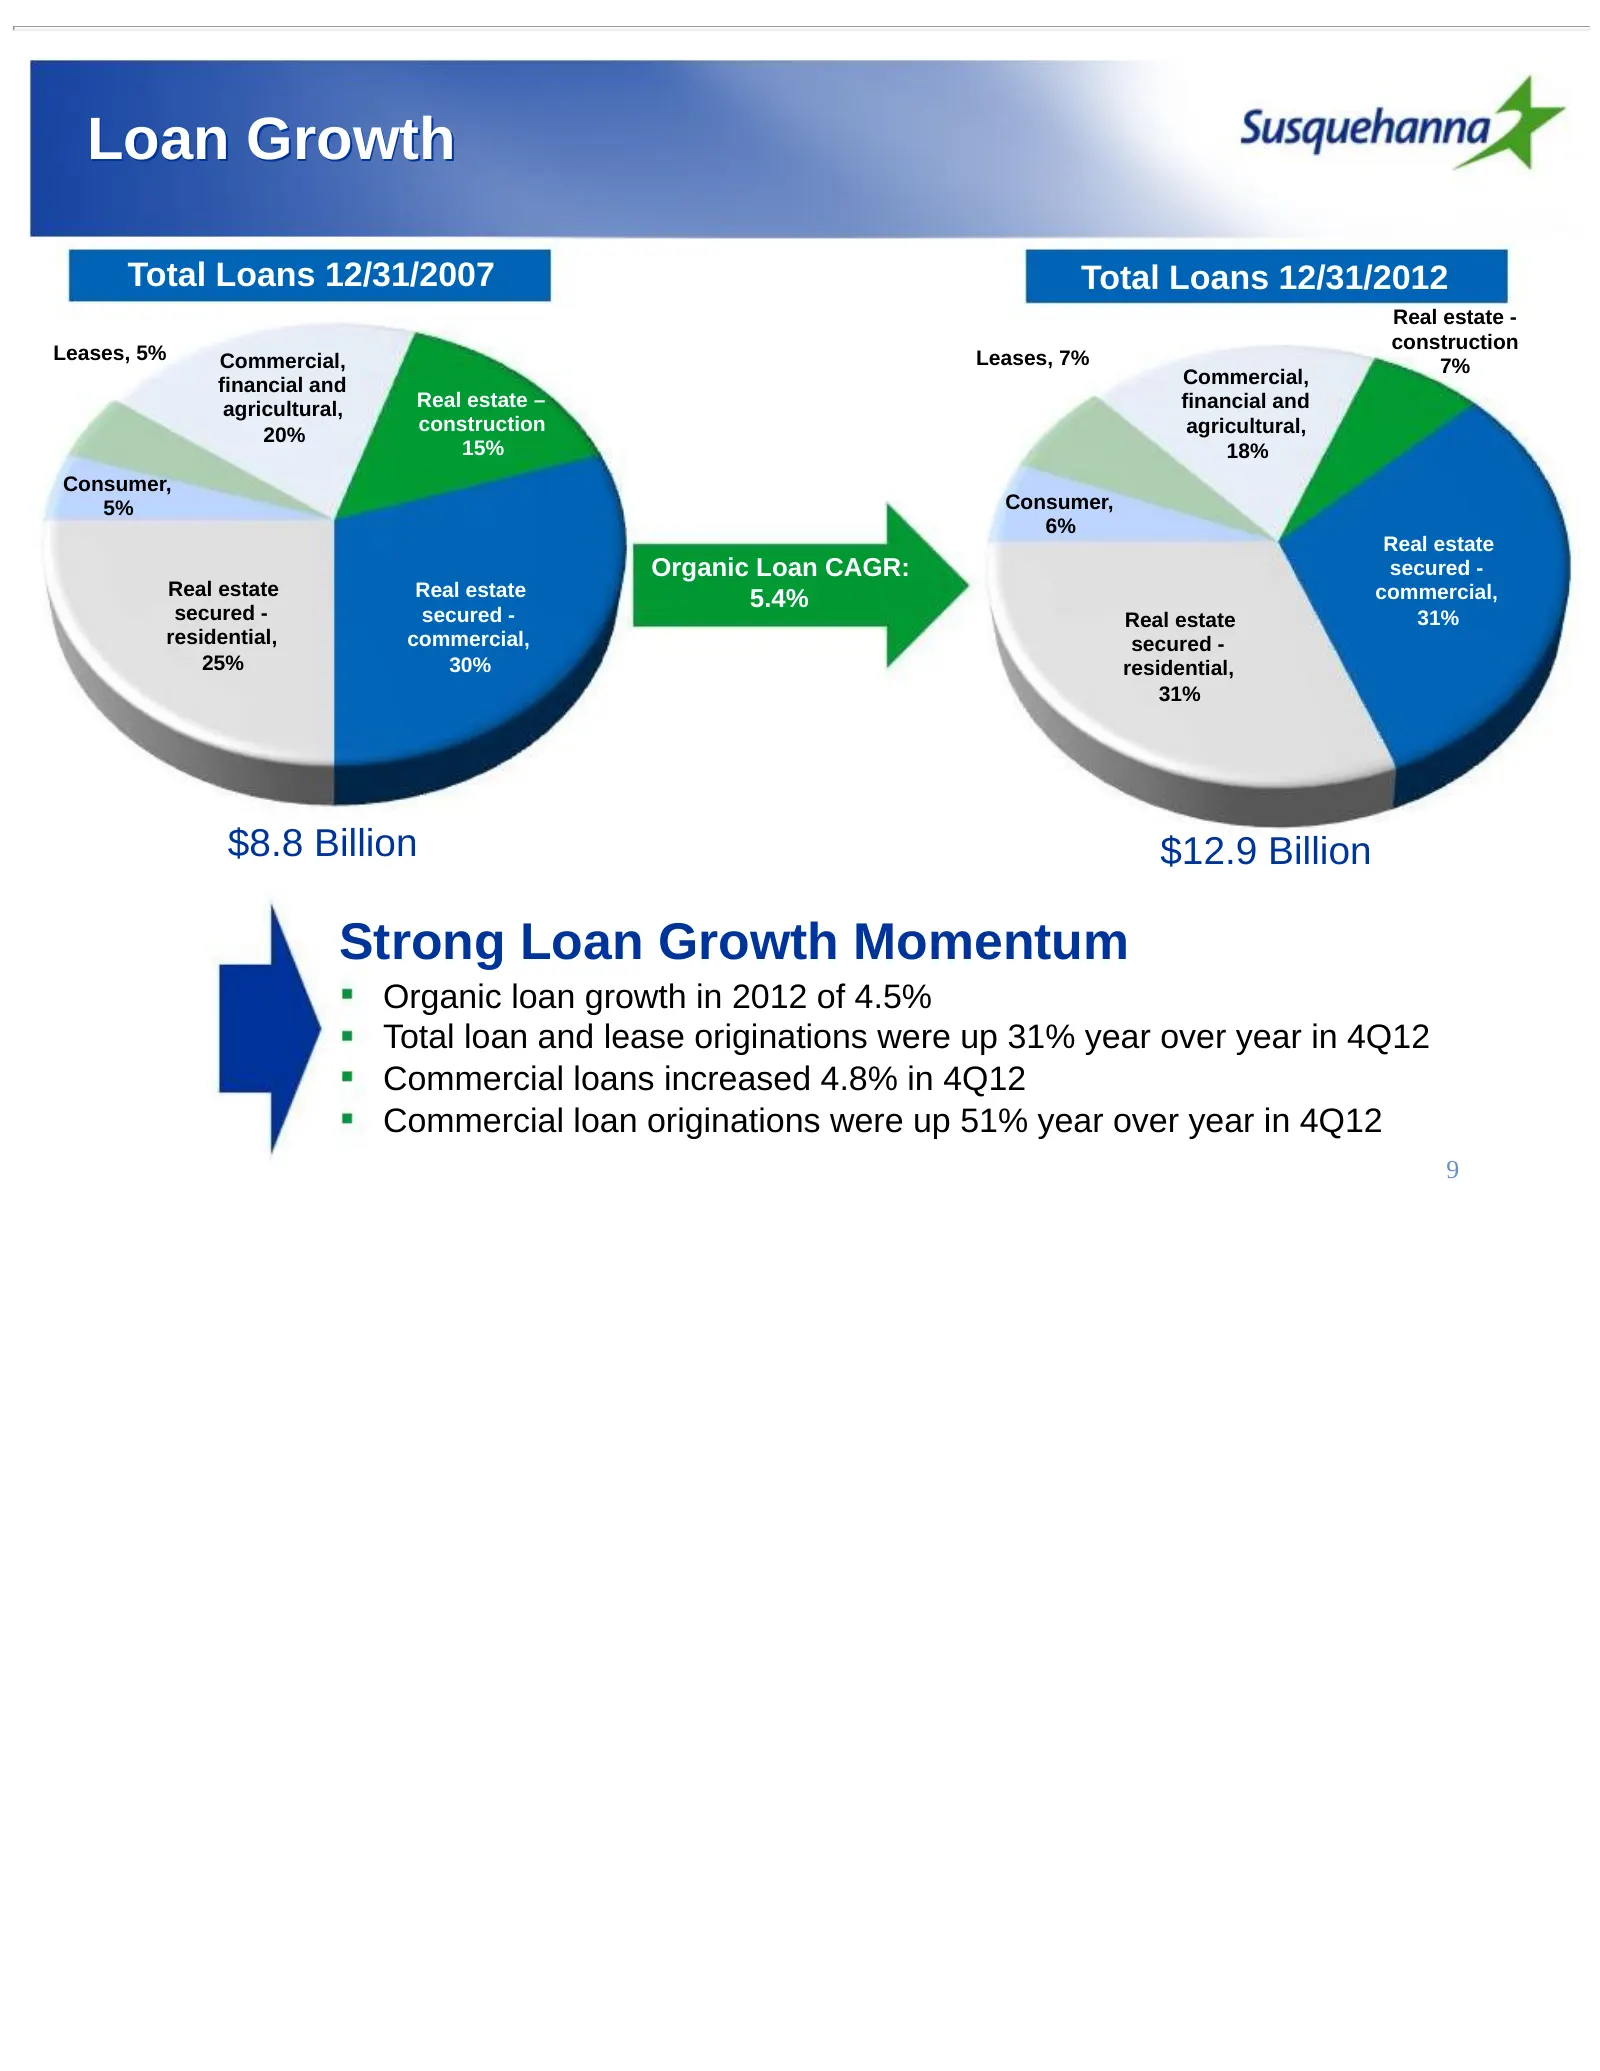
Loan Growth Total Loans 12/31/2007 Total Loans 12/31/2012 Real estate - construction Leases, 5% Commercial, Leases, 7% 7% financial and Commercial, agricultural, Real estate – financial and construction agricultural, 20% 15% 18% Consumer, 5% Consumer, 6% Real estate Organic Loan CAGR: secured - Real
Slide 10: Asset Quality Continues to Improve
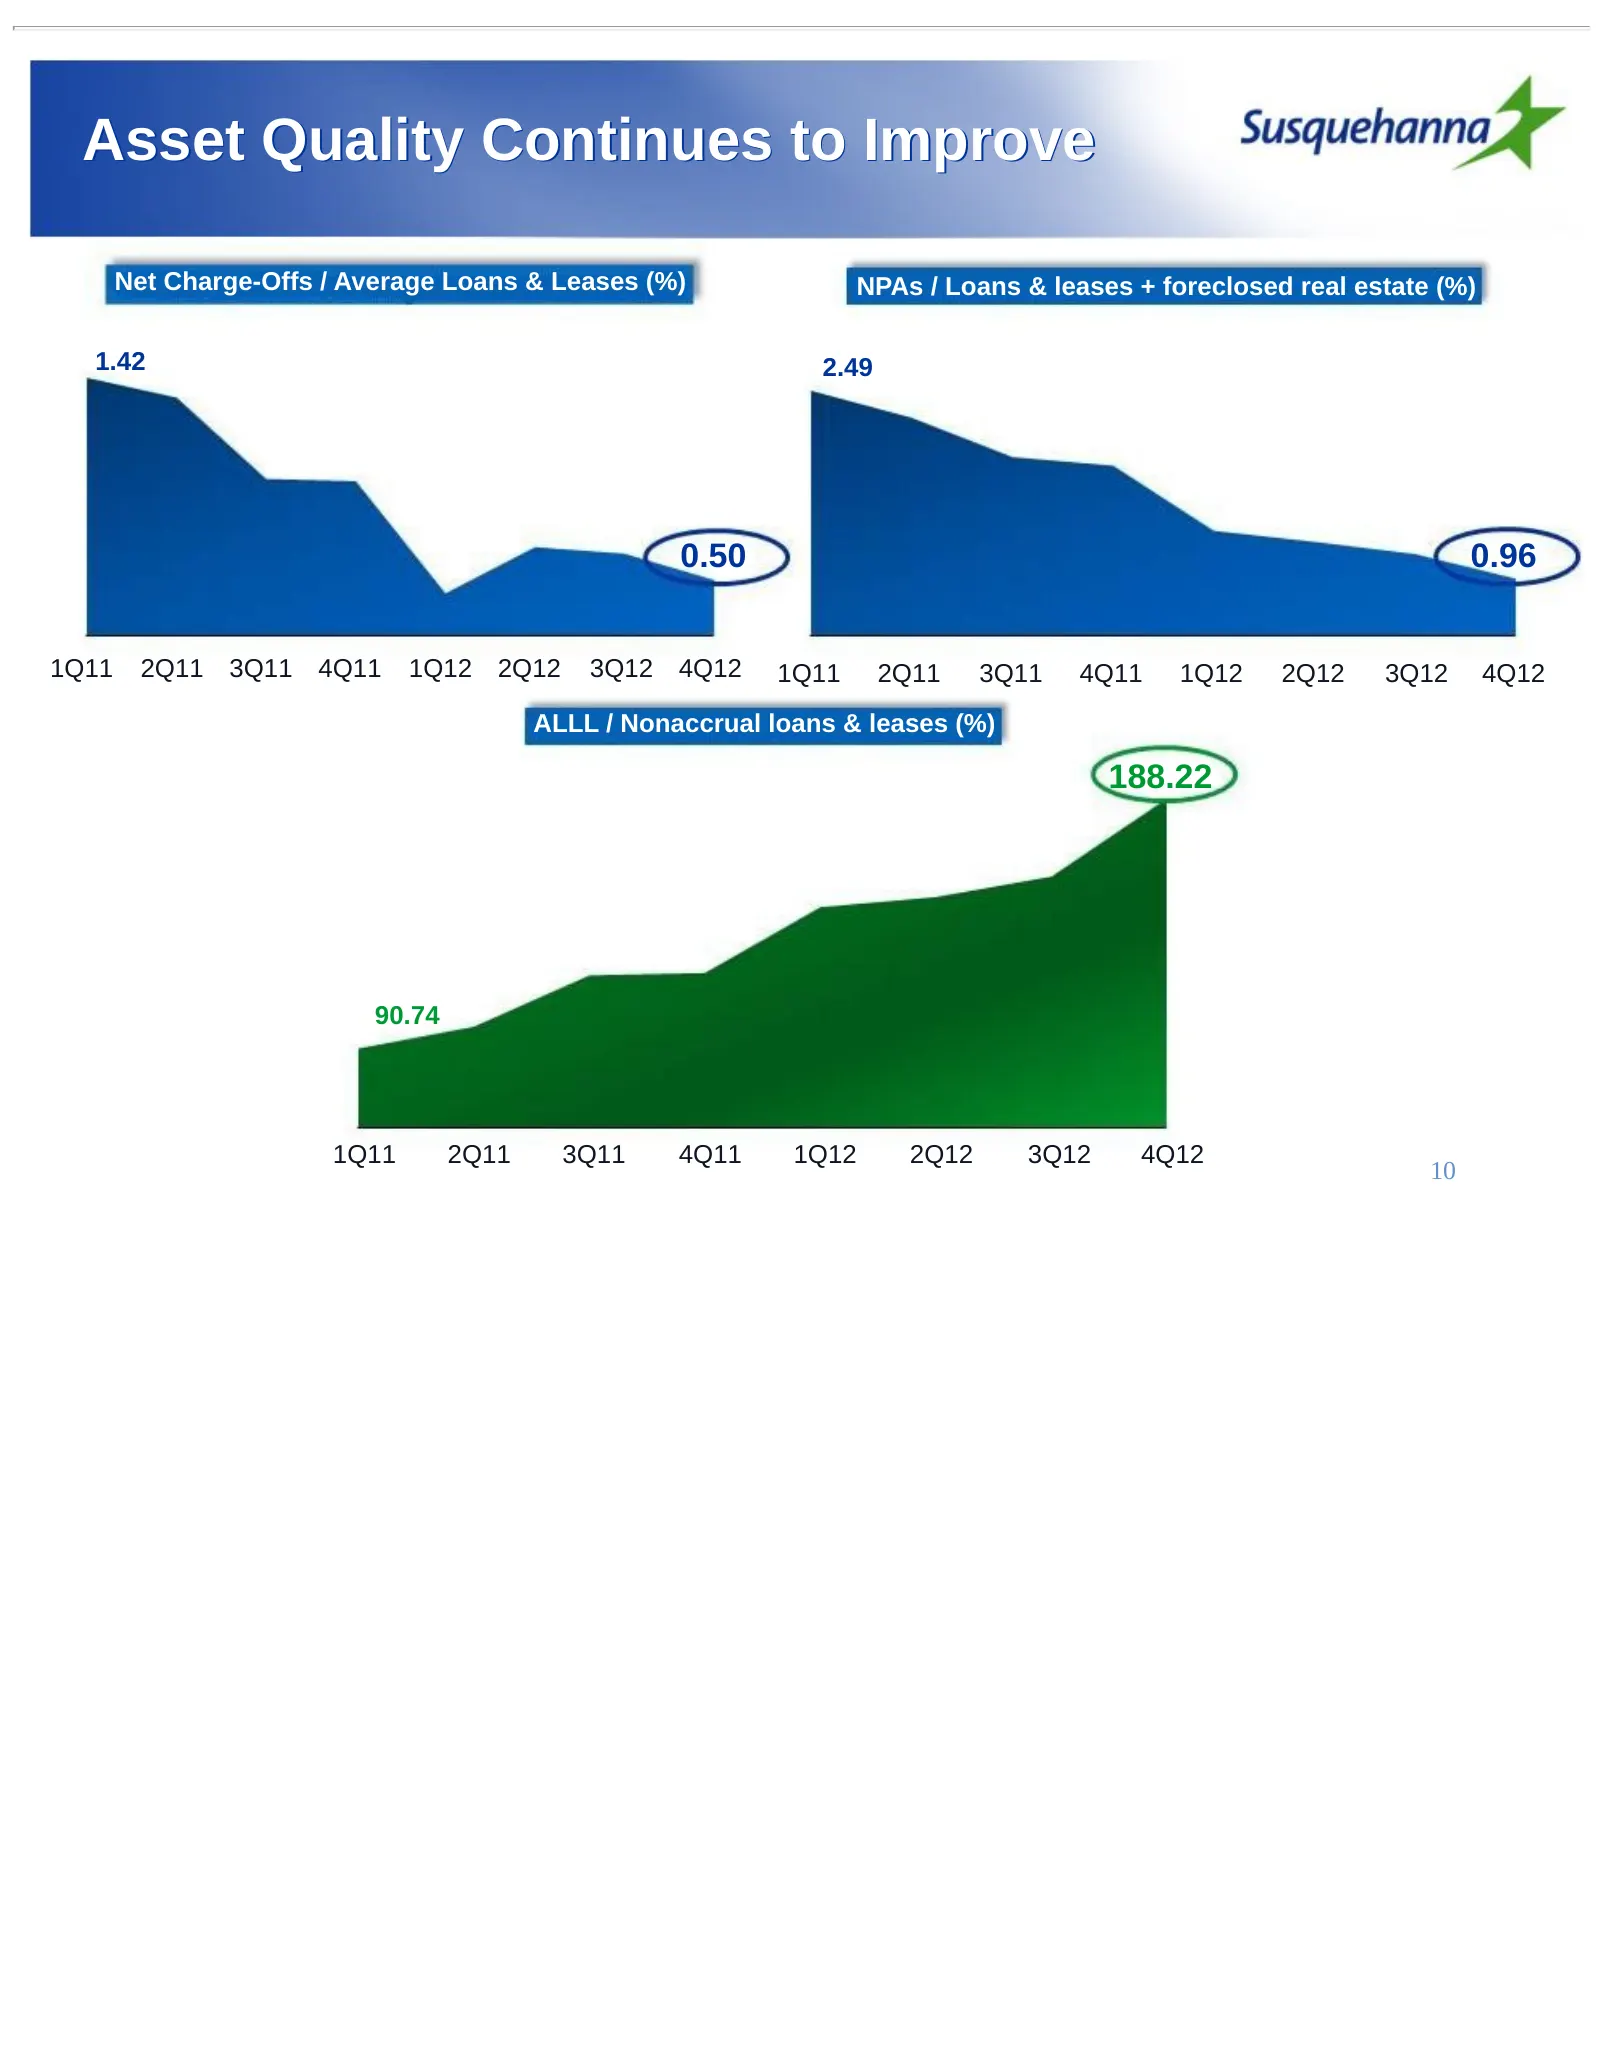
Asset Quality Continues to Improve Net Charge-Offs / Average Loans & Leases (%) NPAs / Loans & leases + foreclosed real estate (%) 1.42 2.49 0.50 0.96 1Q11 2Q11 3Q11 4Q11 1Q12 2Q12 3Q12 4Q12 1Q11 2Q11 3Q11 4Q11 1Q12 2Q12 3Q12 4Q12 ALLL / Nonaccrual loans & leases (%) 188.22 90.74 1Q11 2Q11 3Q11 4Q11
Slide 11: Positioned For Further Growth
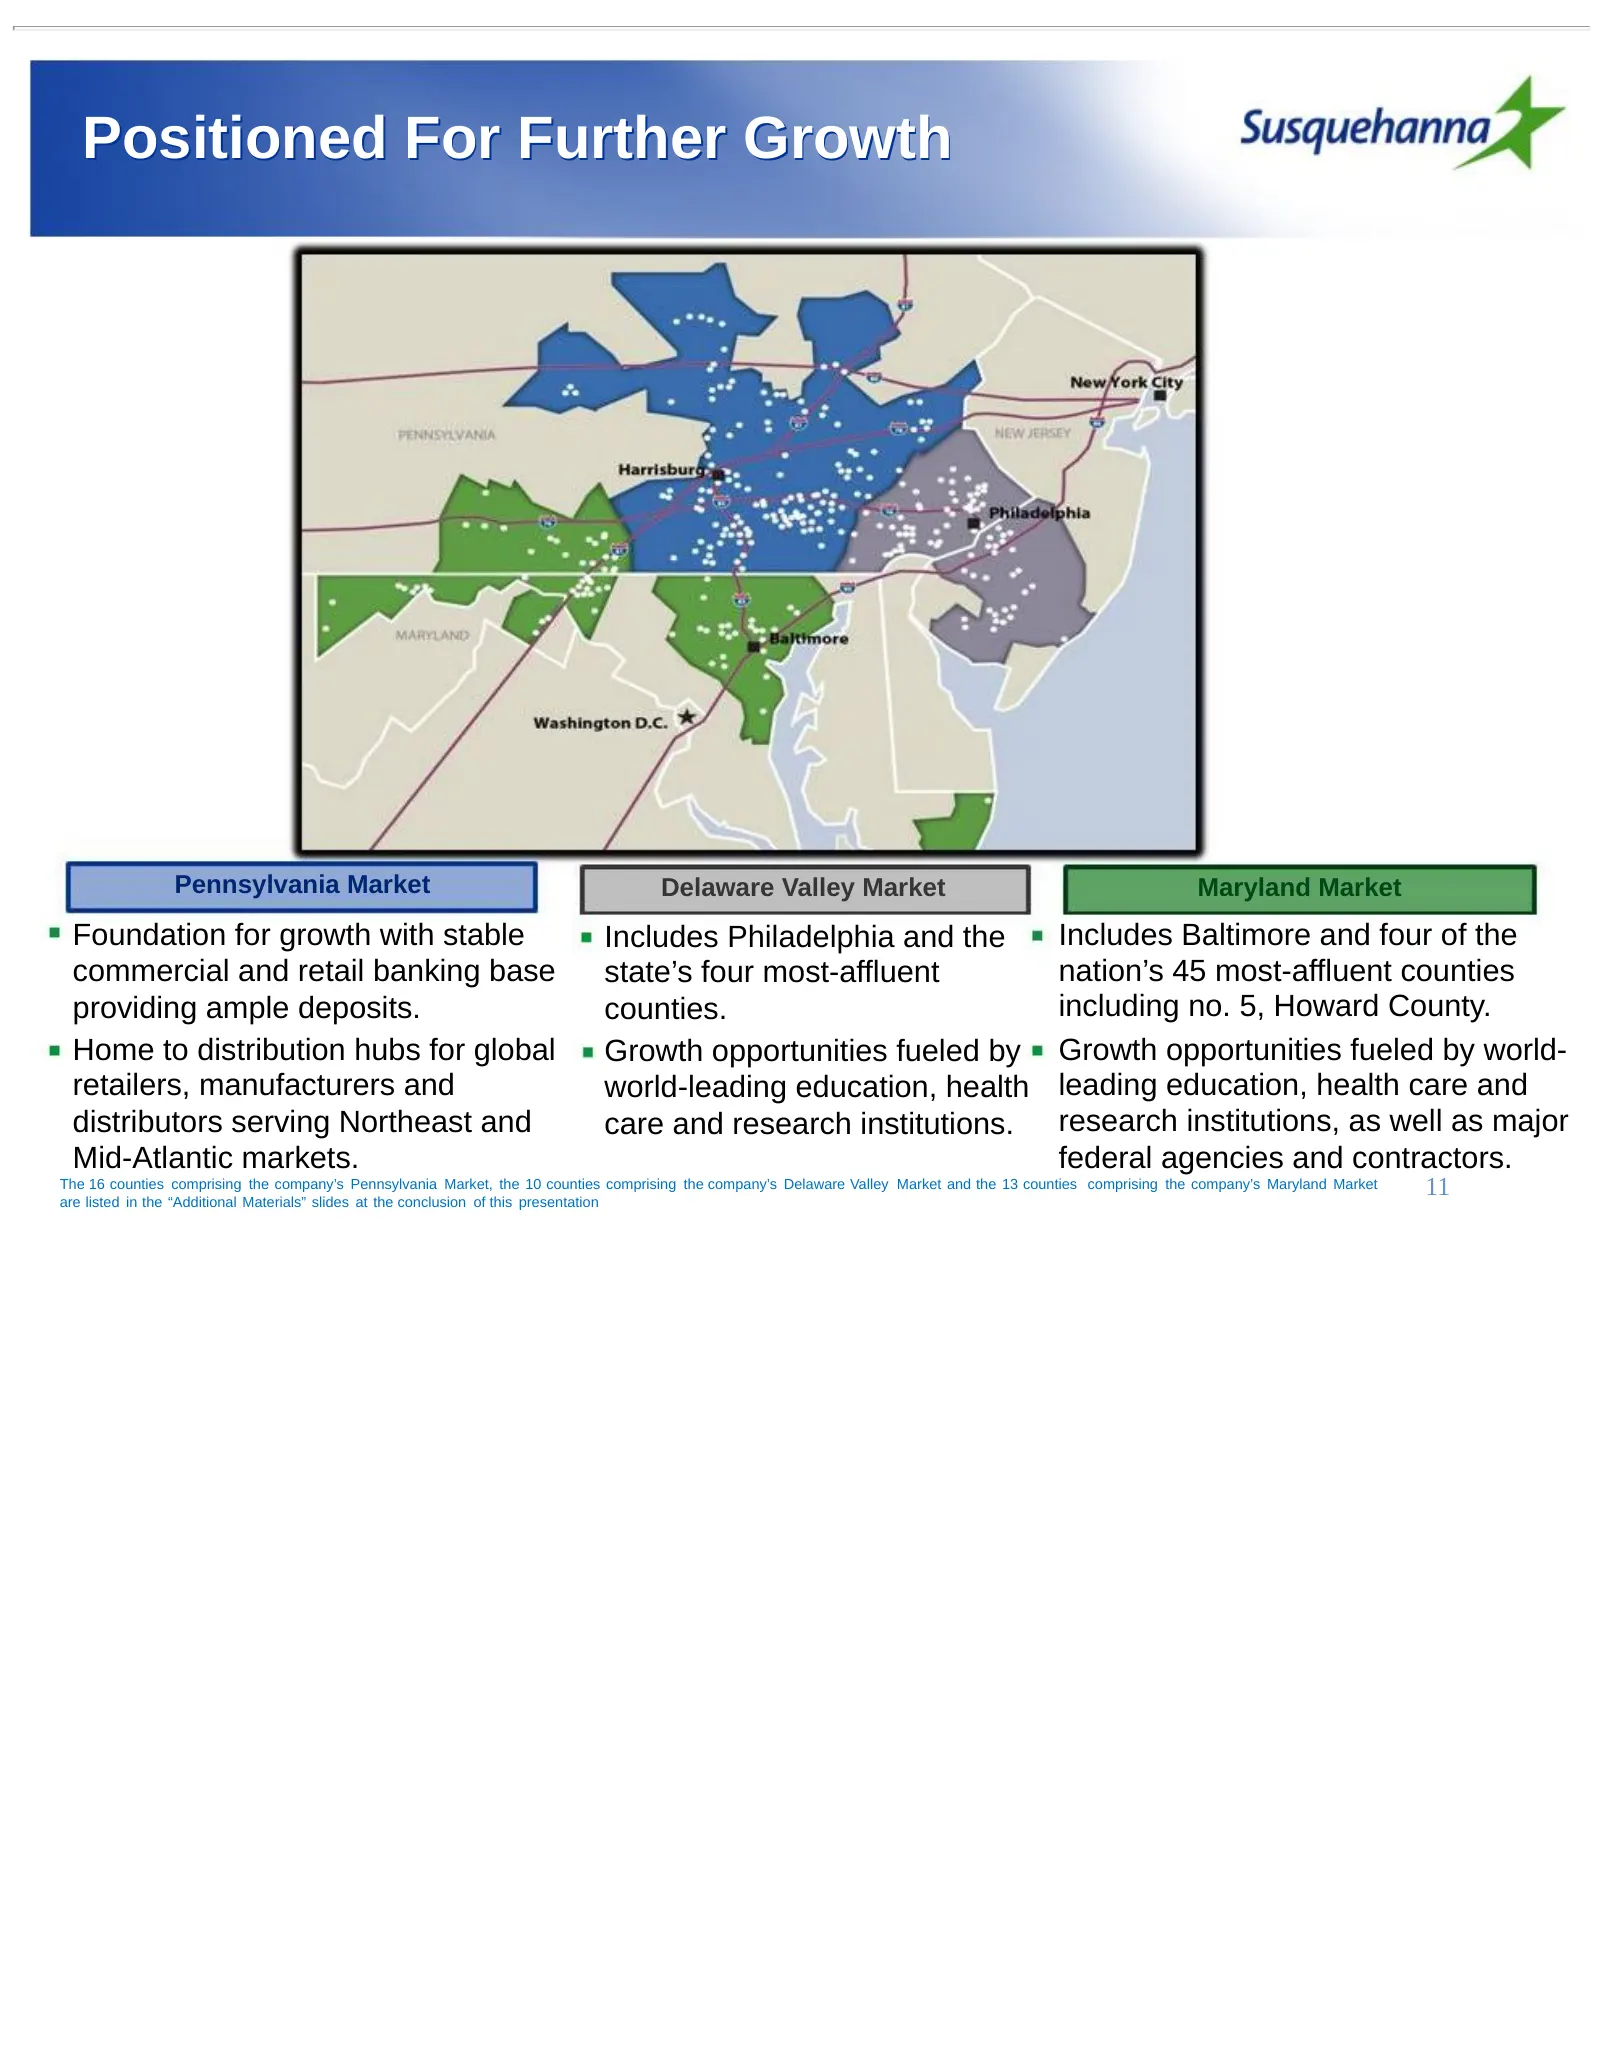
Positioned For Further Growth Pennsylvania Market Delaware Valley Market Maryland Market Foundation for growth with stable Includes Philadelphia and the Includes Baltimore and four of the commercial and retail banking base state’s four most-affluent nation’s 45 most-affluent counties providing ample
Slide 12: Market Opportunity
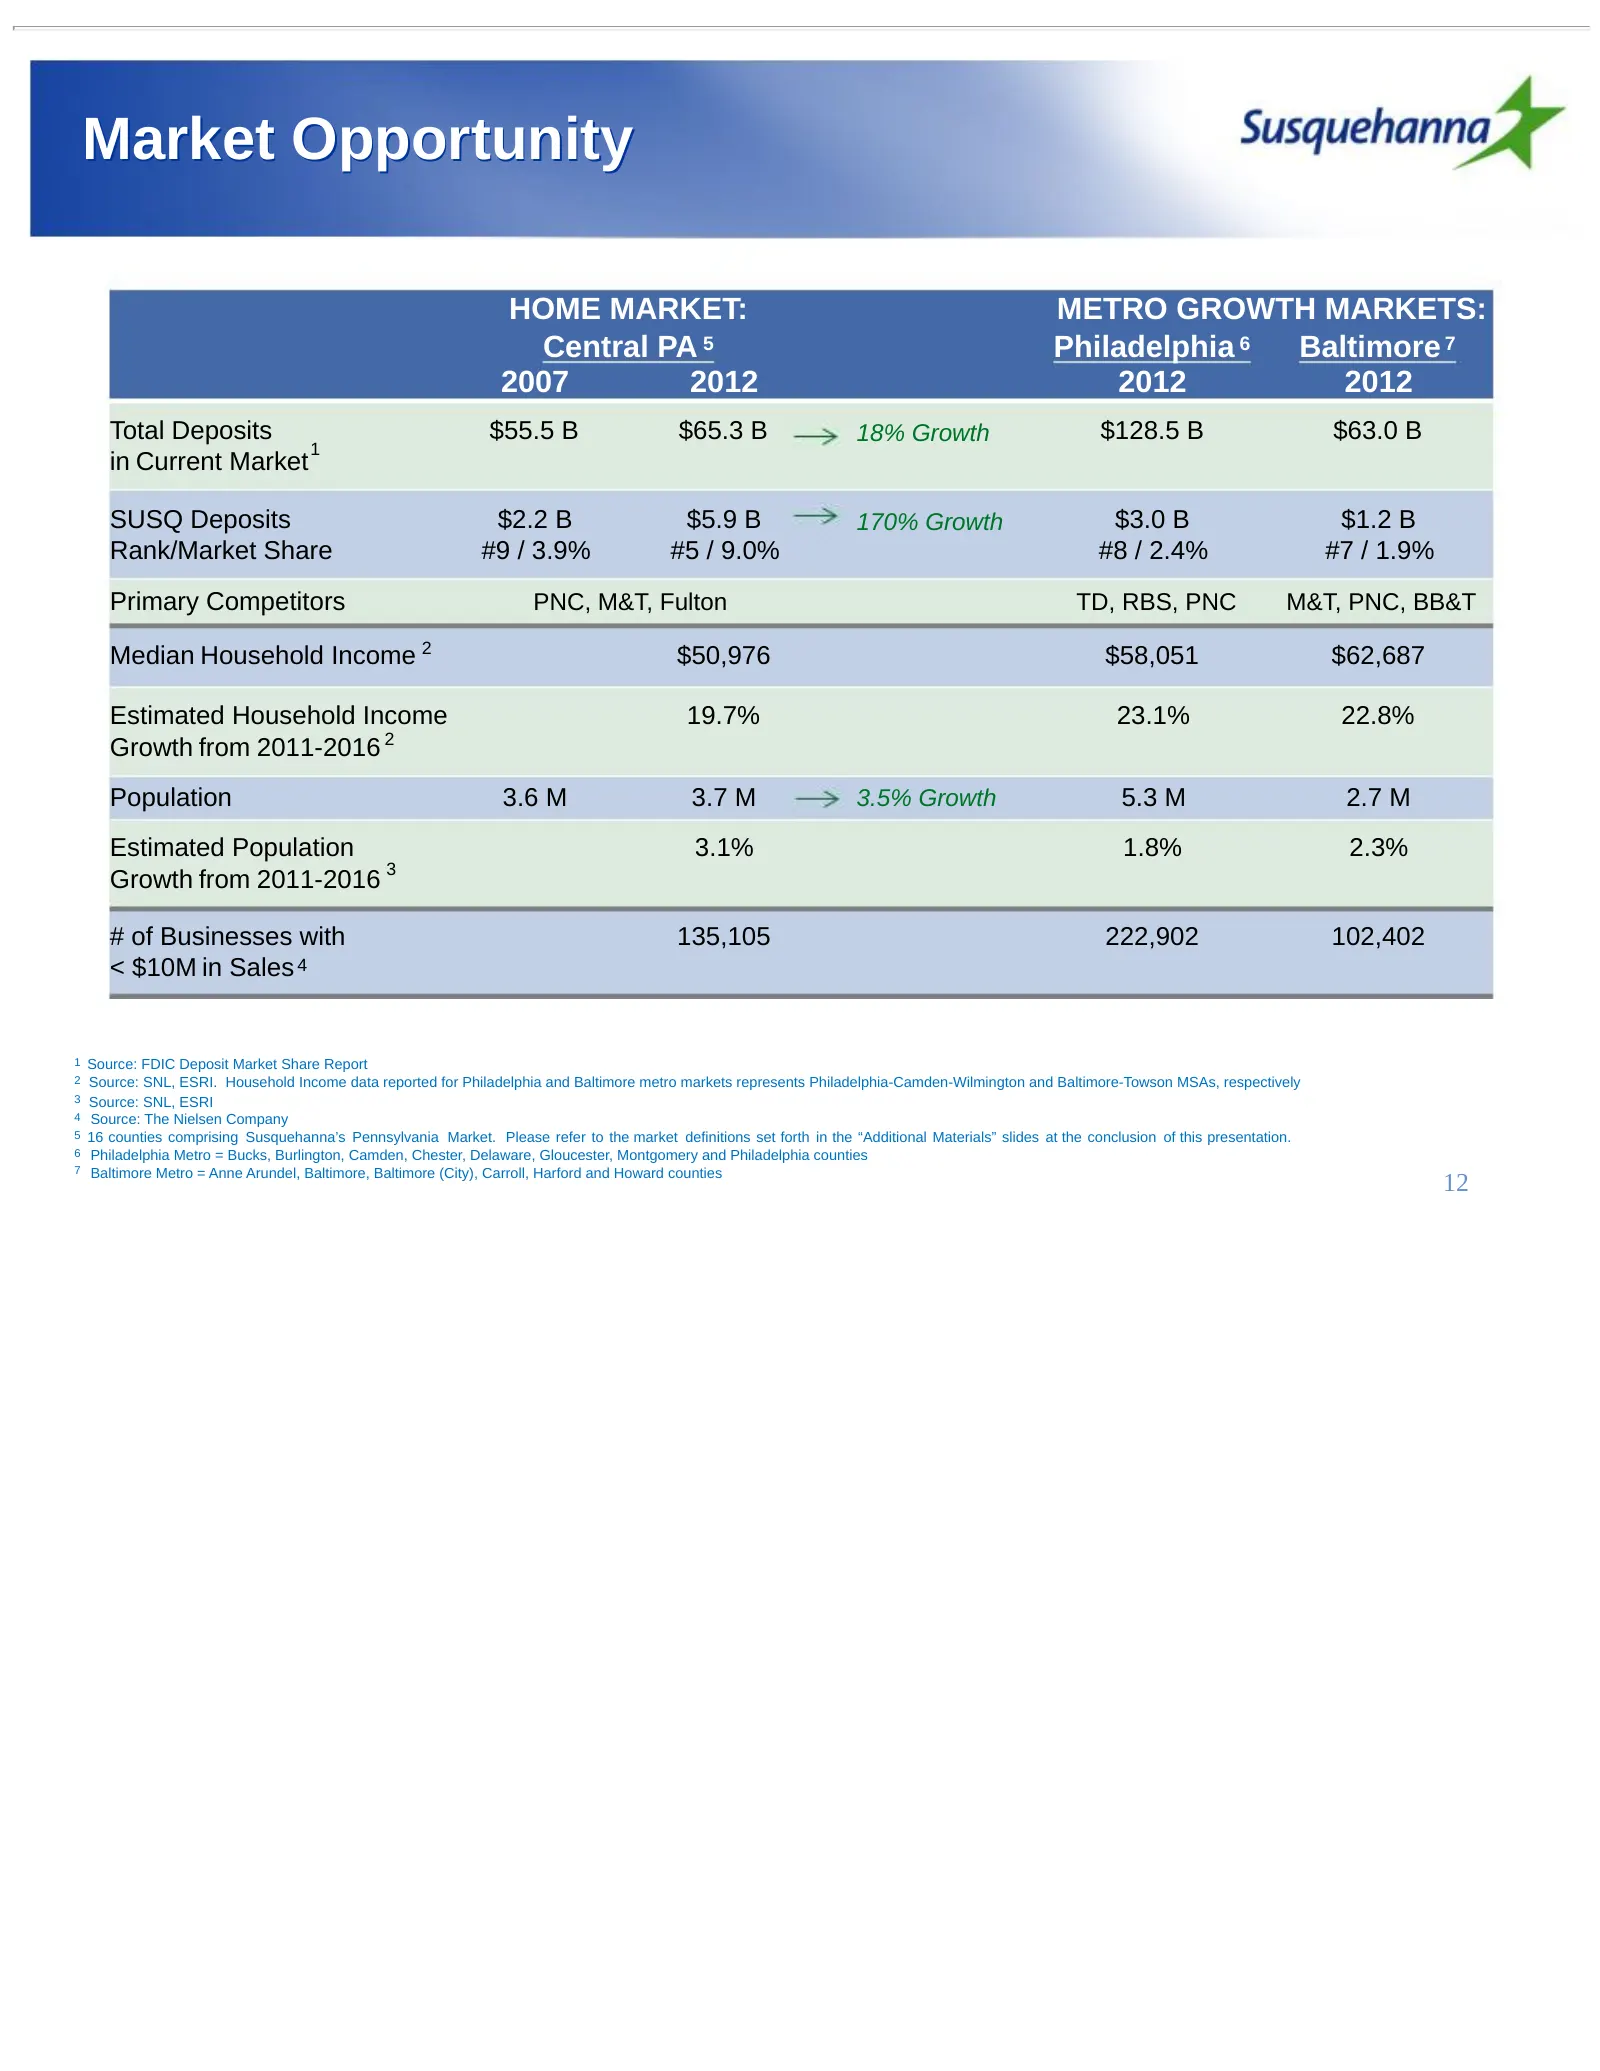
Market Opportunity HOME MARKET: METRO GROWTH MARKETS: Central PA 5 Philadelphia 6 Baltimore 7 2007 2012 2012 2012 Total Deposits $55.5 B $65.3 B 18% Growth $128.5 B $63.0 B 1 in Current Market SUSQ Deposits $2.2 B $5.9 B 170% Growth $3.0 B $1.2 B Rank/Market Share #9 / 3.9% #5 / 9.0% #8 / 2.4% #7 /
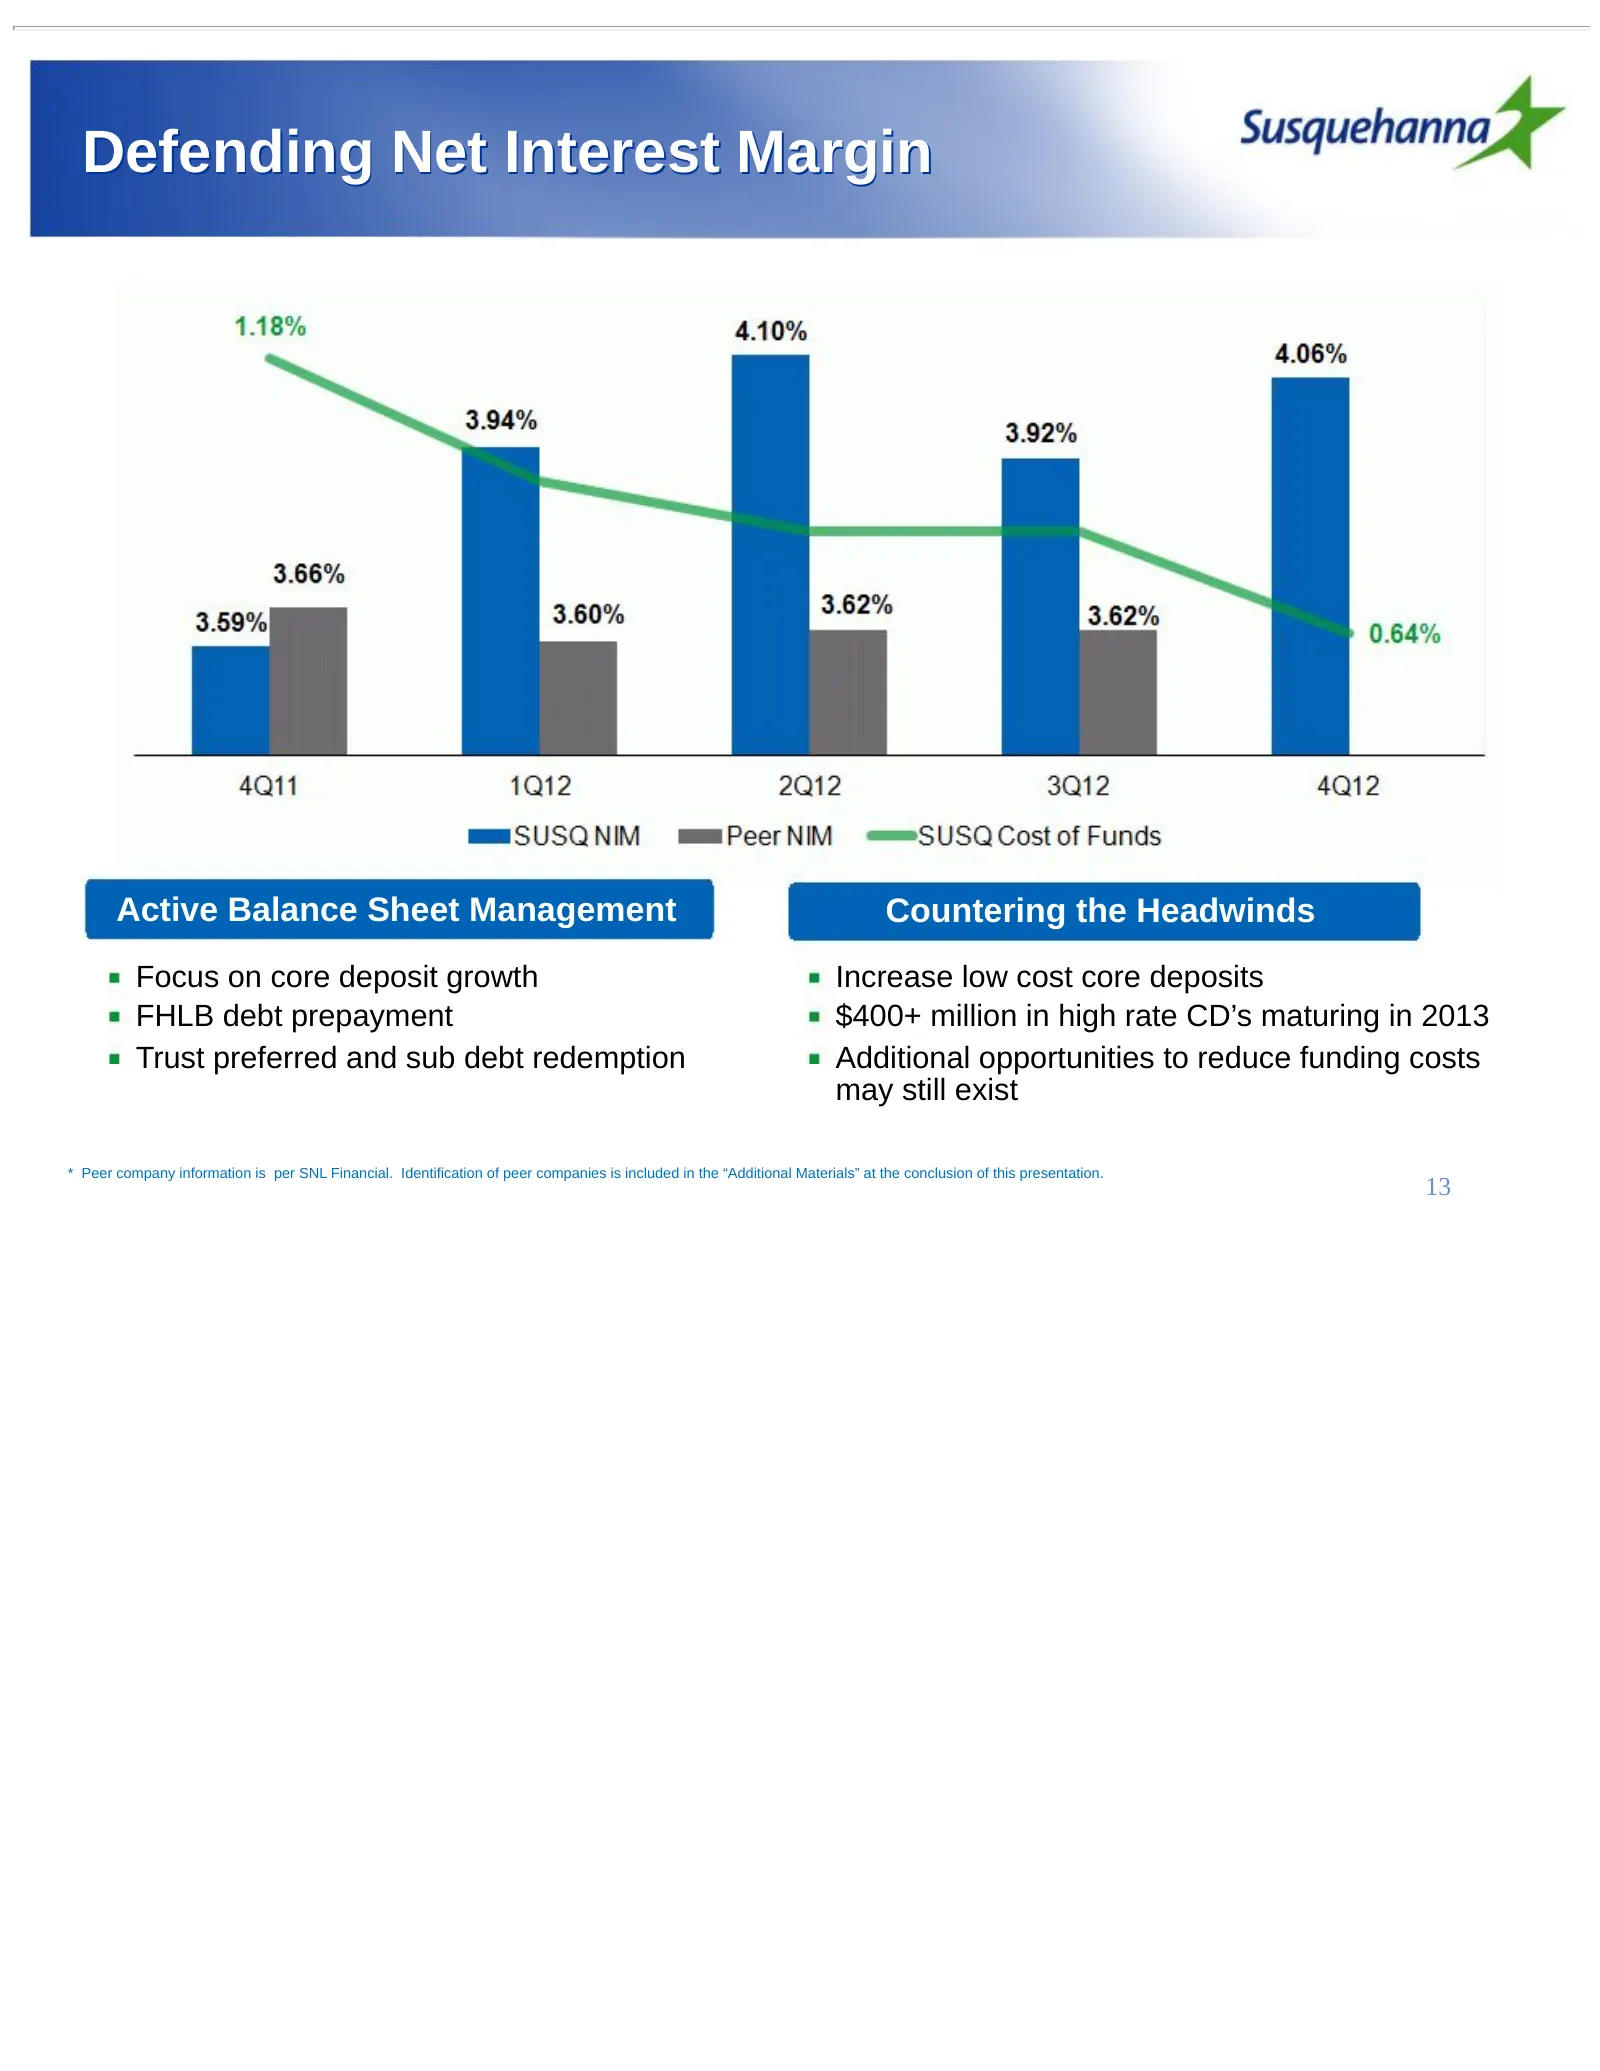
Slide 13: Defending Net Interest Margin
Defending Net Interest Margin Active Balance Sheet Management Countering the Headwinds Focus on core deposit growth Increase low cost core deposits FHLB debt prepayment $400+ million in high rate CD’s maturing in 2013 Trust preferred and sub debt redemption Additional opportunities to reduce funding
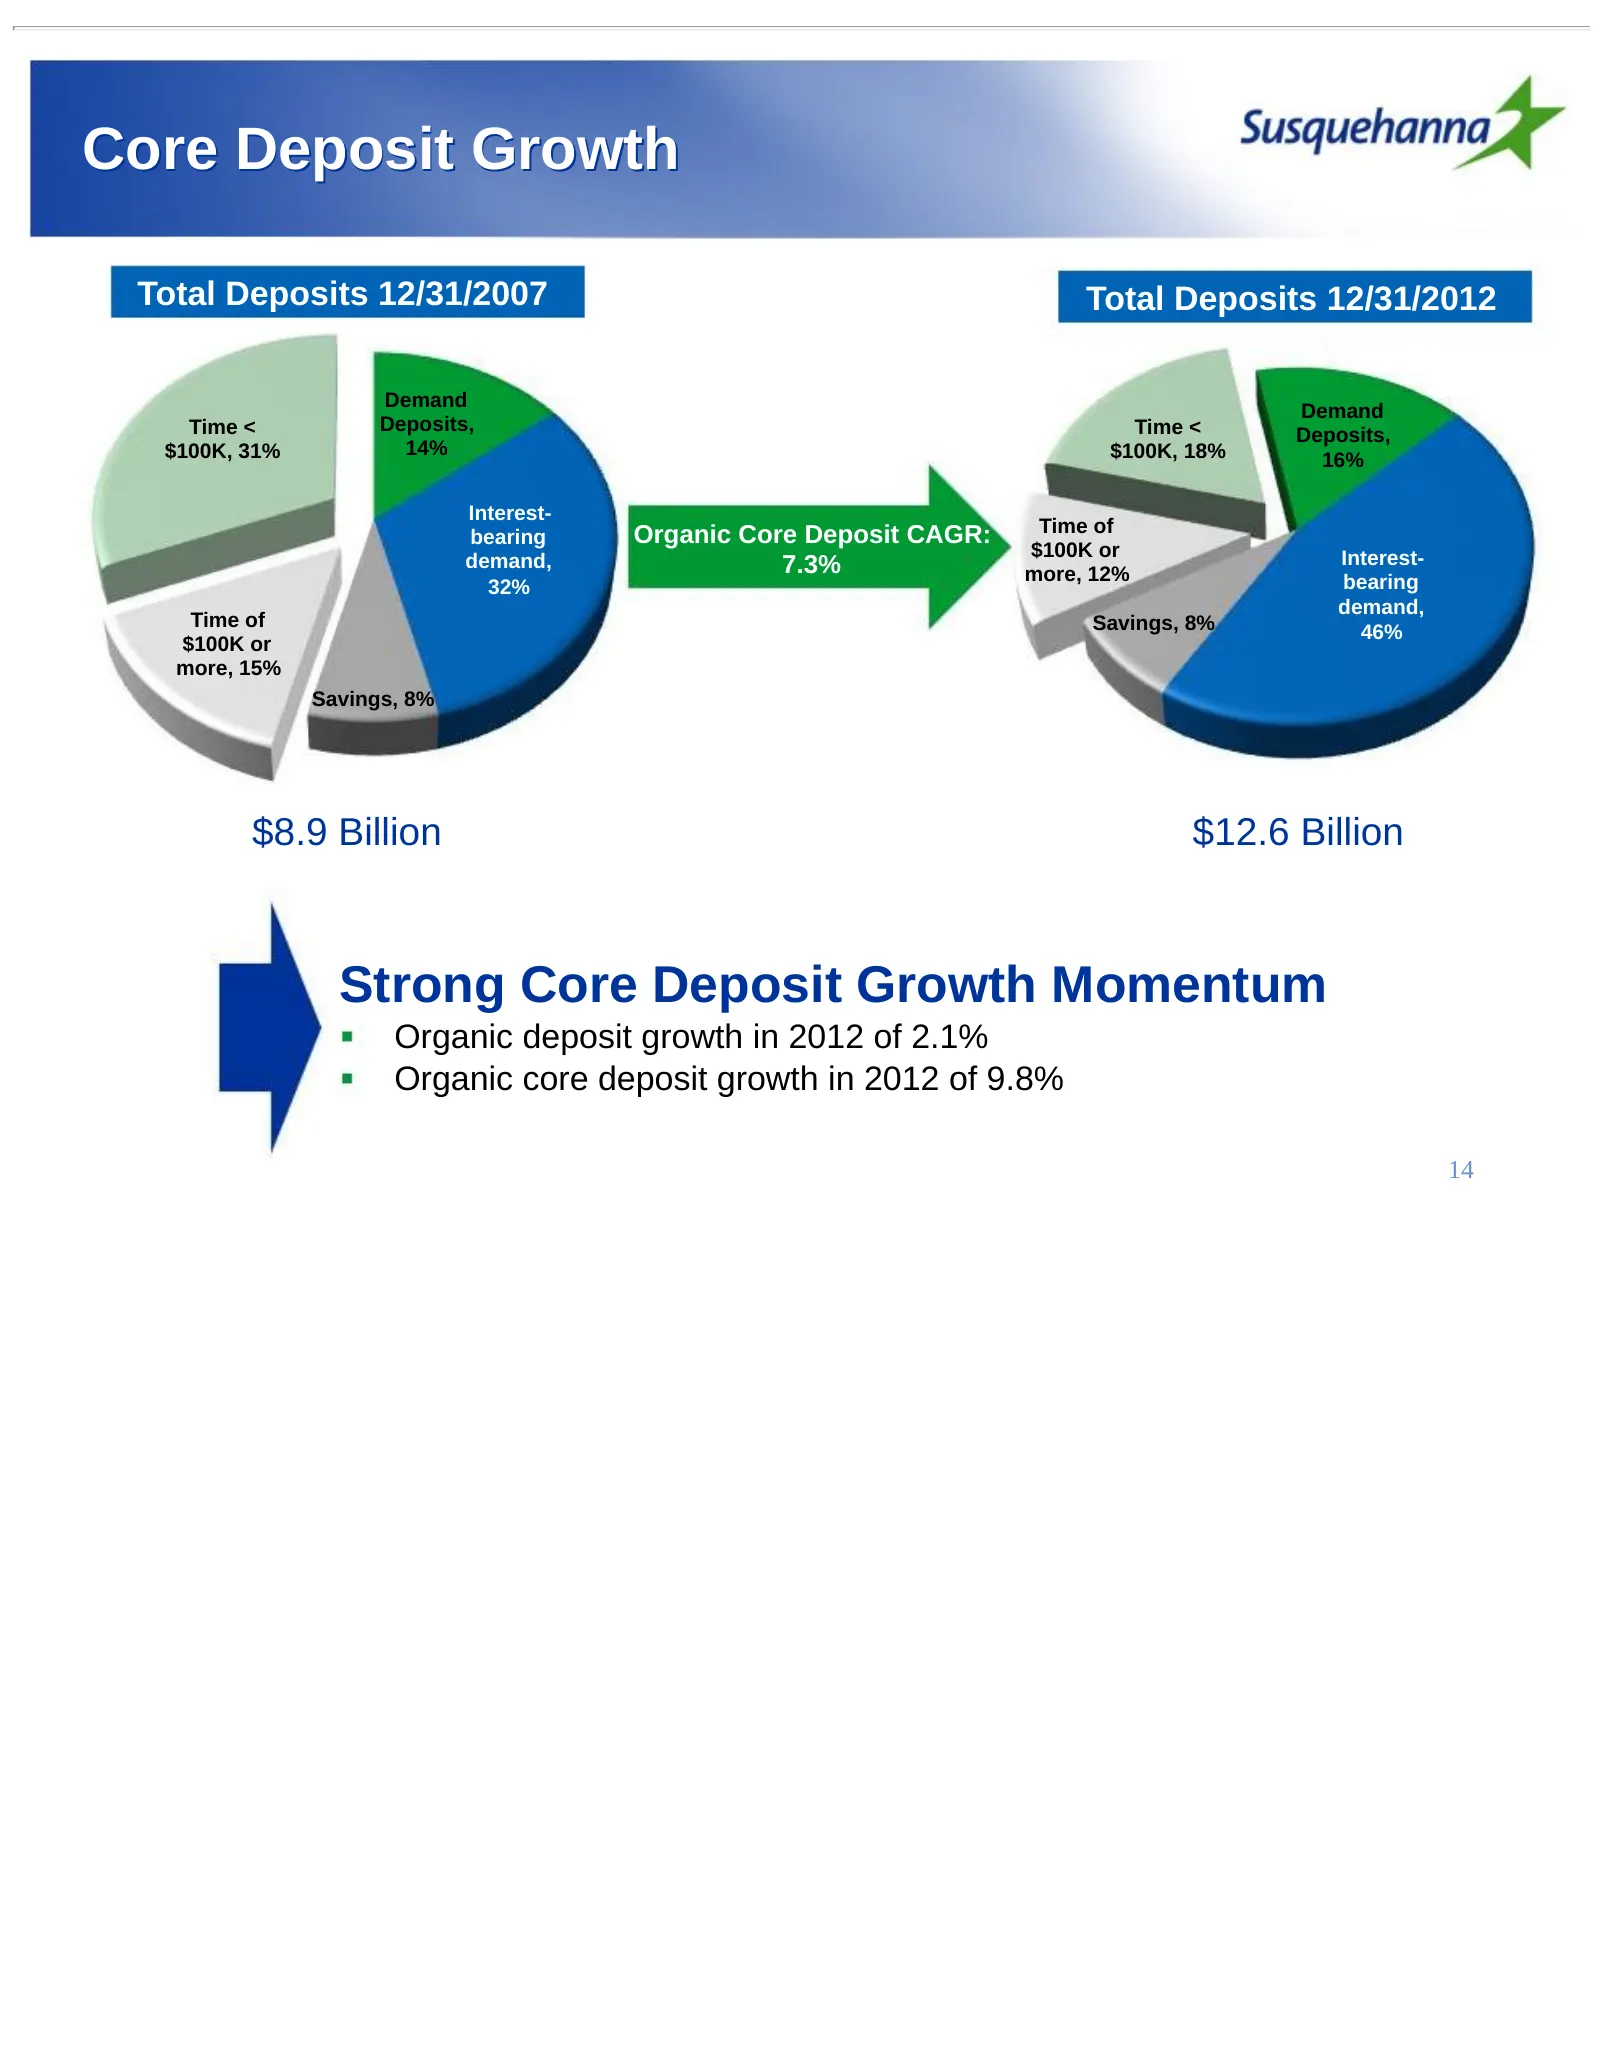
Slide 14: Core Deposit Growth
Core Deposit Growth Total Deposits 12/31/2007 Total Deposits 12/31/2012 Demand Demand Time < Deposits, Time < Deposits, $100K, 31% 14% $100K, 18% 16% Interest- Organic Core Deposit CAGR: Time of bearing $100K or Interest- demand, 7.3% more, 12% bearing 32% demand, Time of Savings, 8% 46% $100K or mo
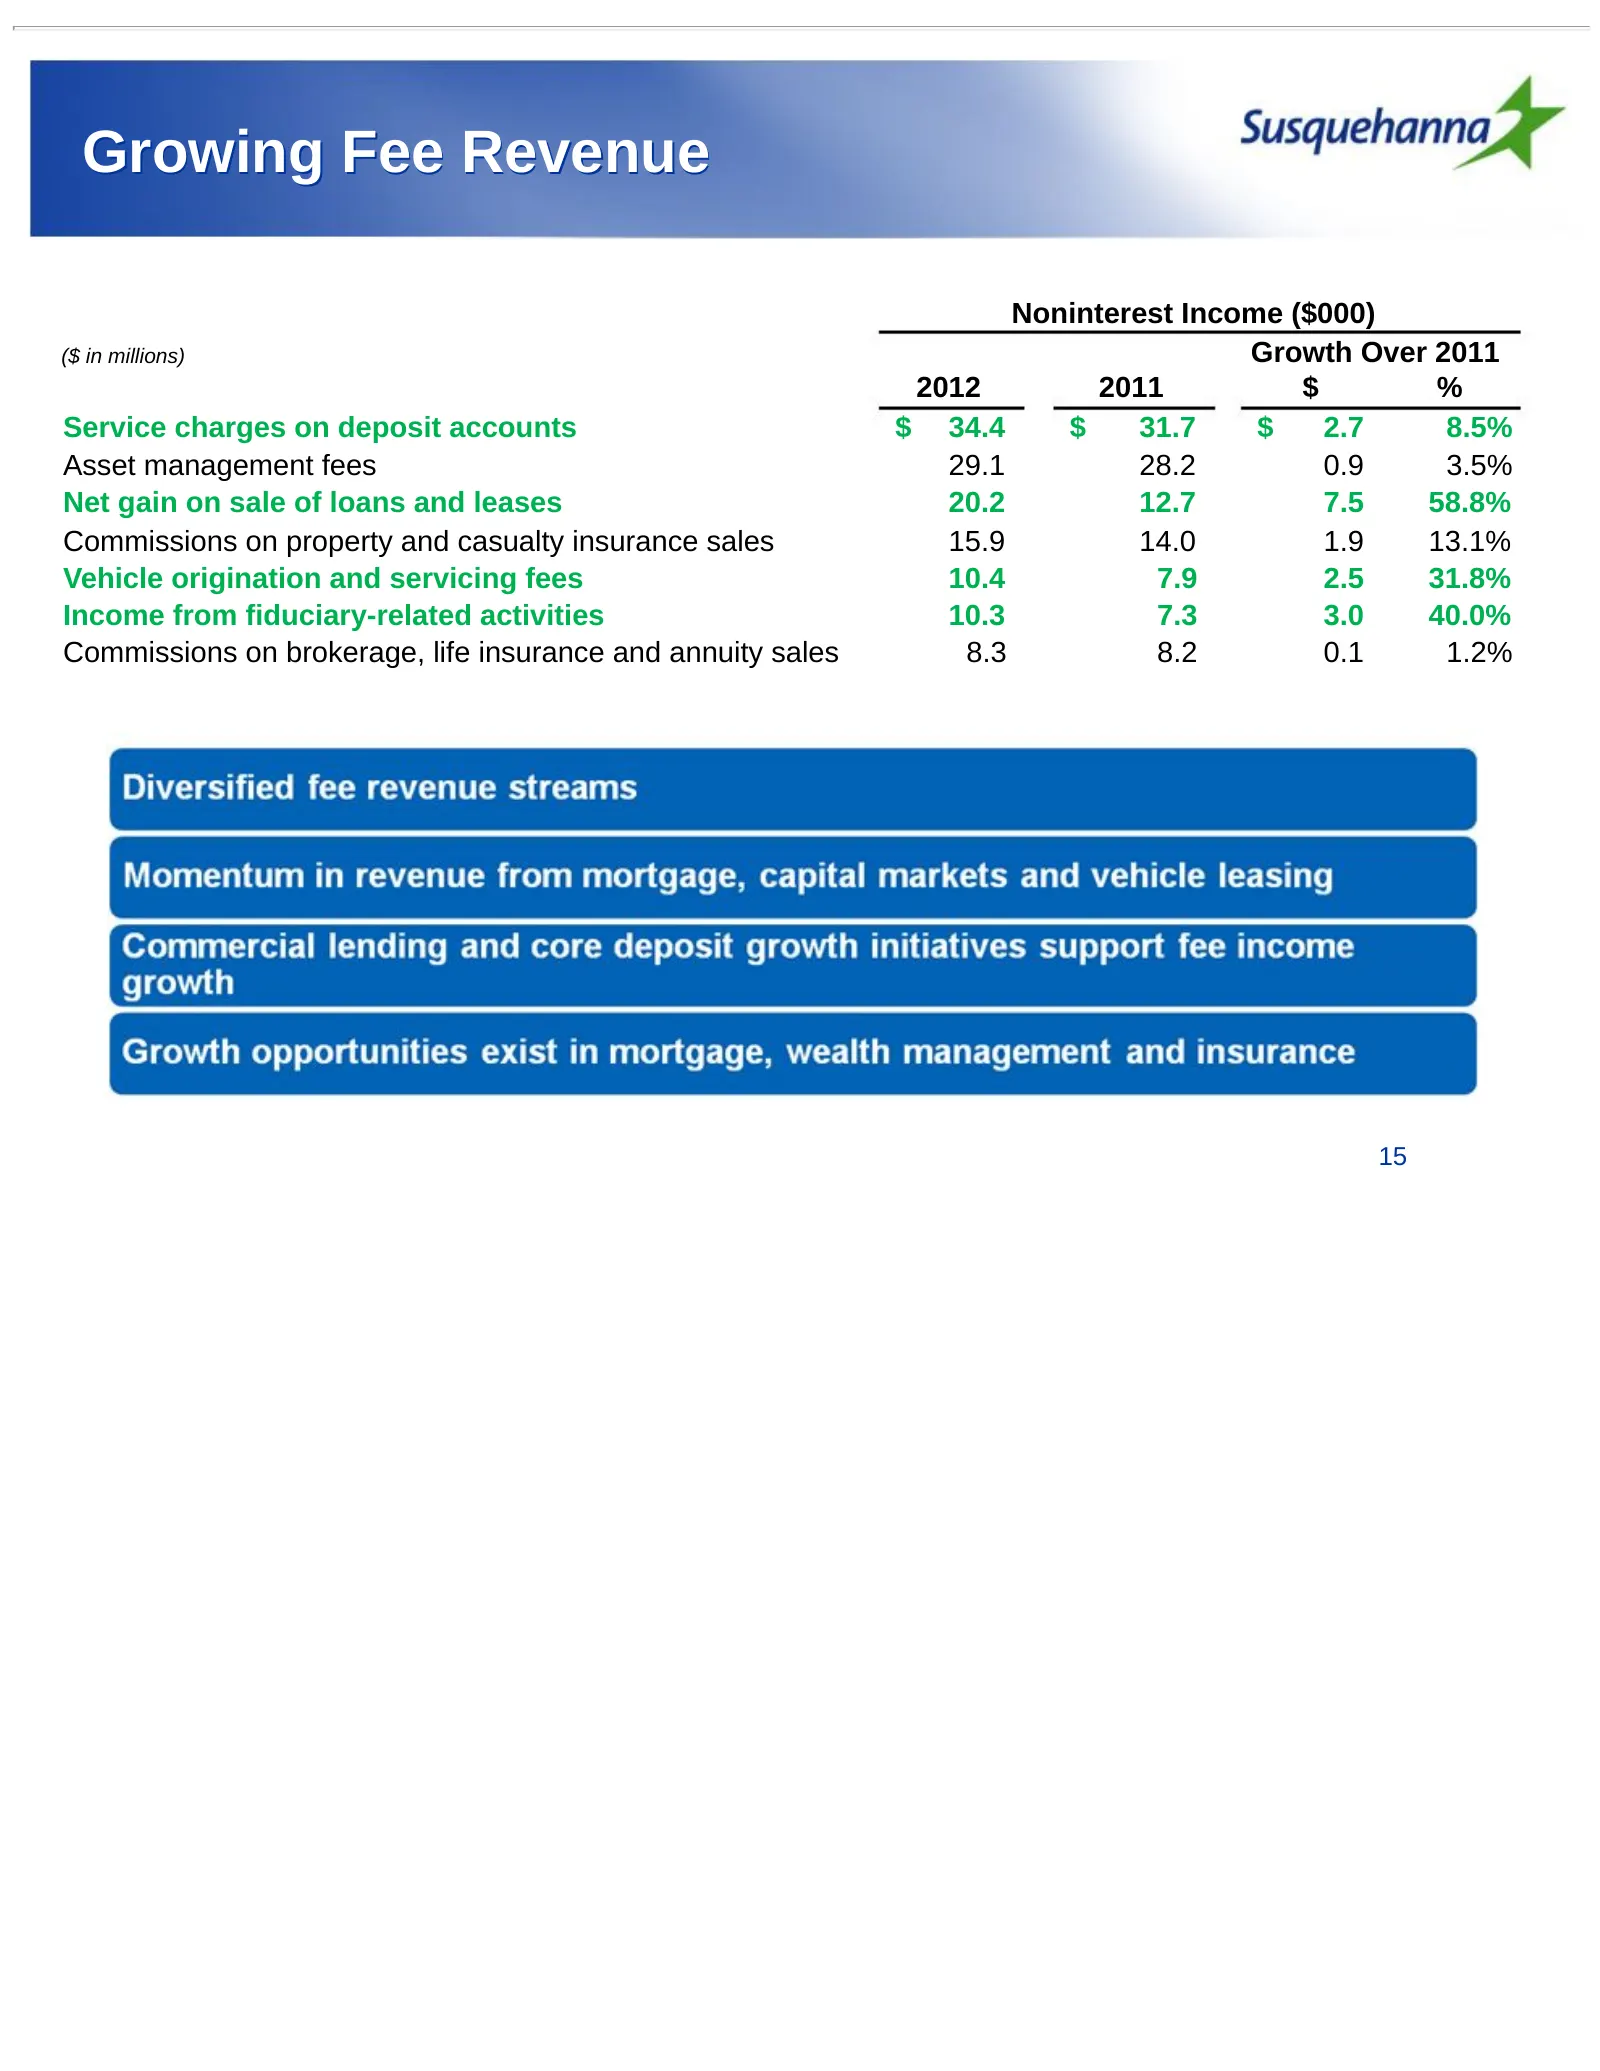
Slide 15: Growing Fee Revenue
Growing Fee Revenue Noninterest Income ($000) ($ in millions) Growth Over 2011 2012 2011 $ % Service charges on deposit accounts $ 34.4 $ 31.7 $ 2.7 8.5% Asset management fees 29.1 28.2 0.9 3.5% Net gain on sale of loans and leases 20.2 12.7 7.5 58.8% Commissions on property and casualty insurance s
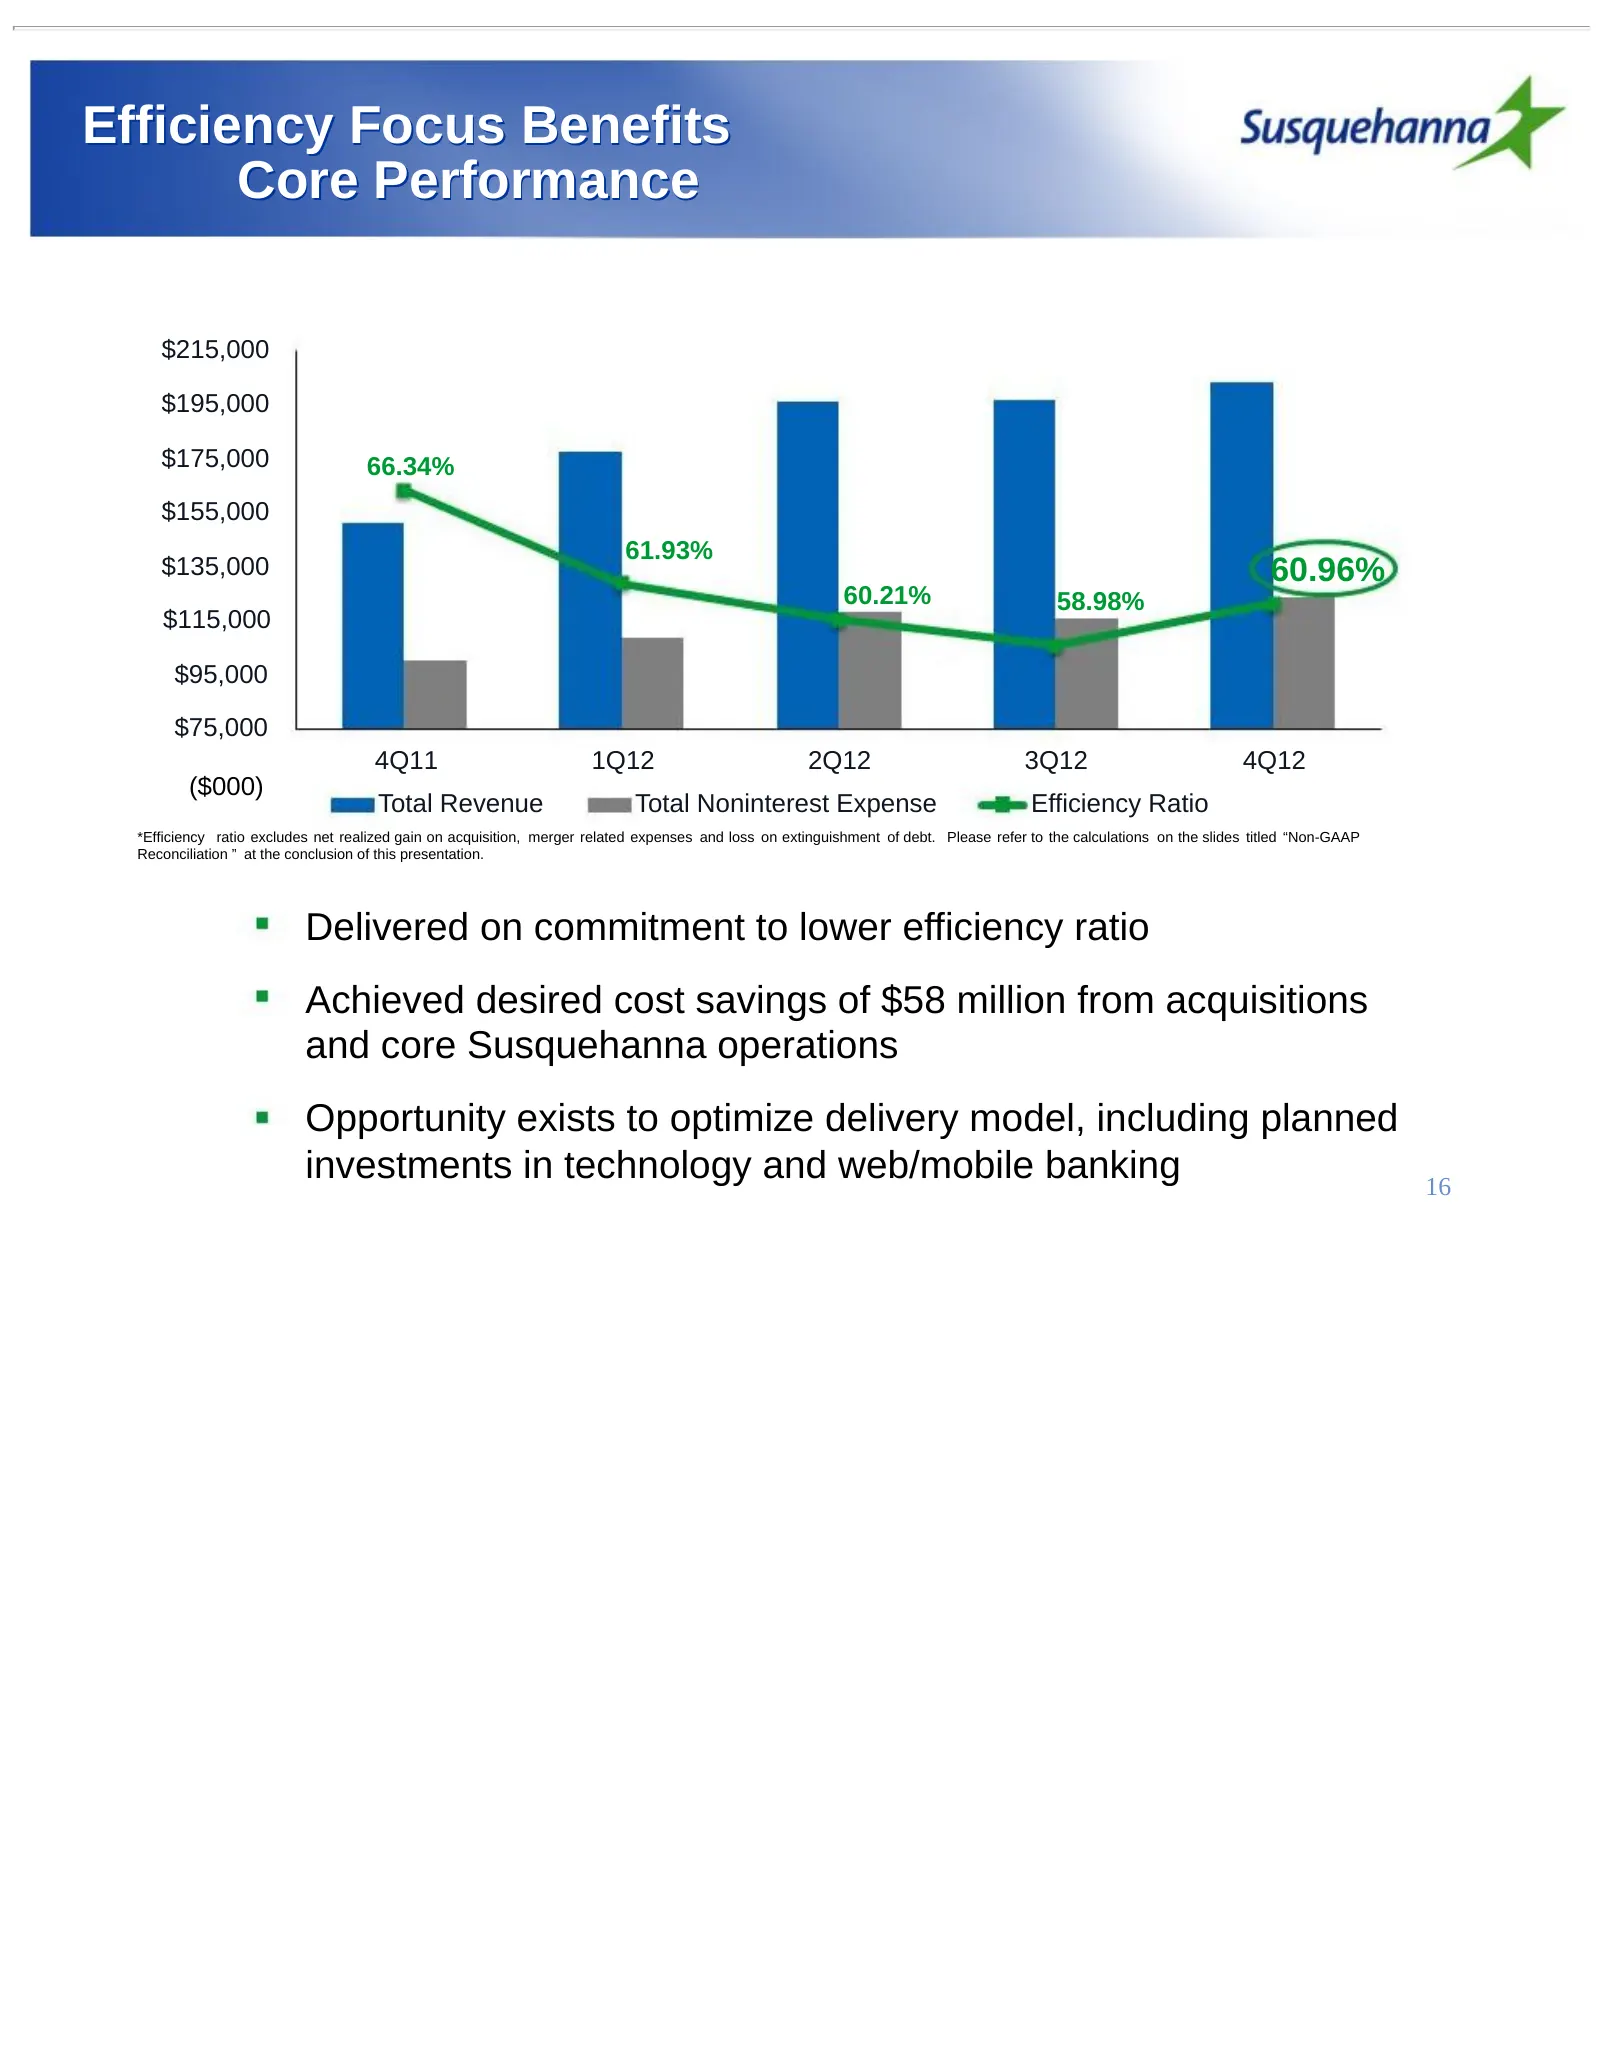
Slide 16: Efficiency Focus Benefits Core Performance
Efficiency Focus Benefits Core Performance $215,000 $195,000 $175,000 66.34% $155,000 61.93% $135,000 60.96% 60.21% 58.98% $115,000 $95,000 $75,000 4Q11 1Q12 2Q12 3Q12 4Q12 ($000) Total Revenue Total Noninterest Expense Efficiency Ratio *Efficiency ratio excludes net realized gain on acquisition, me
Slide 17: Capital Generation and Returns
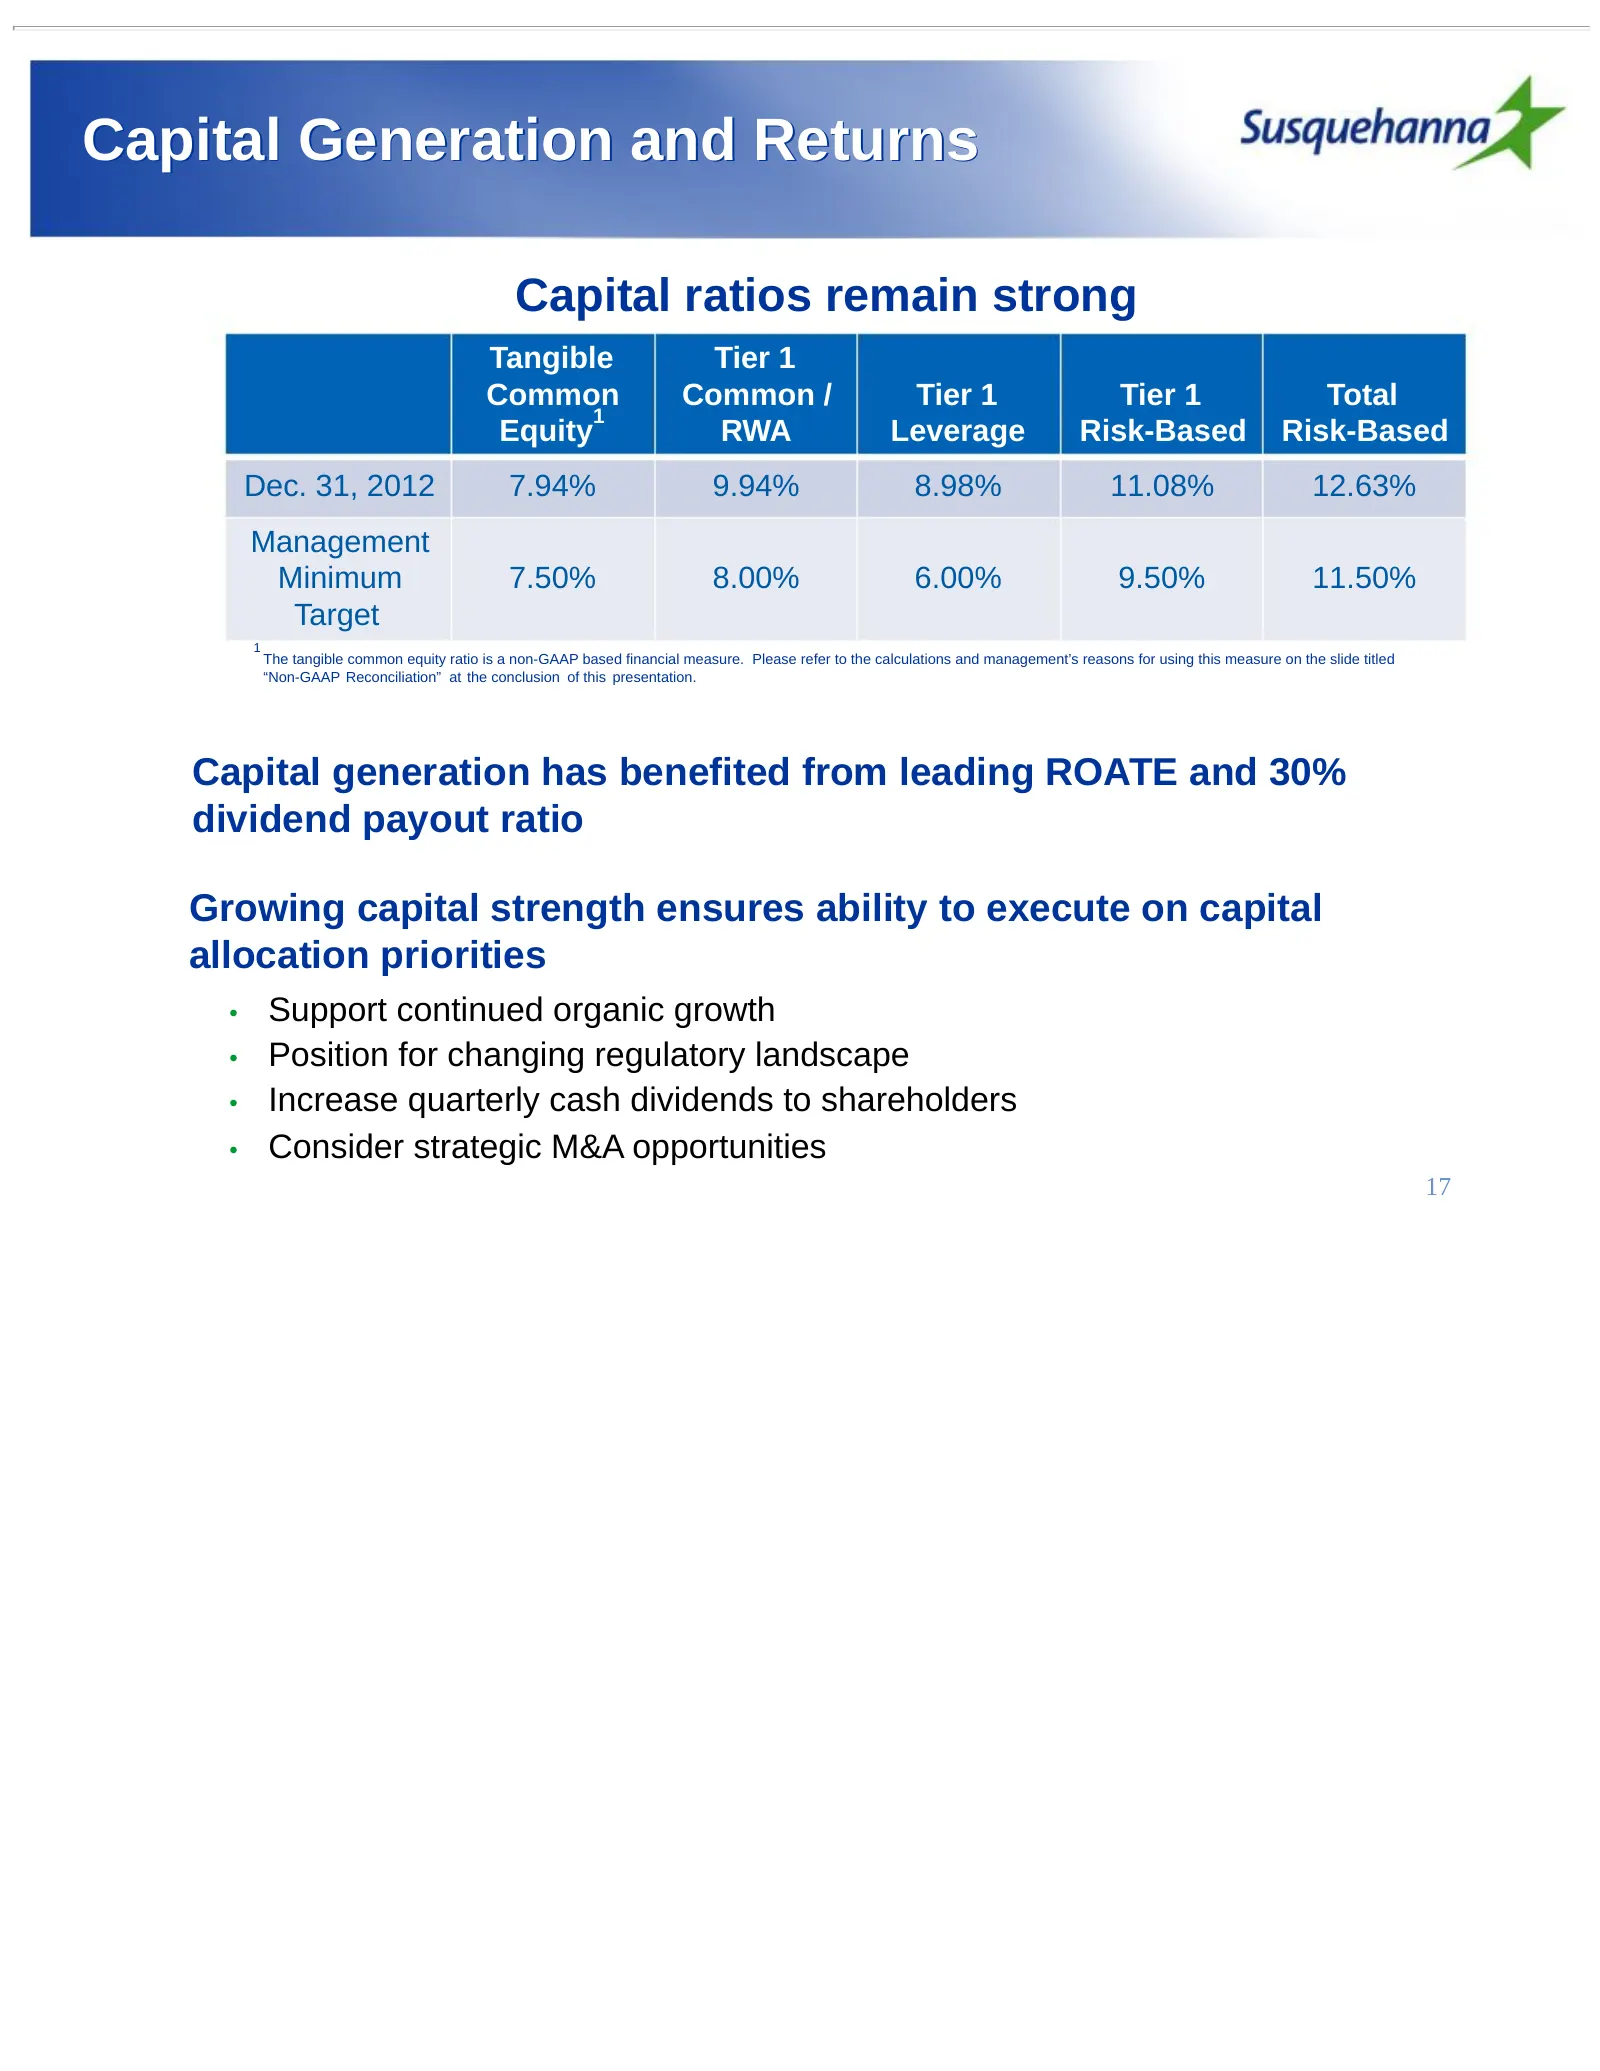
Capital Generation and Returns Capital ratios remain strong Tangible Tier 1 Common Common / Tier 1 Tier 1 Total 1 Equity RWA Leverage Risk-Based Risk-Based Dec. 31, 2012 7.94% 9.94% 8.98% 11.08% 12.63% Management Minimum 7.50% 8.00% 6.00% 9.50% 11.50% Target 1 The tangible common equity ratio is a n
Slide 18: Earnings Power Drives Returns
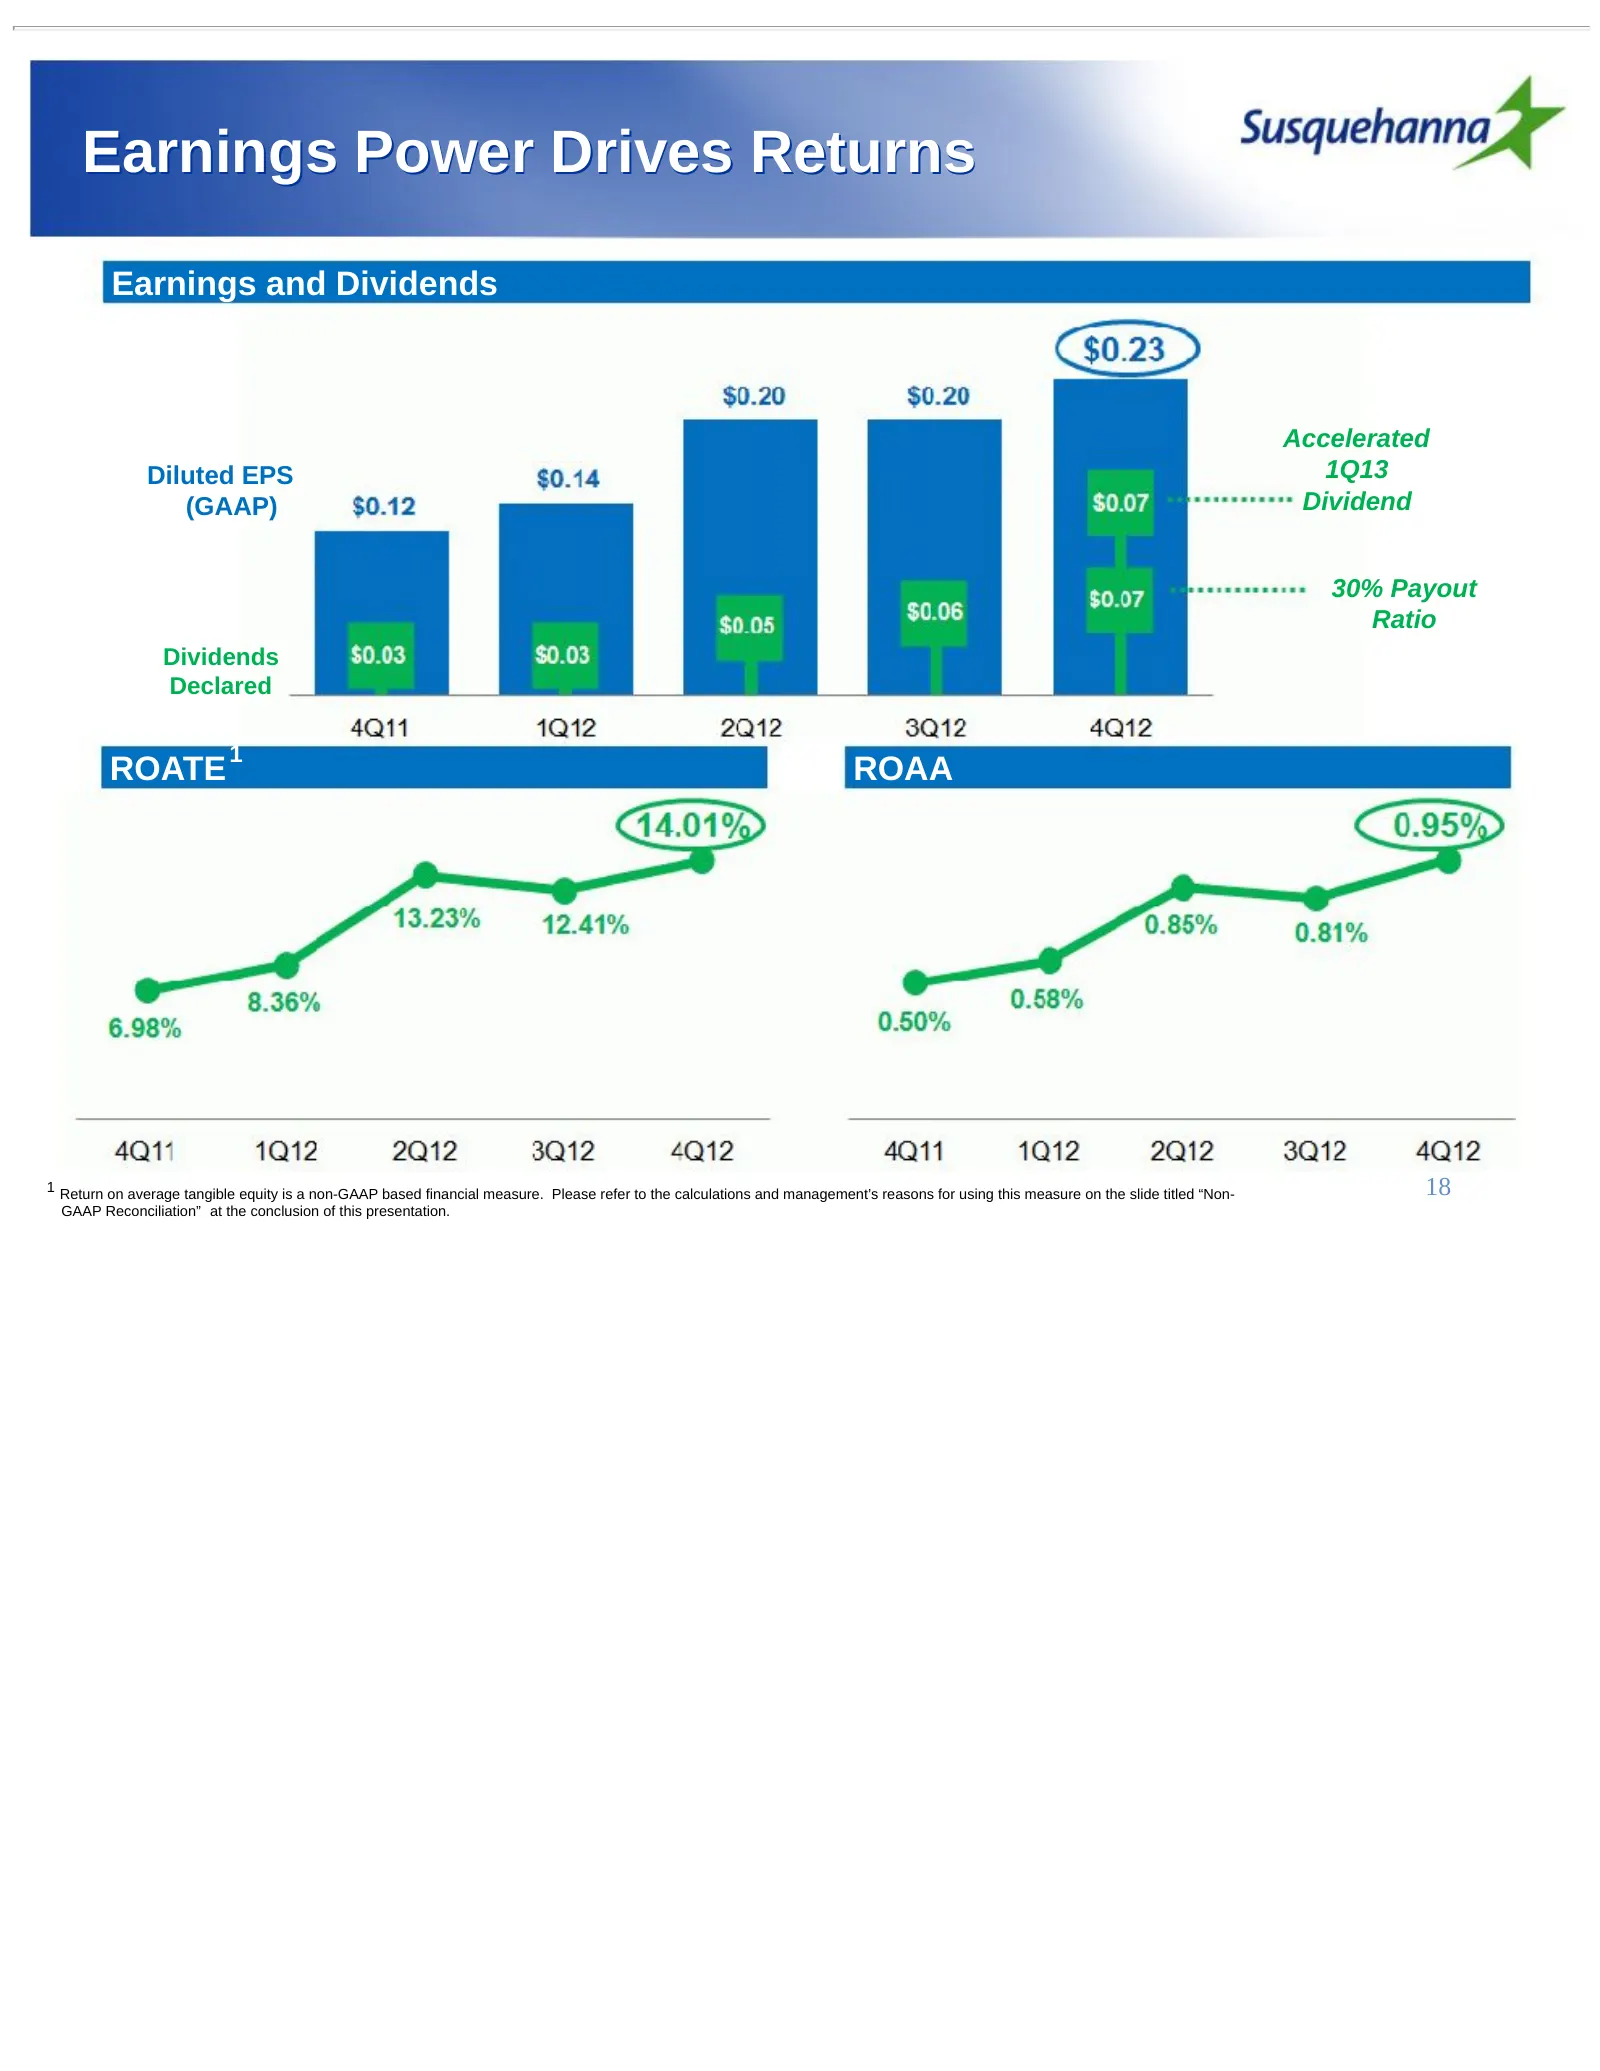
Earnings Power Drives Returns Earnings and Dividends Accelerated Diluted EPS 1Q13 (GAAP) Dividend 30% Payout Ratio Dividends Declared 1 ROATE ROAA 1 Return on average tangible equity is a non-GAAP based financial measure. Please refer to the calculations and management’s reasons for using this measu
Slide 19: Building on Momentum
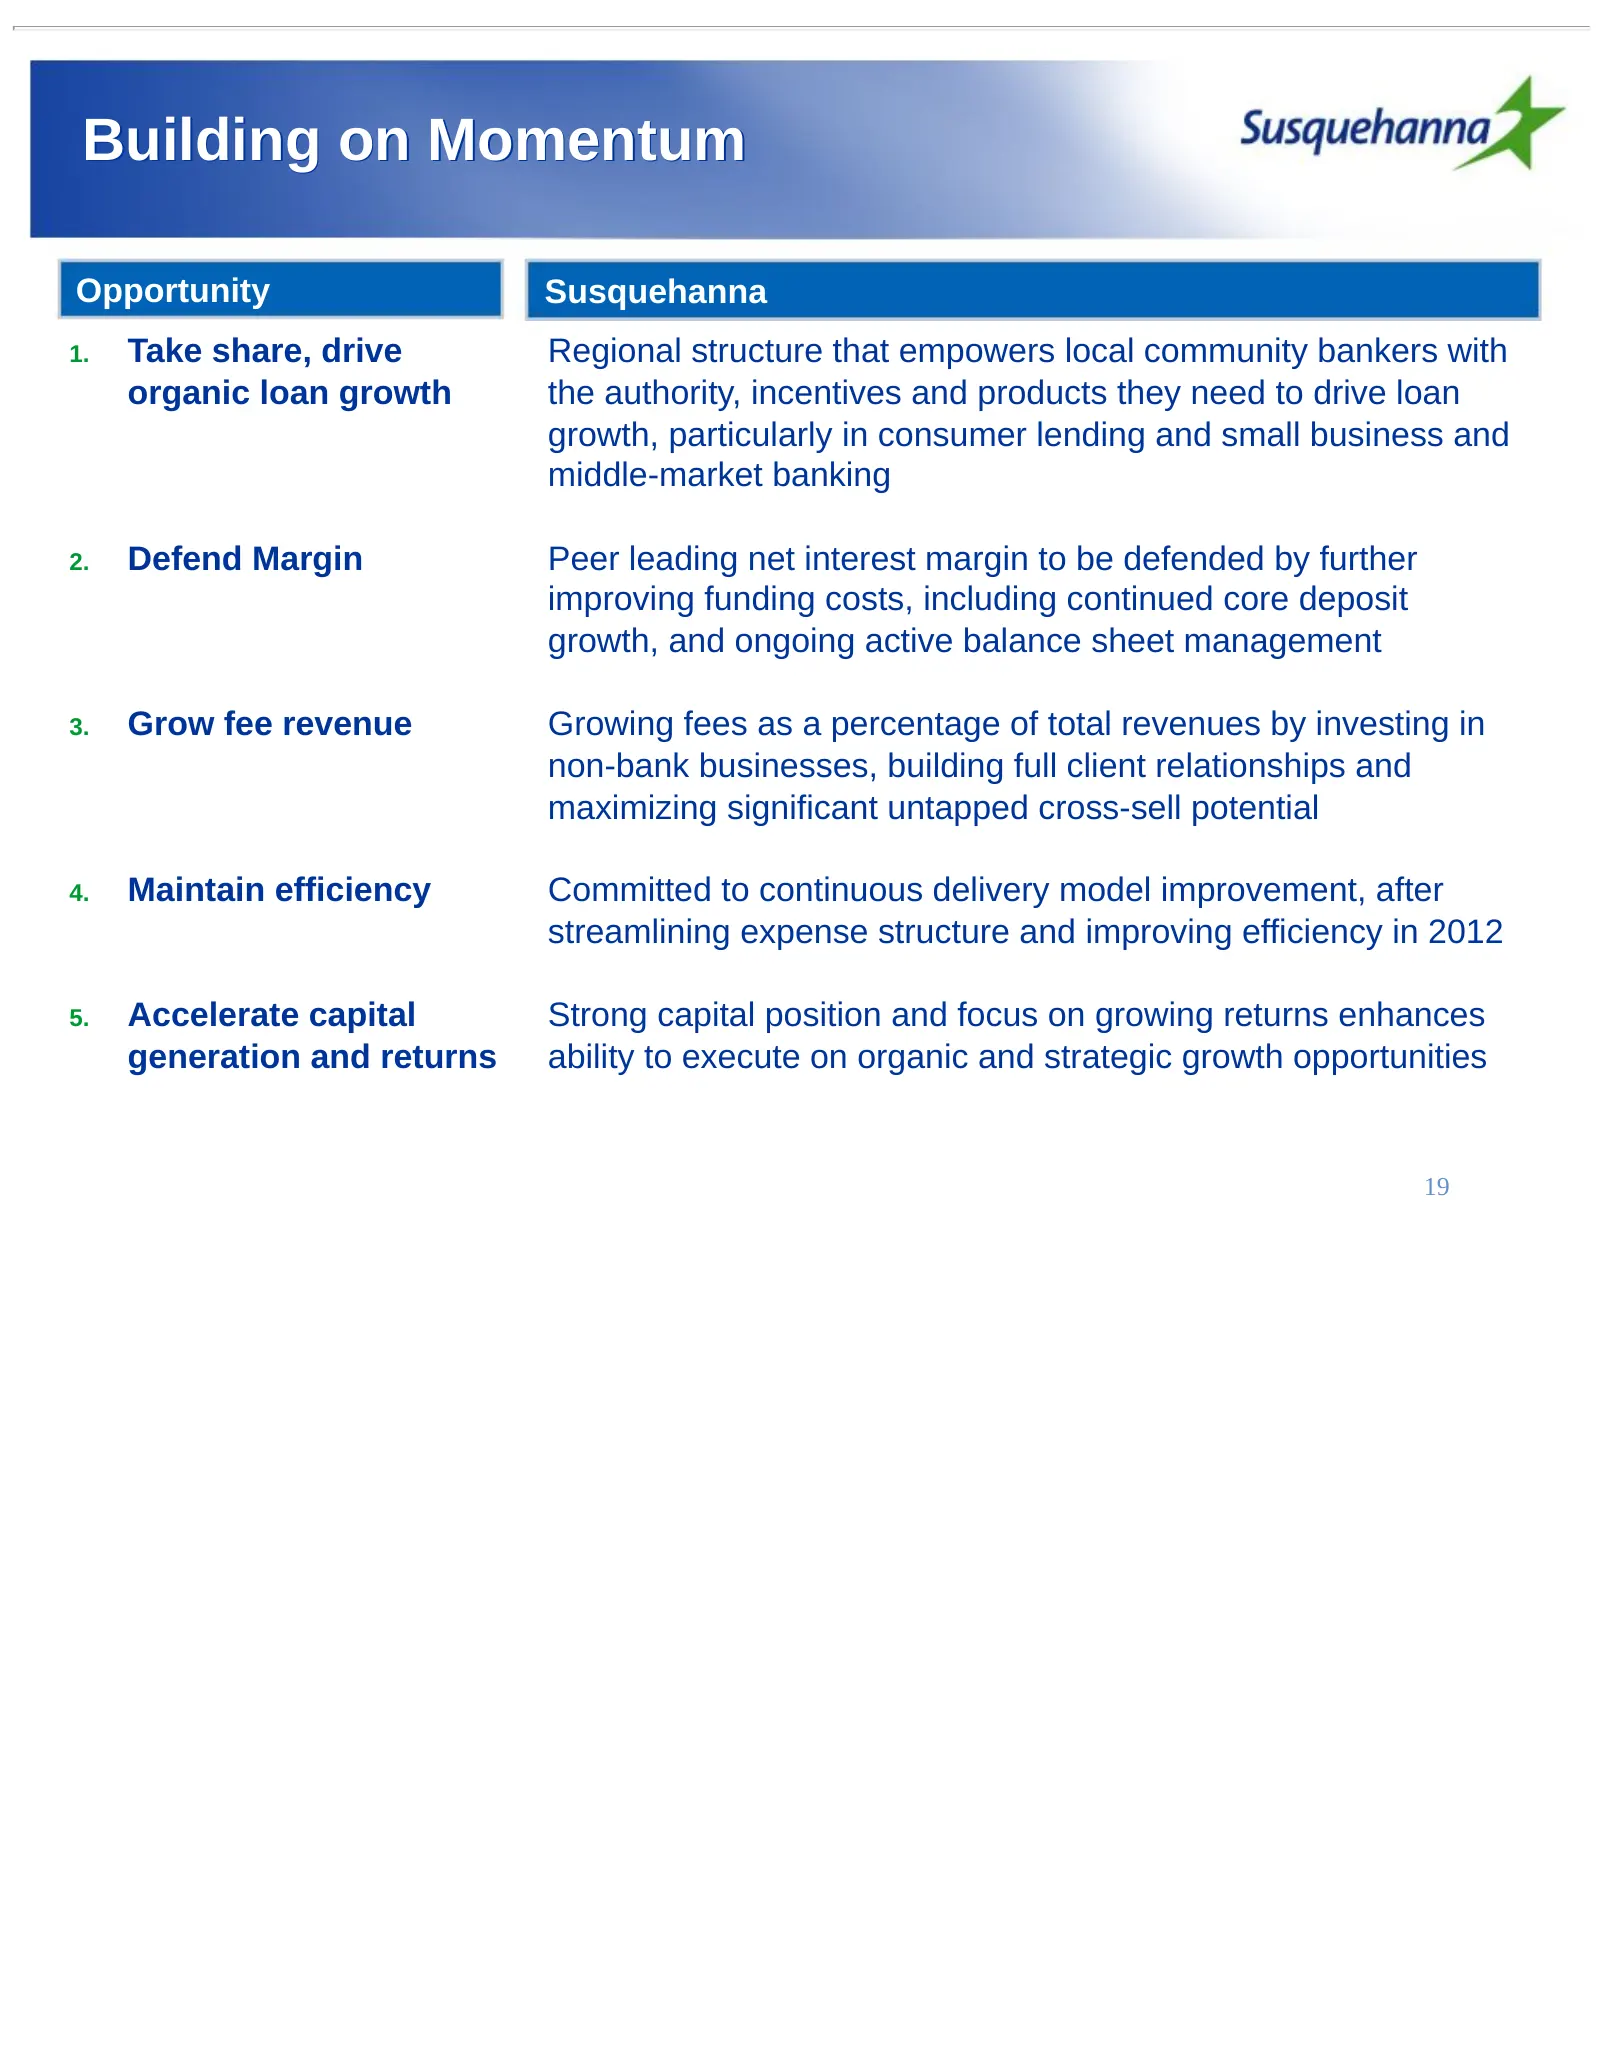
Building on Momentum Opportunity Susquehanna 1. Take share, drive Regional structure that empowers local community bankers with organic loan growth the authority, incentives and products they need to drive loan growth, particularly in consumer lending and small business and middle-market banking 2.
Slide 20: Additional Materials
Additional Materials
Slide 21: Executive Leadership Team
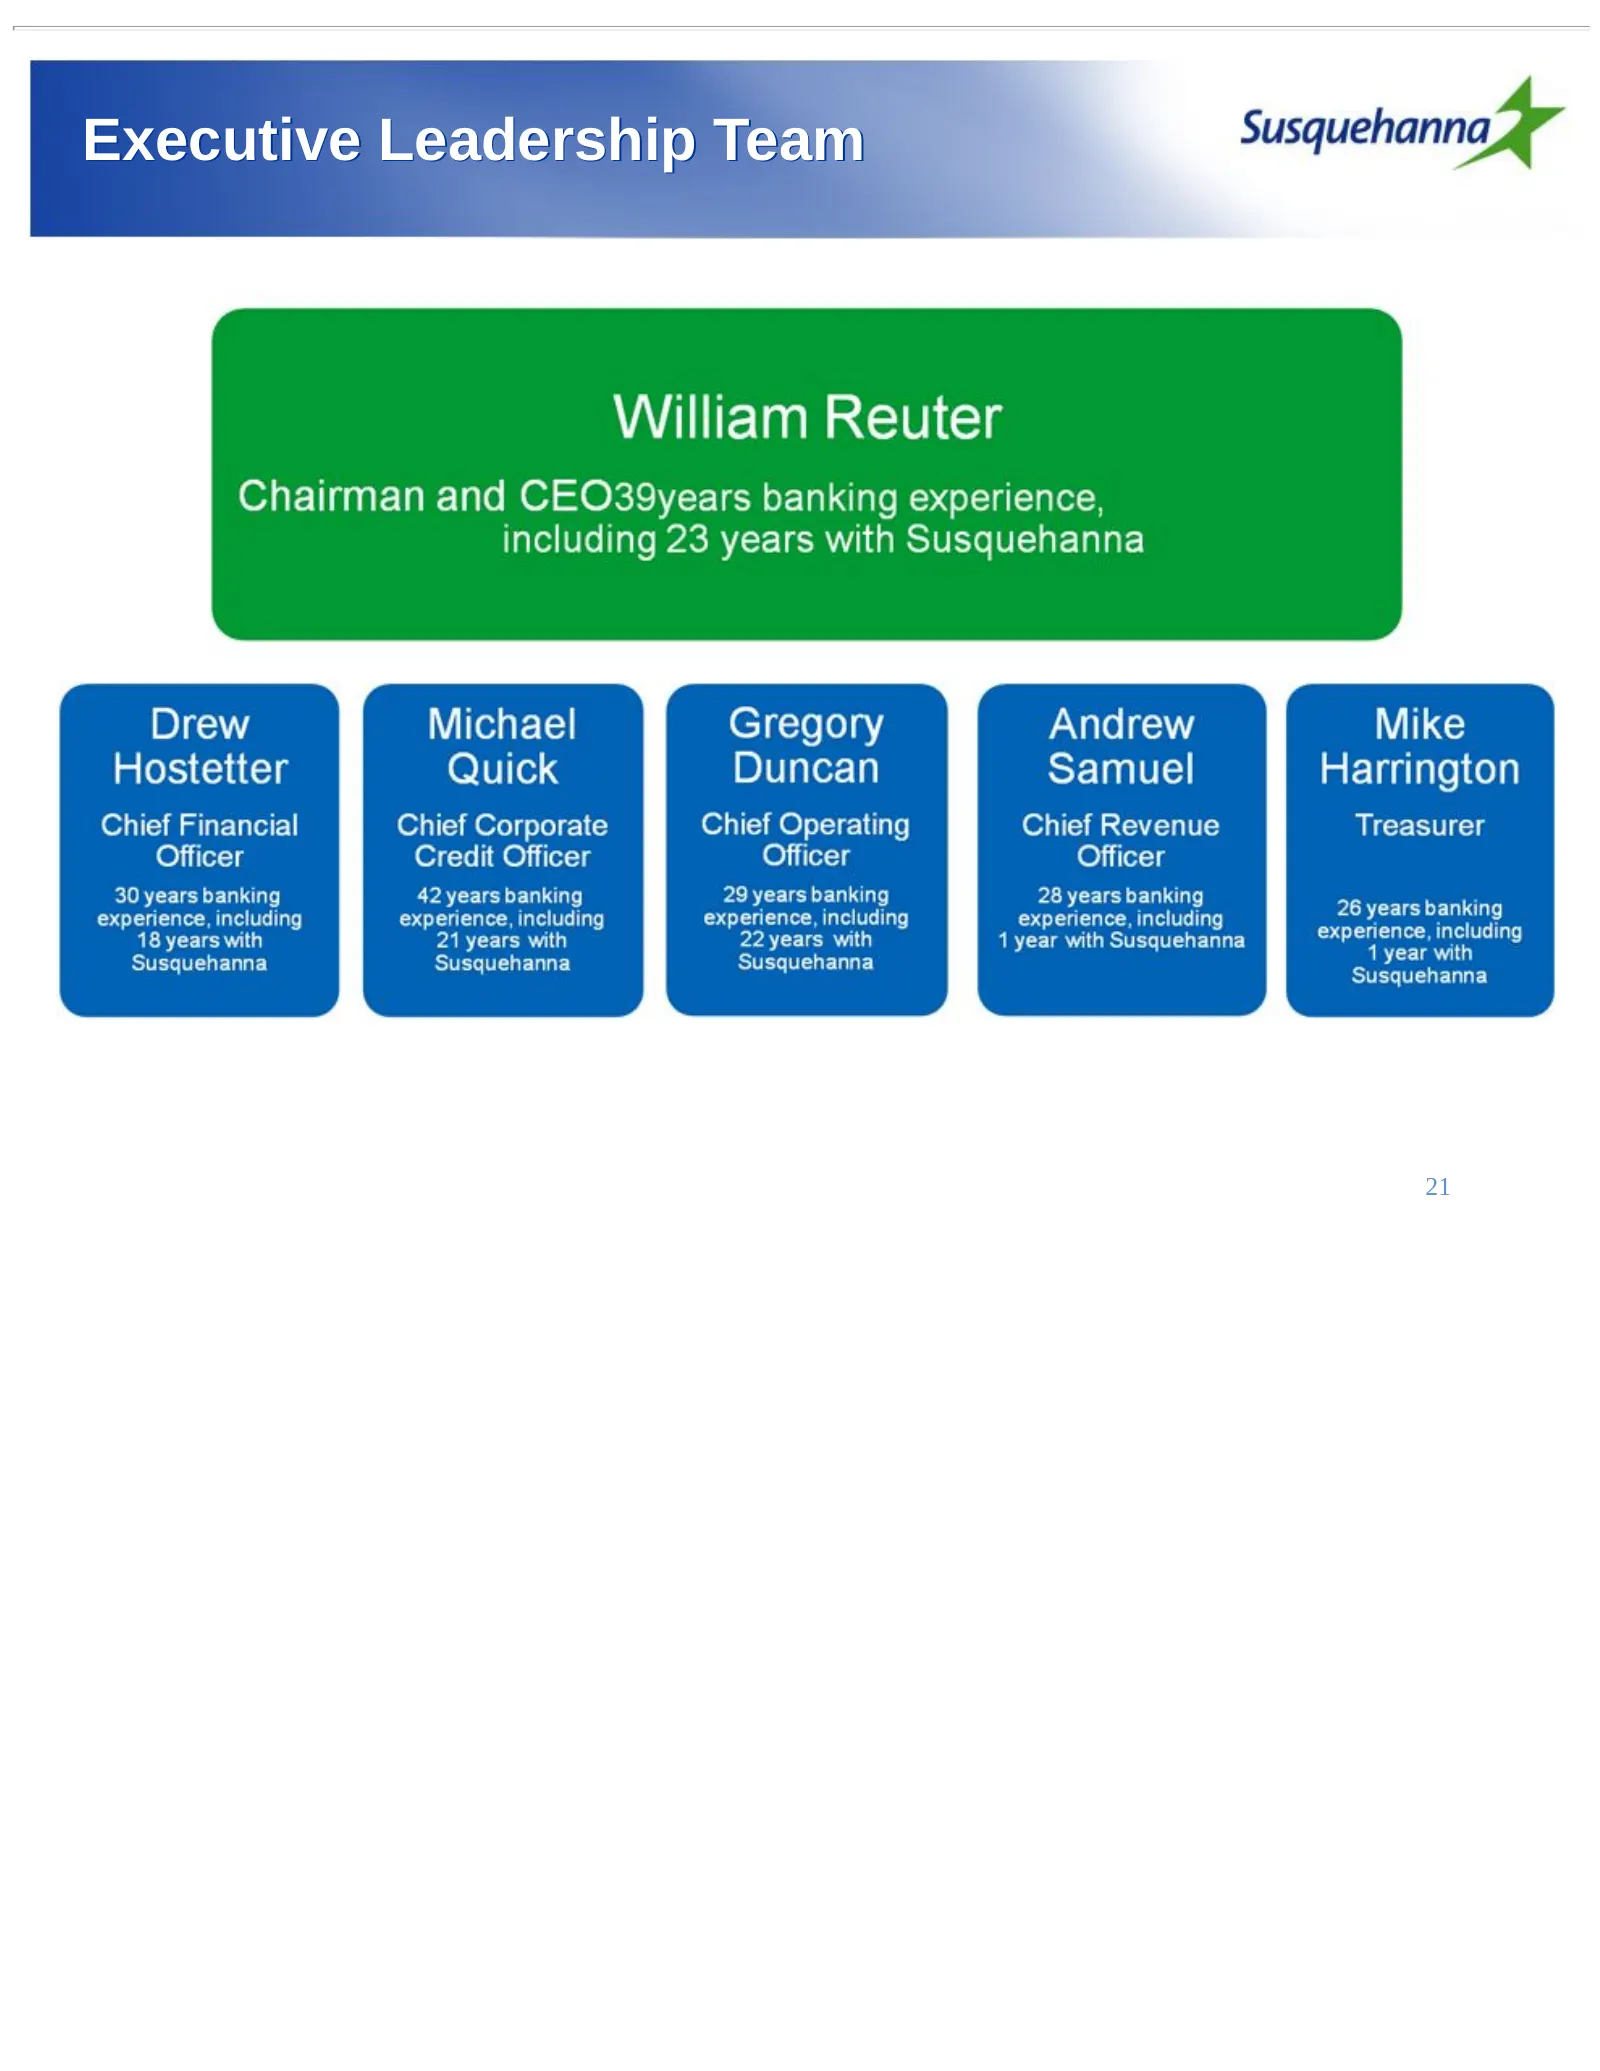
Executive Leadership Team 21
Slide 22: Critical Mass in Attractive Markets
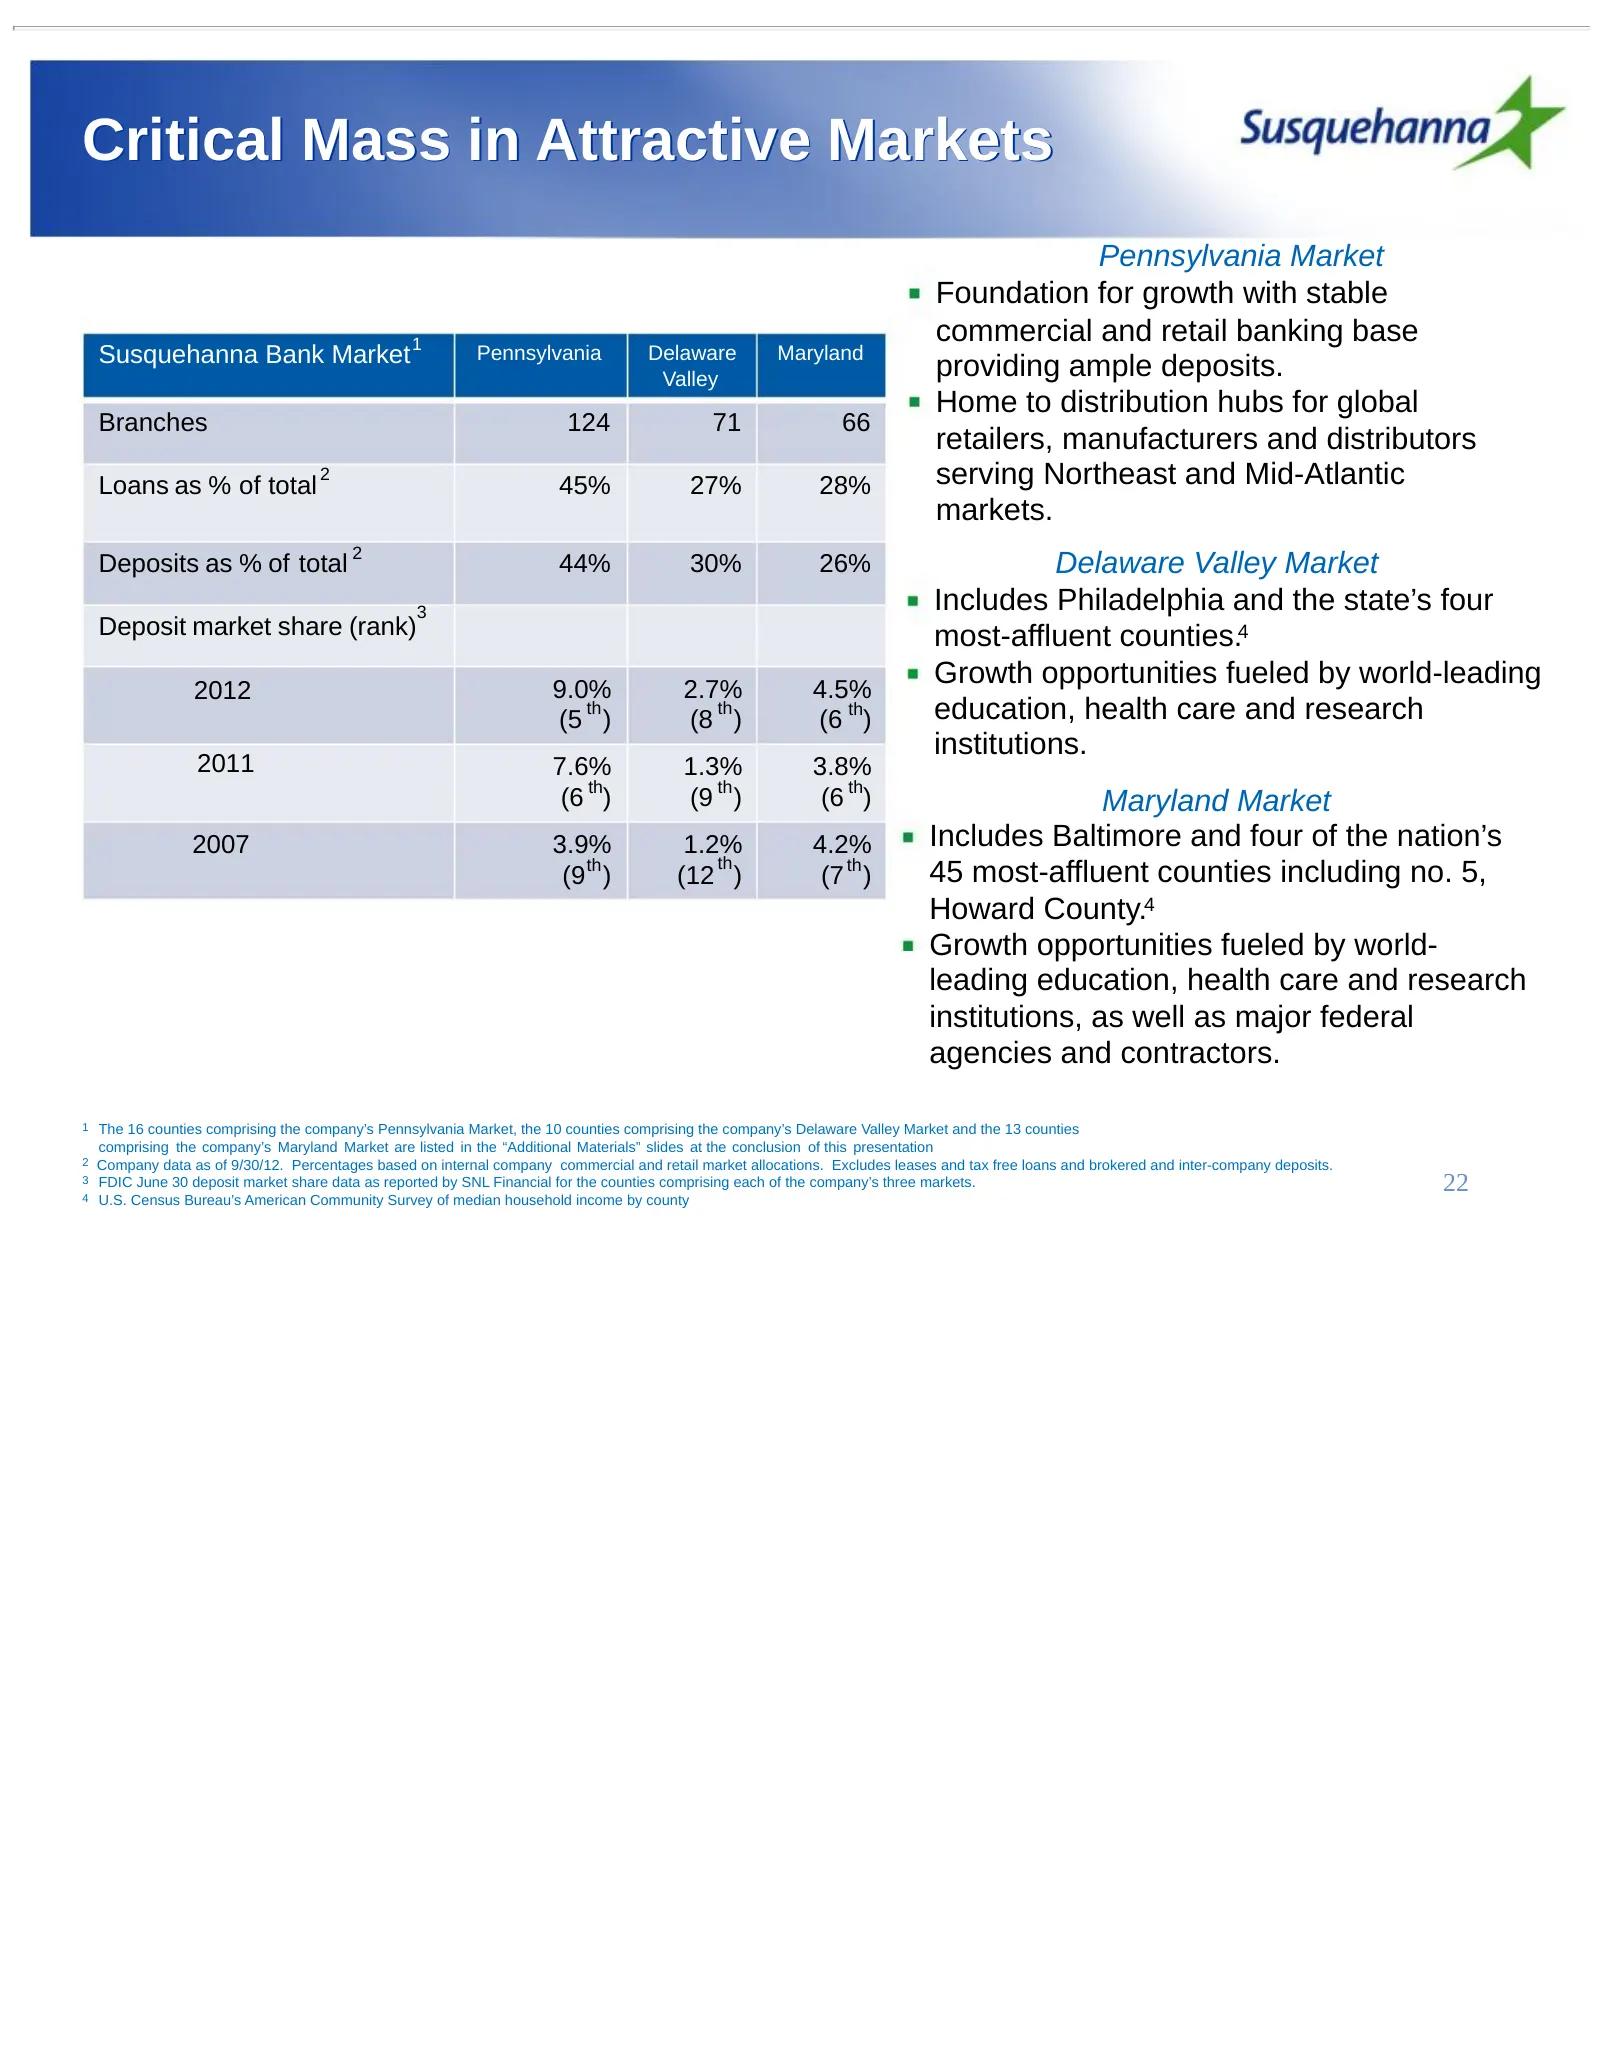
Critical Mass in Attractive Markets Pennsylvania Market Foundation for growth with stable 1 commercial and retail banking base Susquehanna Bank Market Pennsylvania Delaware Maryland Valley providing ample deposits. Home to distribution hubs for global Branches 124 71 66 retailers, manufacturers and
Slide 23: 4th Quarter 2012 Financial Highlights
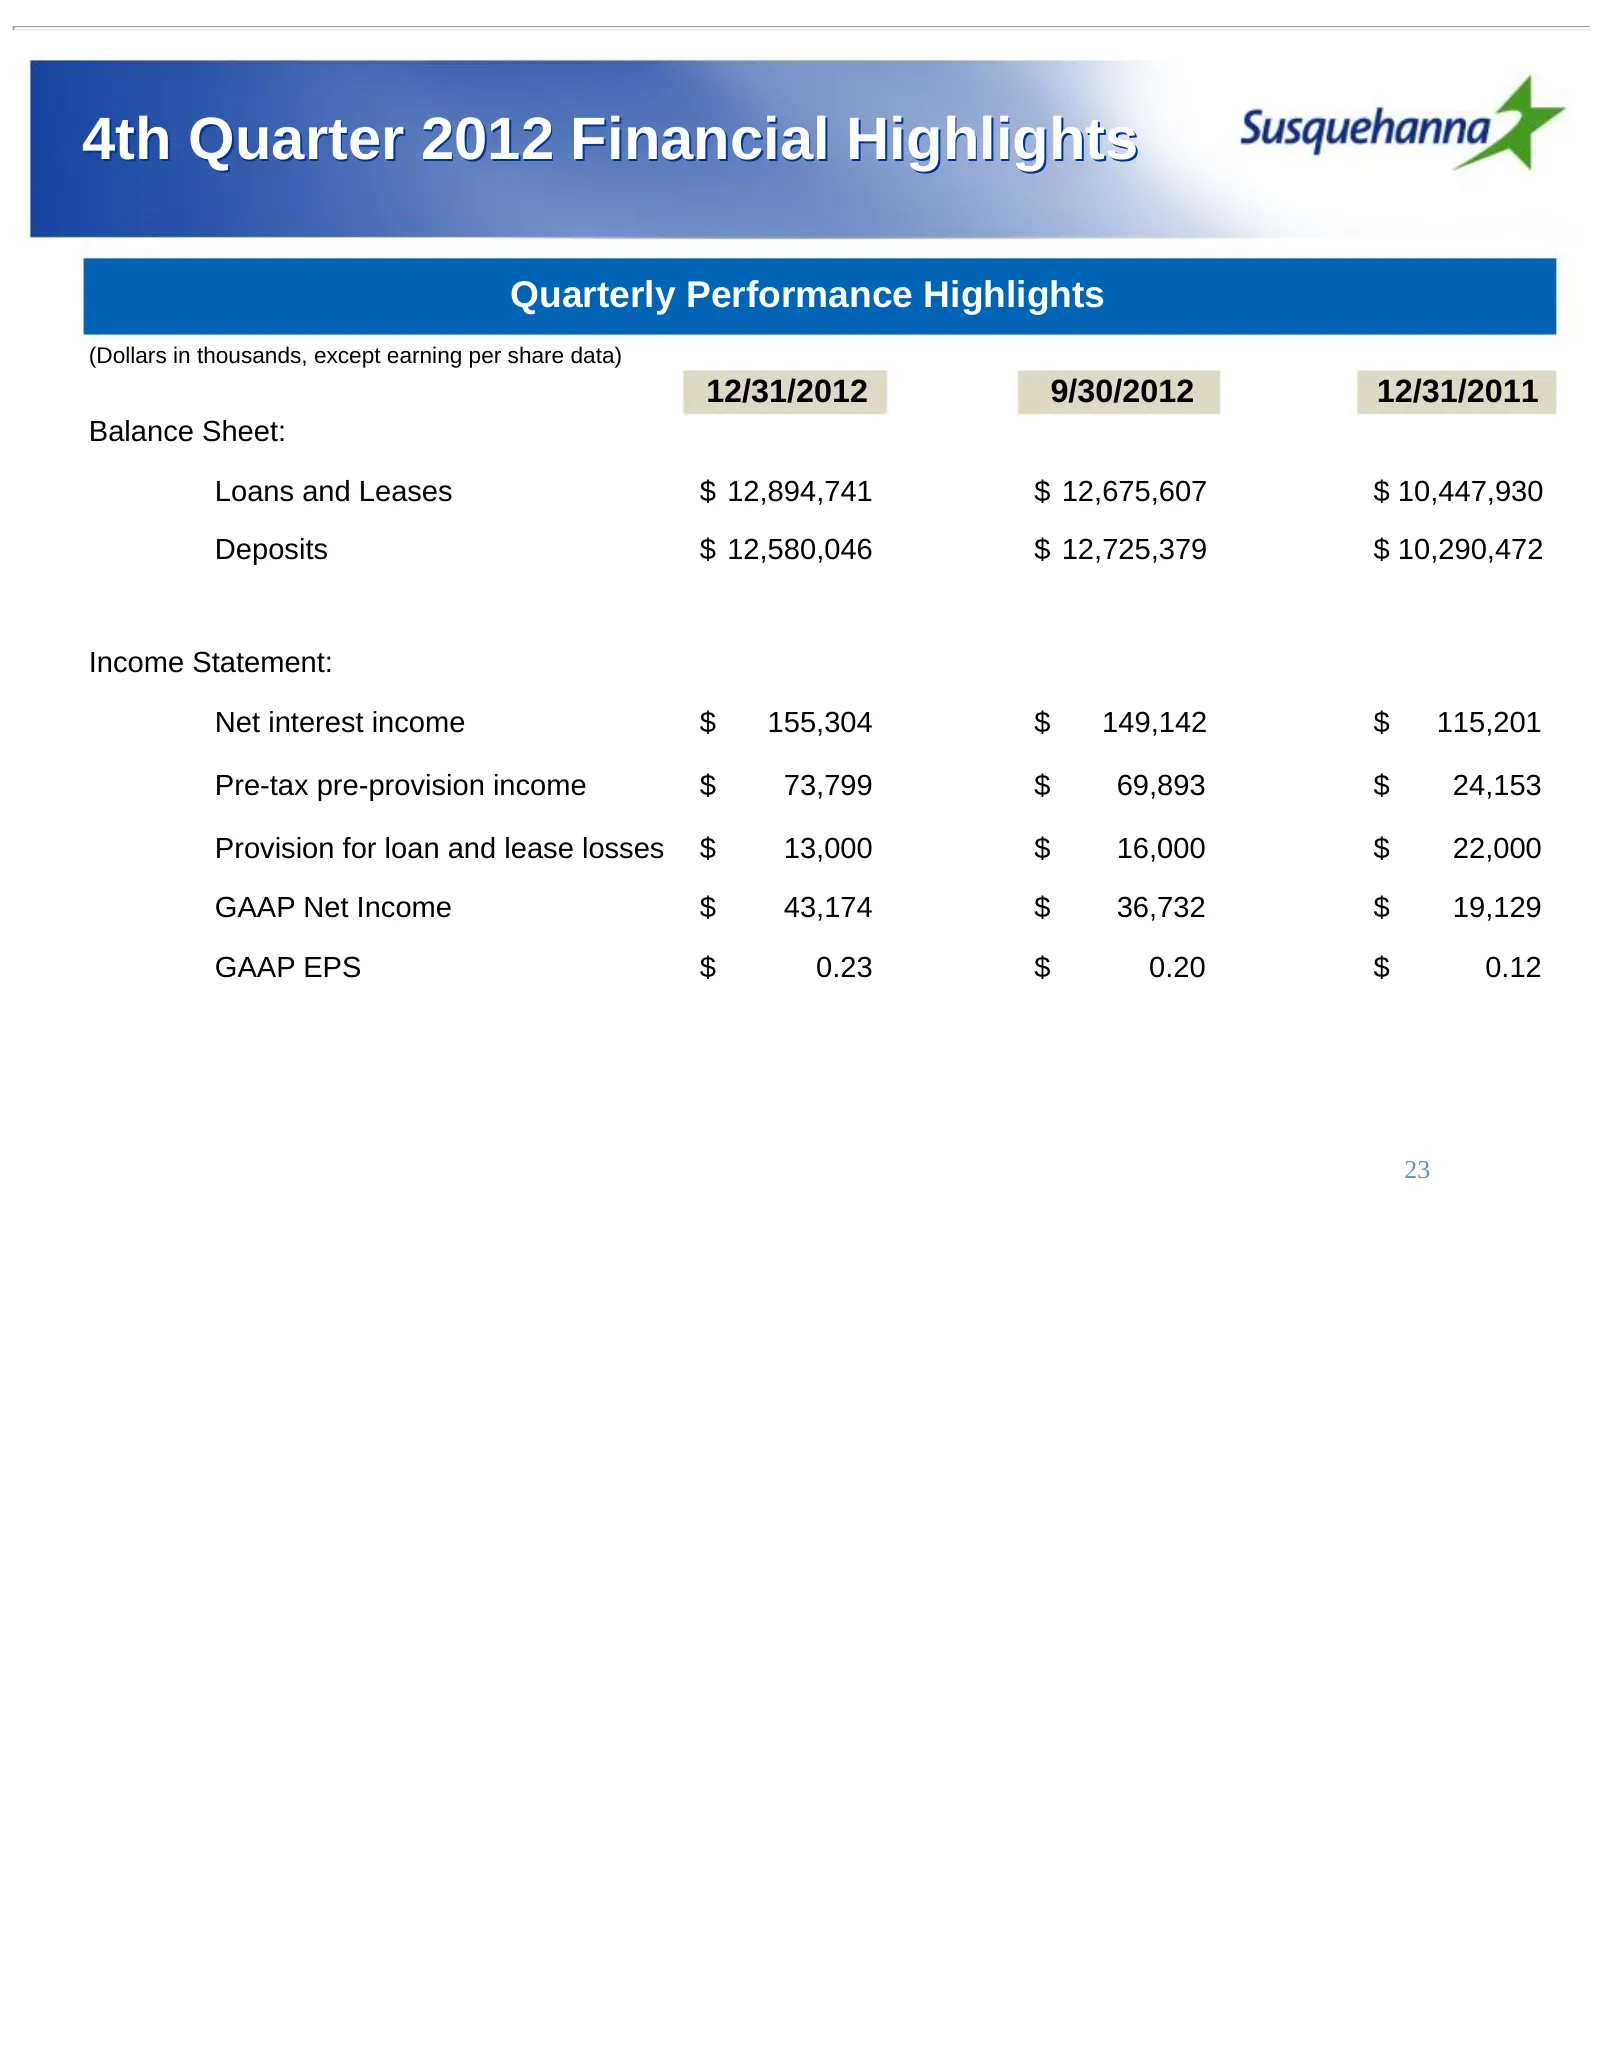
4th Quarter 2012 Financial Highlights Quarterly Performance Highlights (Dollars in thousands, except earning per share data) 12/31/2012 9/30/2012 12/31/2011 Balance Sheet: Loans and Leases $ 12,894,741 $ 12,675,607 $ 10,447,930 Deposits $ 12,580,046 $ 12,725,379 $ 10,290,472 Income Statement: Net in
Slide 24: Quarterly Loan and Lease Originations
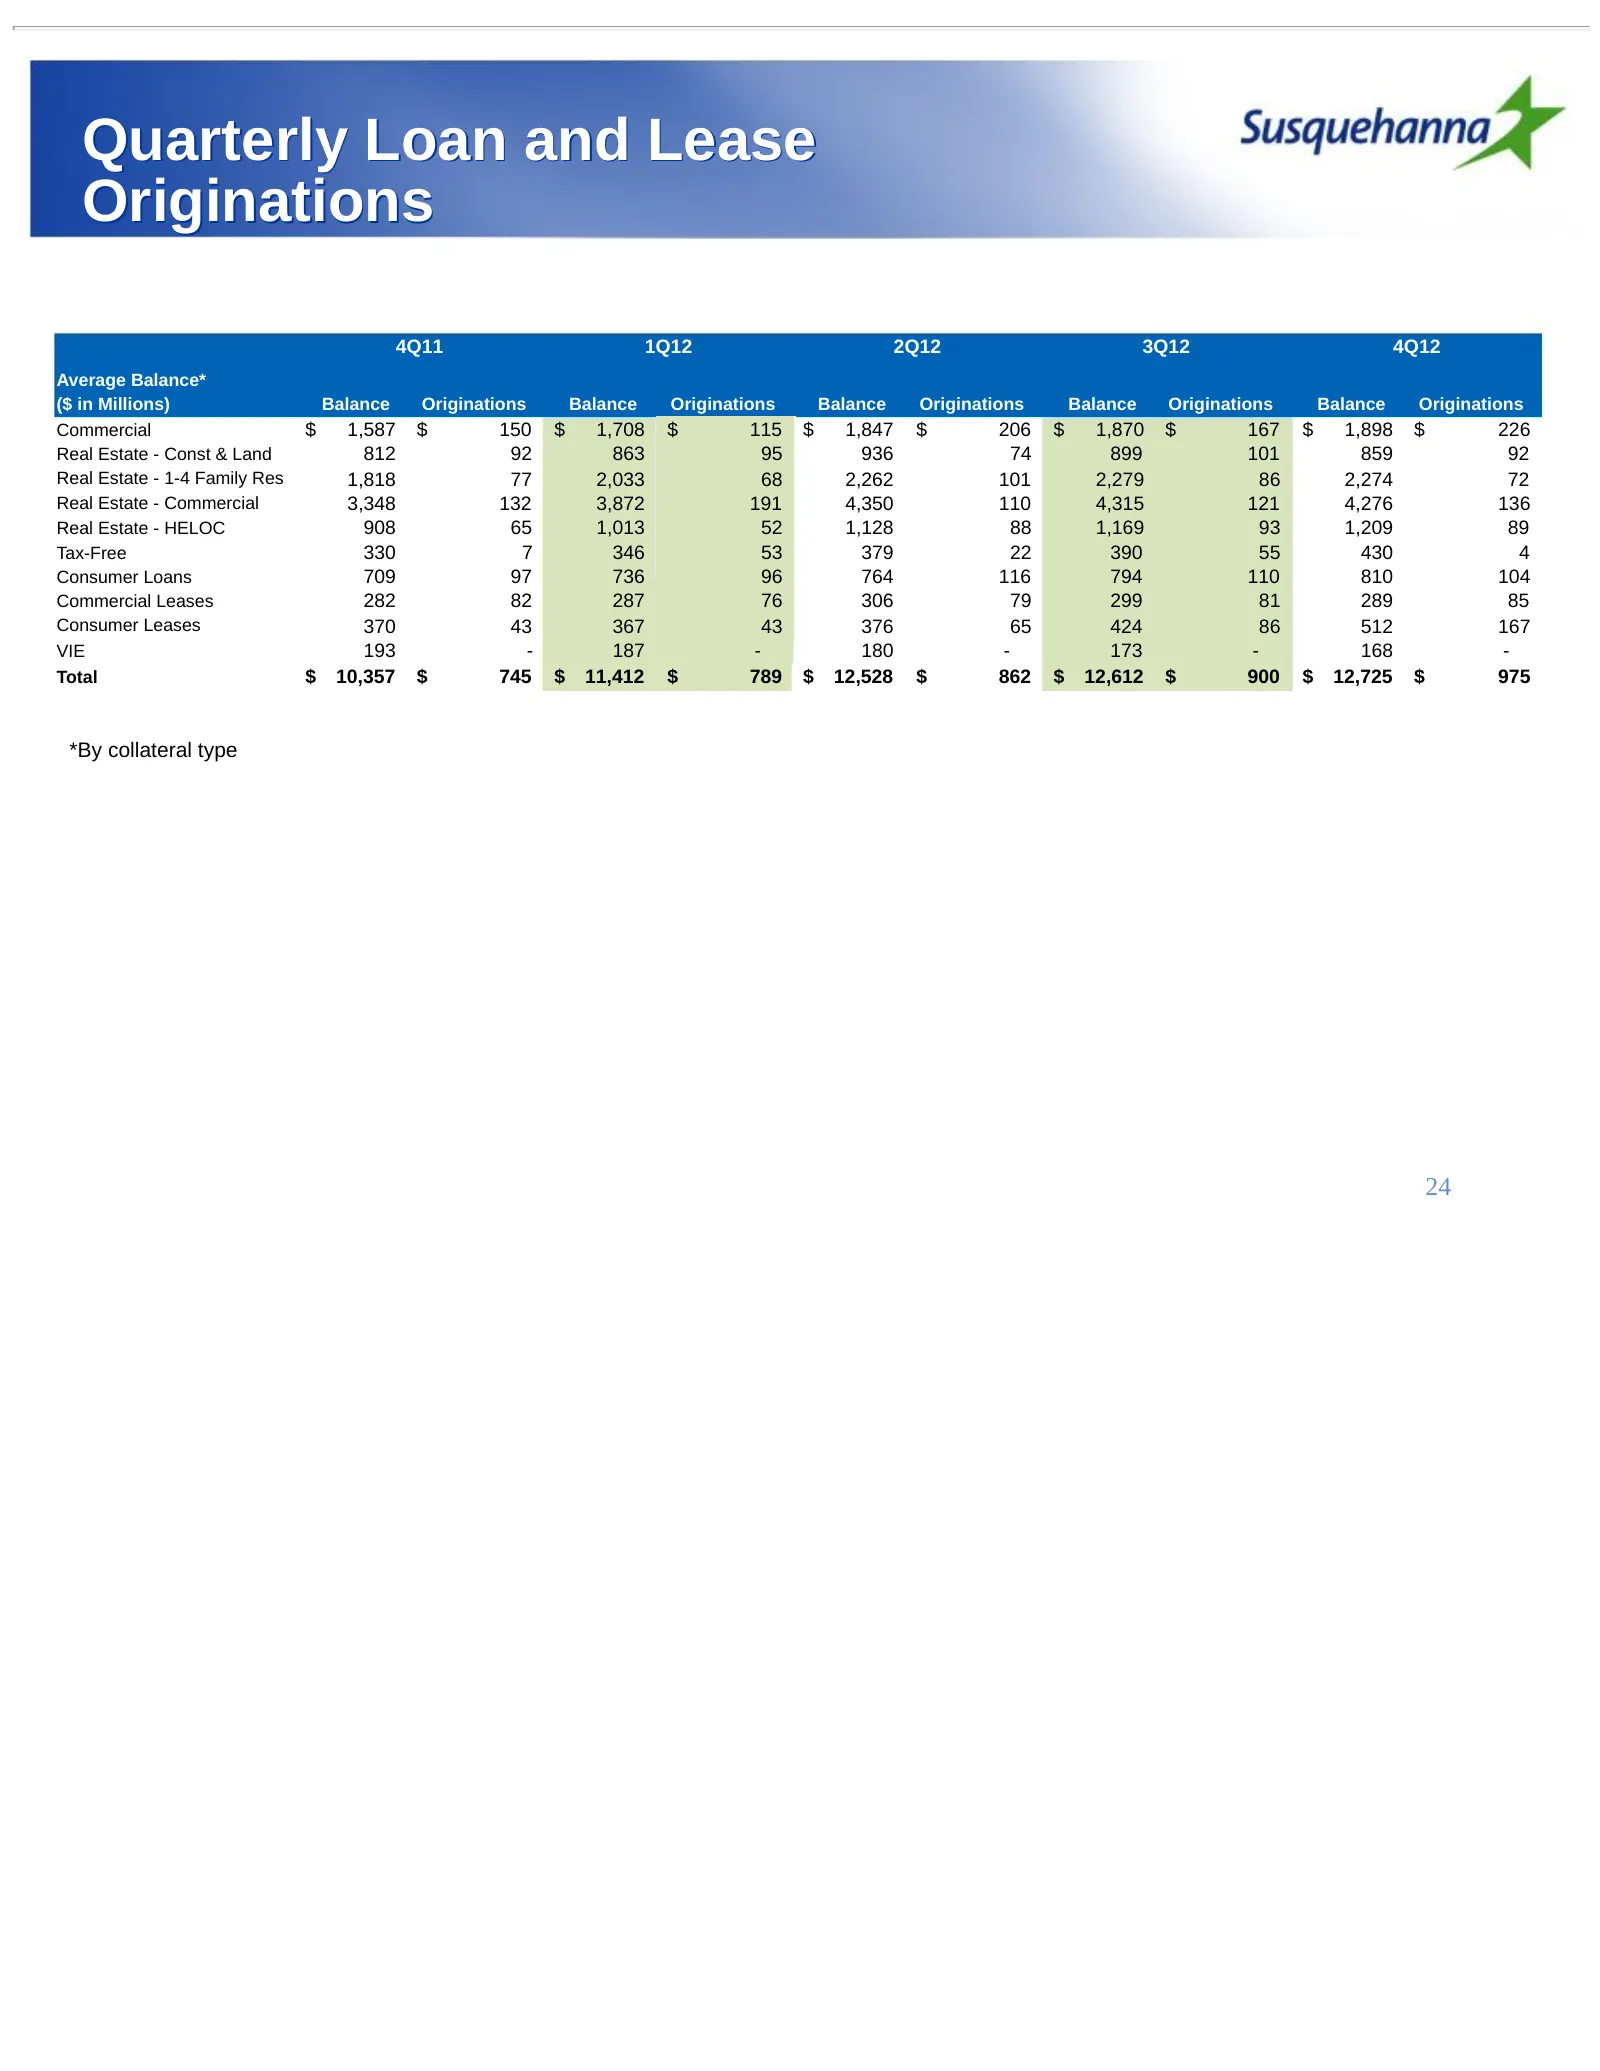
Quarterly Loan and Lease Originations 4Q11 1Q12 2Q12 3Q12 4Q12 Average Balance* ($ in Millions) Balance Originations Balance Originations Balance Originations Balance Originations Balance Originations Commercial $ 1,587 $ 150 $ 1,708 $ 115 $ 1,847 $ 206 $ 1,870 $ 167 $ 1,898 $ 226 Real Estate - Cons
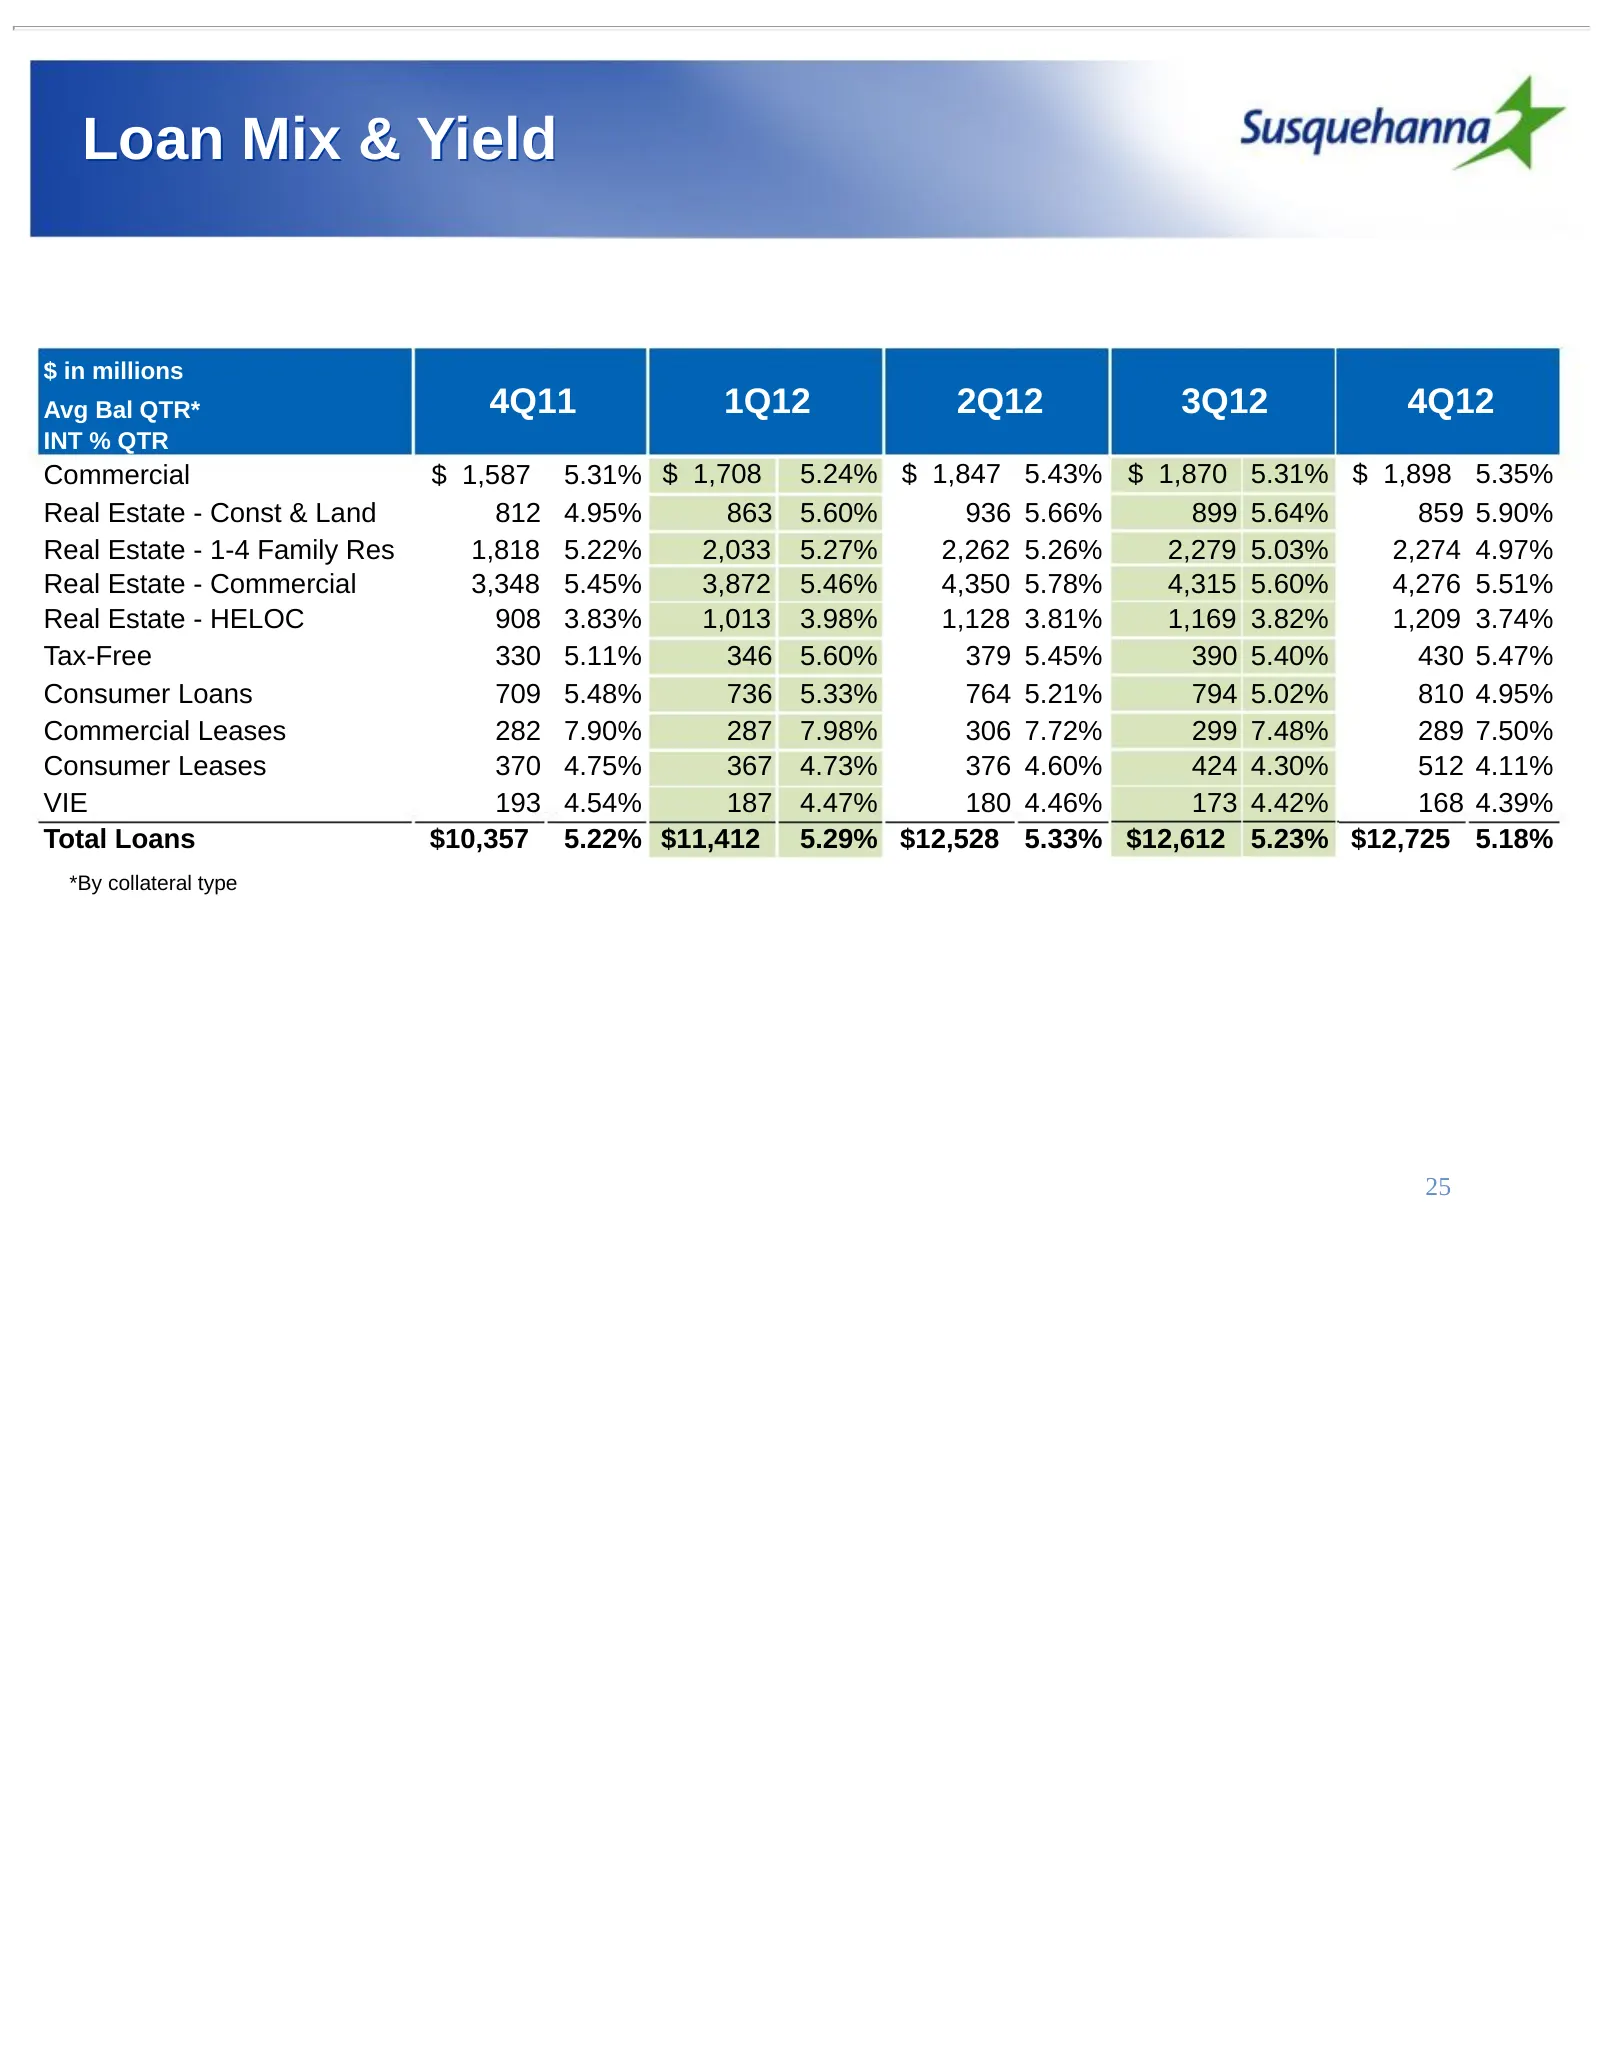
Slide 25: Loan Mix & Yield
Loan Mix & Yield $ in millions Avg Bal QTR* 4Q11 1Q12 2Q12 3Q12 4Q12 INT % QTR Commercial $ 1,587 5.31% $ 1,708 5.24% $ 1,847 5.43% $ 1,870 5.31% $ 1,898 5.35% Real Estate - Const & Land 812 4.95% 863 5.60% 936 5.66% 899 5.64% 859 5.90% Real Estate - 1-4 Family Res 1,818 5.22% 2,033 5.27% 2,262 5.26
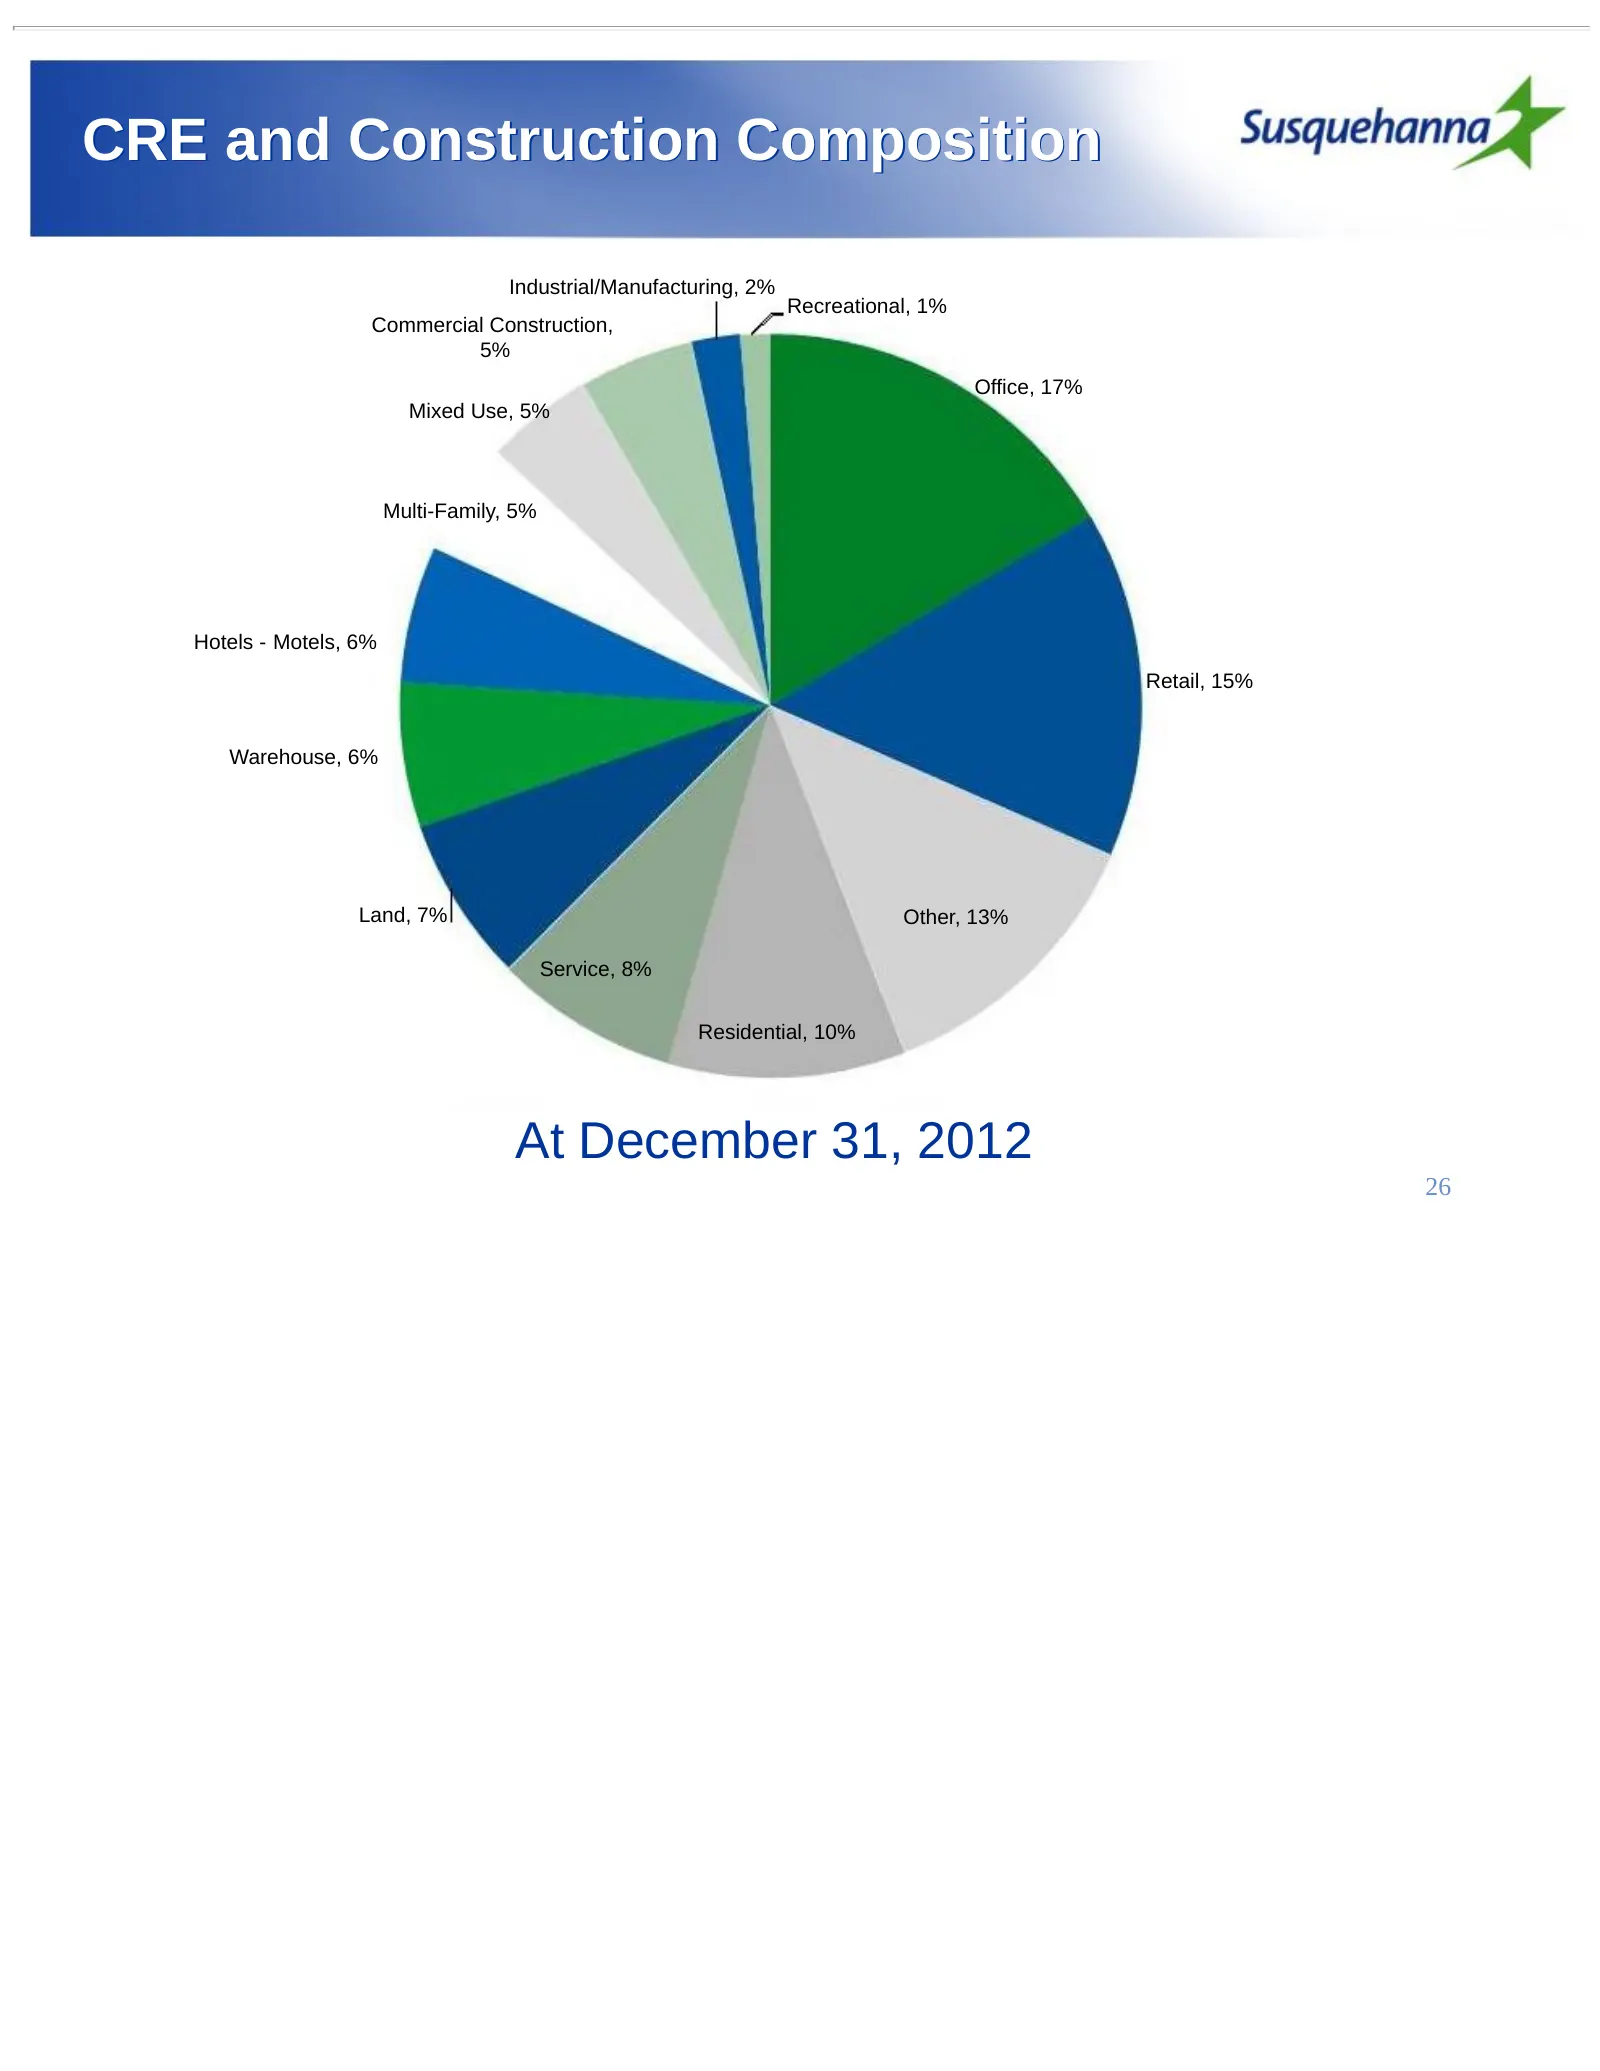
Slide 26: CRE and Construction Composition
CRE and Construction Composition Industrial/Manufacturing, 2% Recreational, 1% Commercial Construction, 5% Office, 17% Mixed Use, 5% Multi-Family, 5% Hotels - Motels, 6% Retail, 15% Warehouse, 6% Land, 7% Other, 13% Service, 8% Residential, 10% At December 31, 2012 26
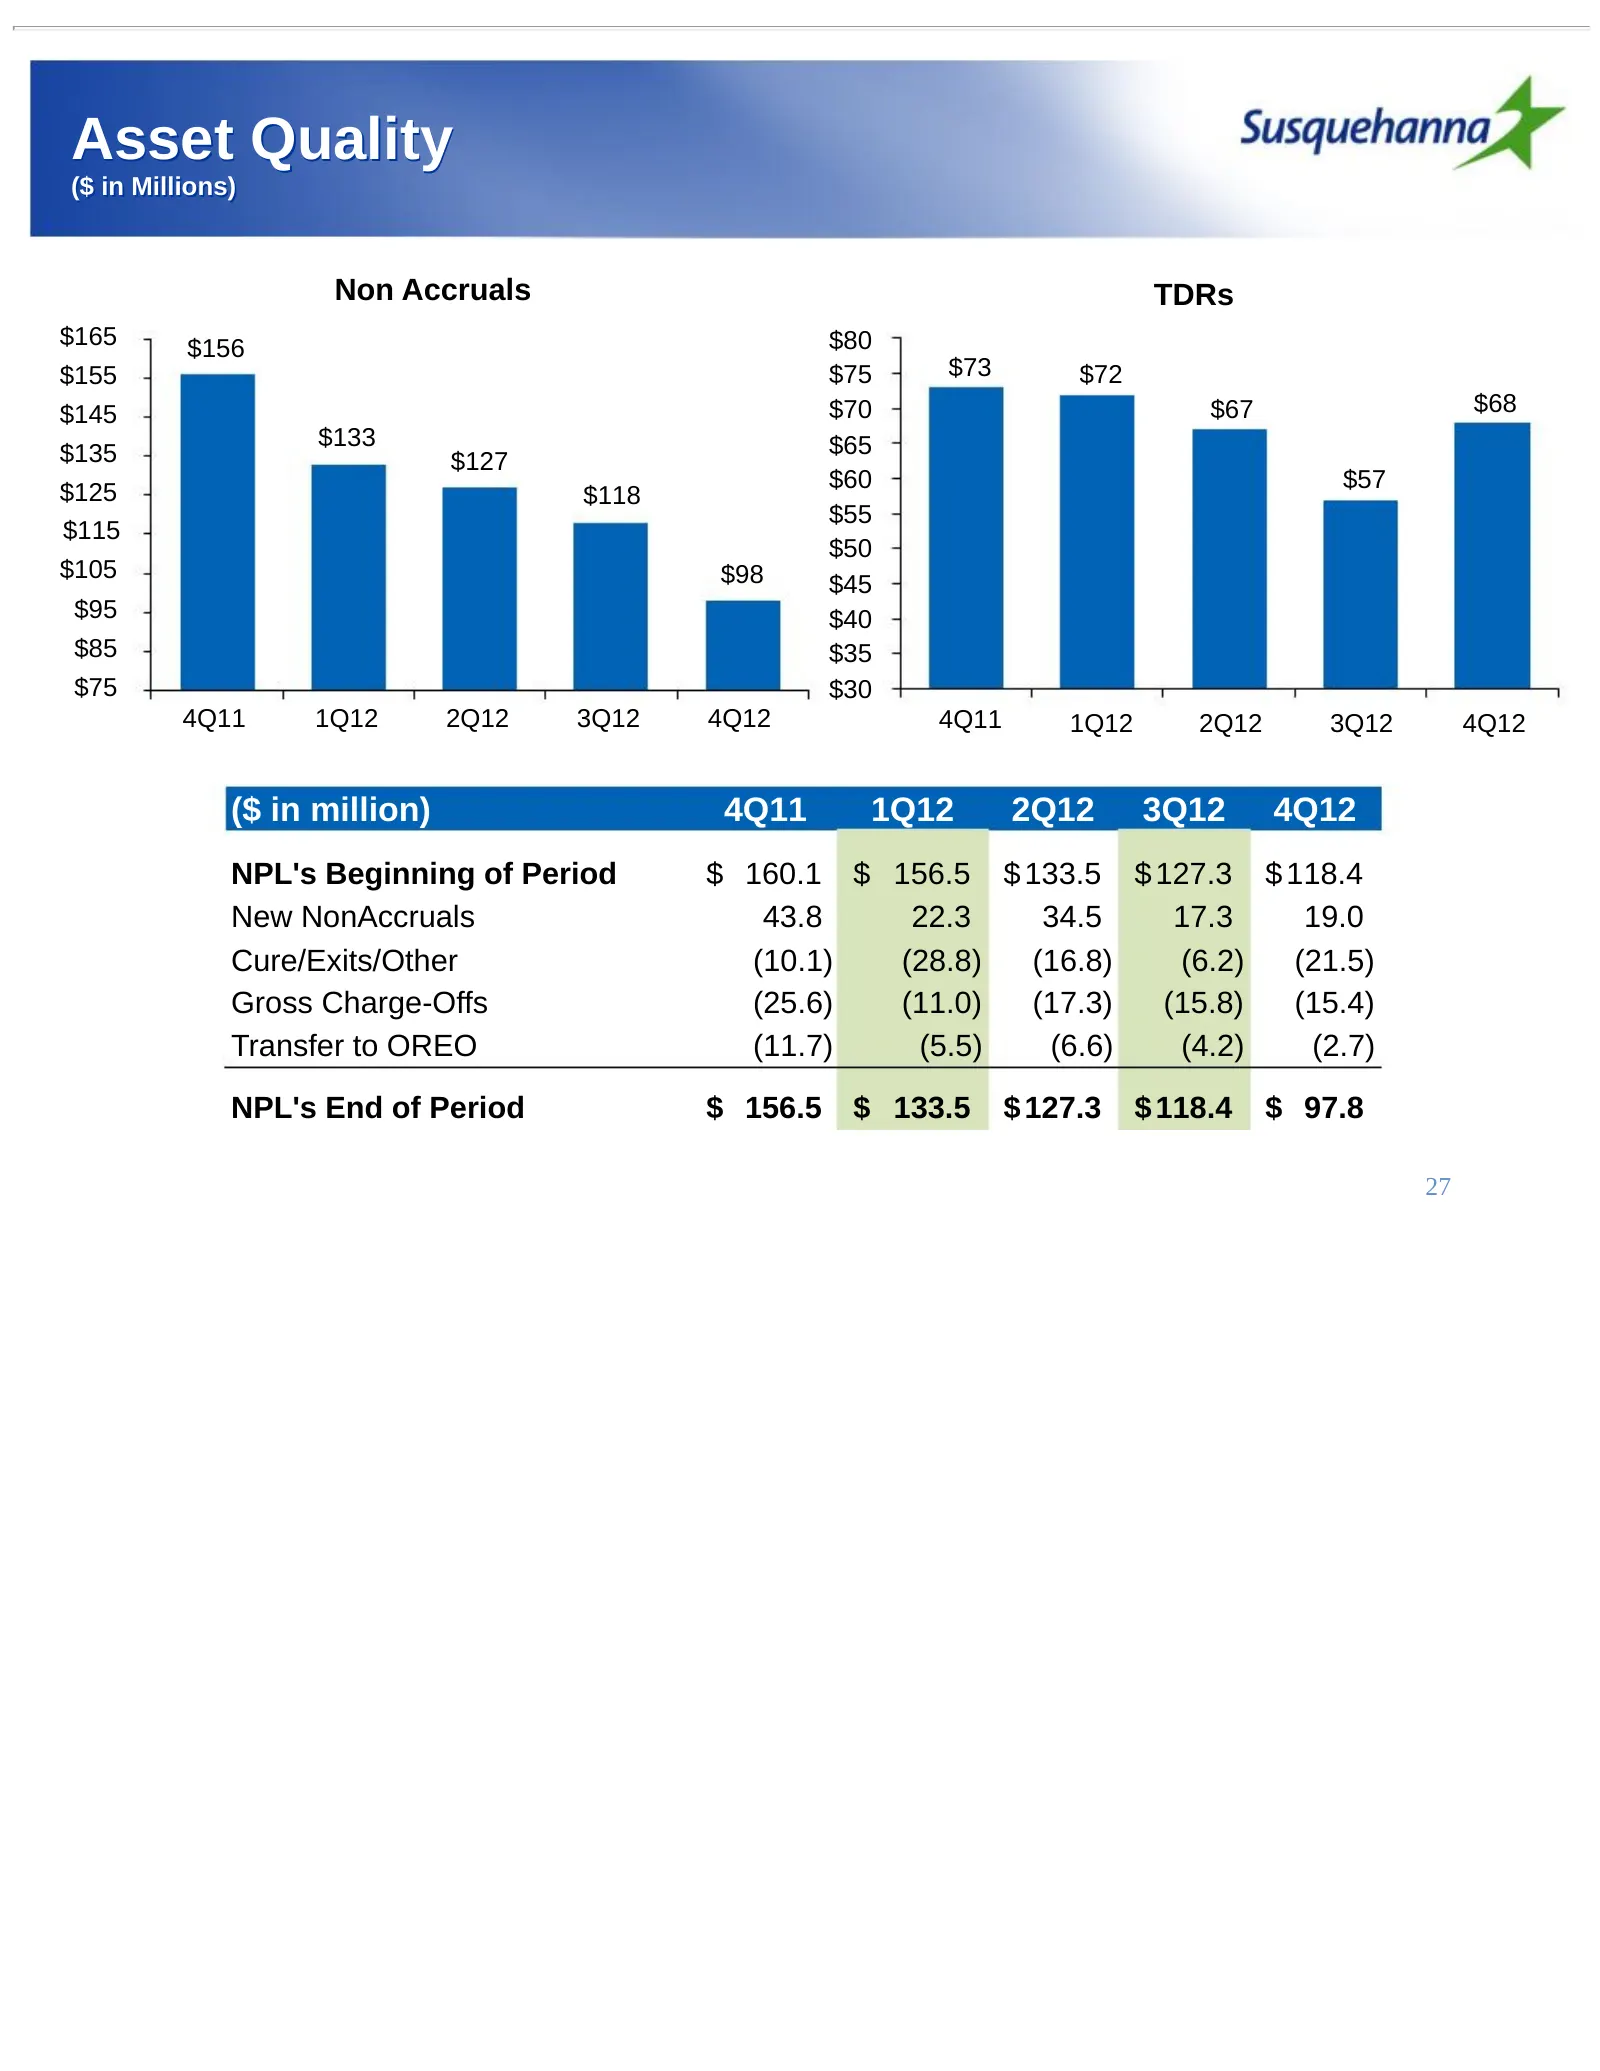
Slide 27: Asset Quality
Asset Quality ($ in Millions) Non Accruals TDRs $165 $156 $80 $155 $75 $73 $72 $145 $70 $67 $68 $133 $65 $135 $127 $125 $60 $57 $118 $55 $115 $50 $105 $98 $45 $95 $40 $85 $35 $75 $30 4Q11 1Q12 2Q12 3Q12 4Q12 4Q11 1Q12 2Q12 3Q12 4Q12 ($ in million) 4Q11 1Q12 2Q12 3Q12 4Q12 NPL's Beginning of Period $
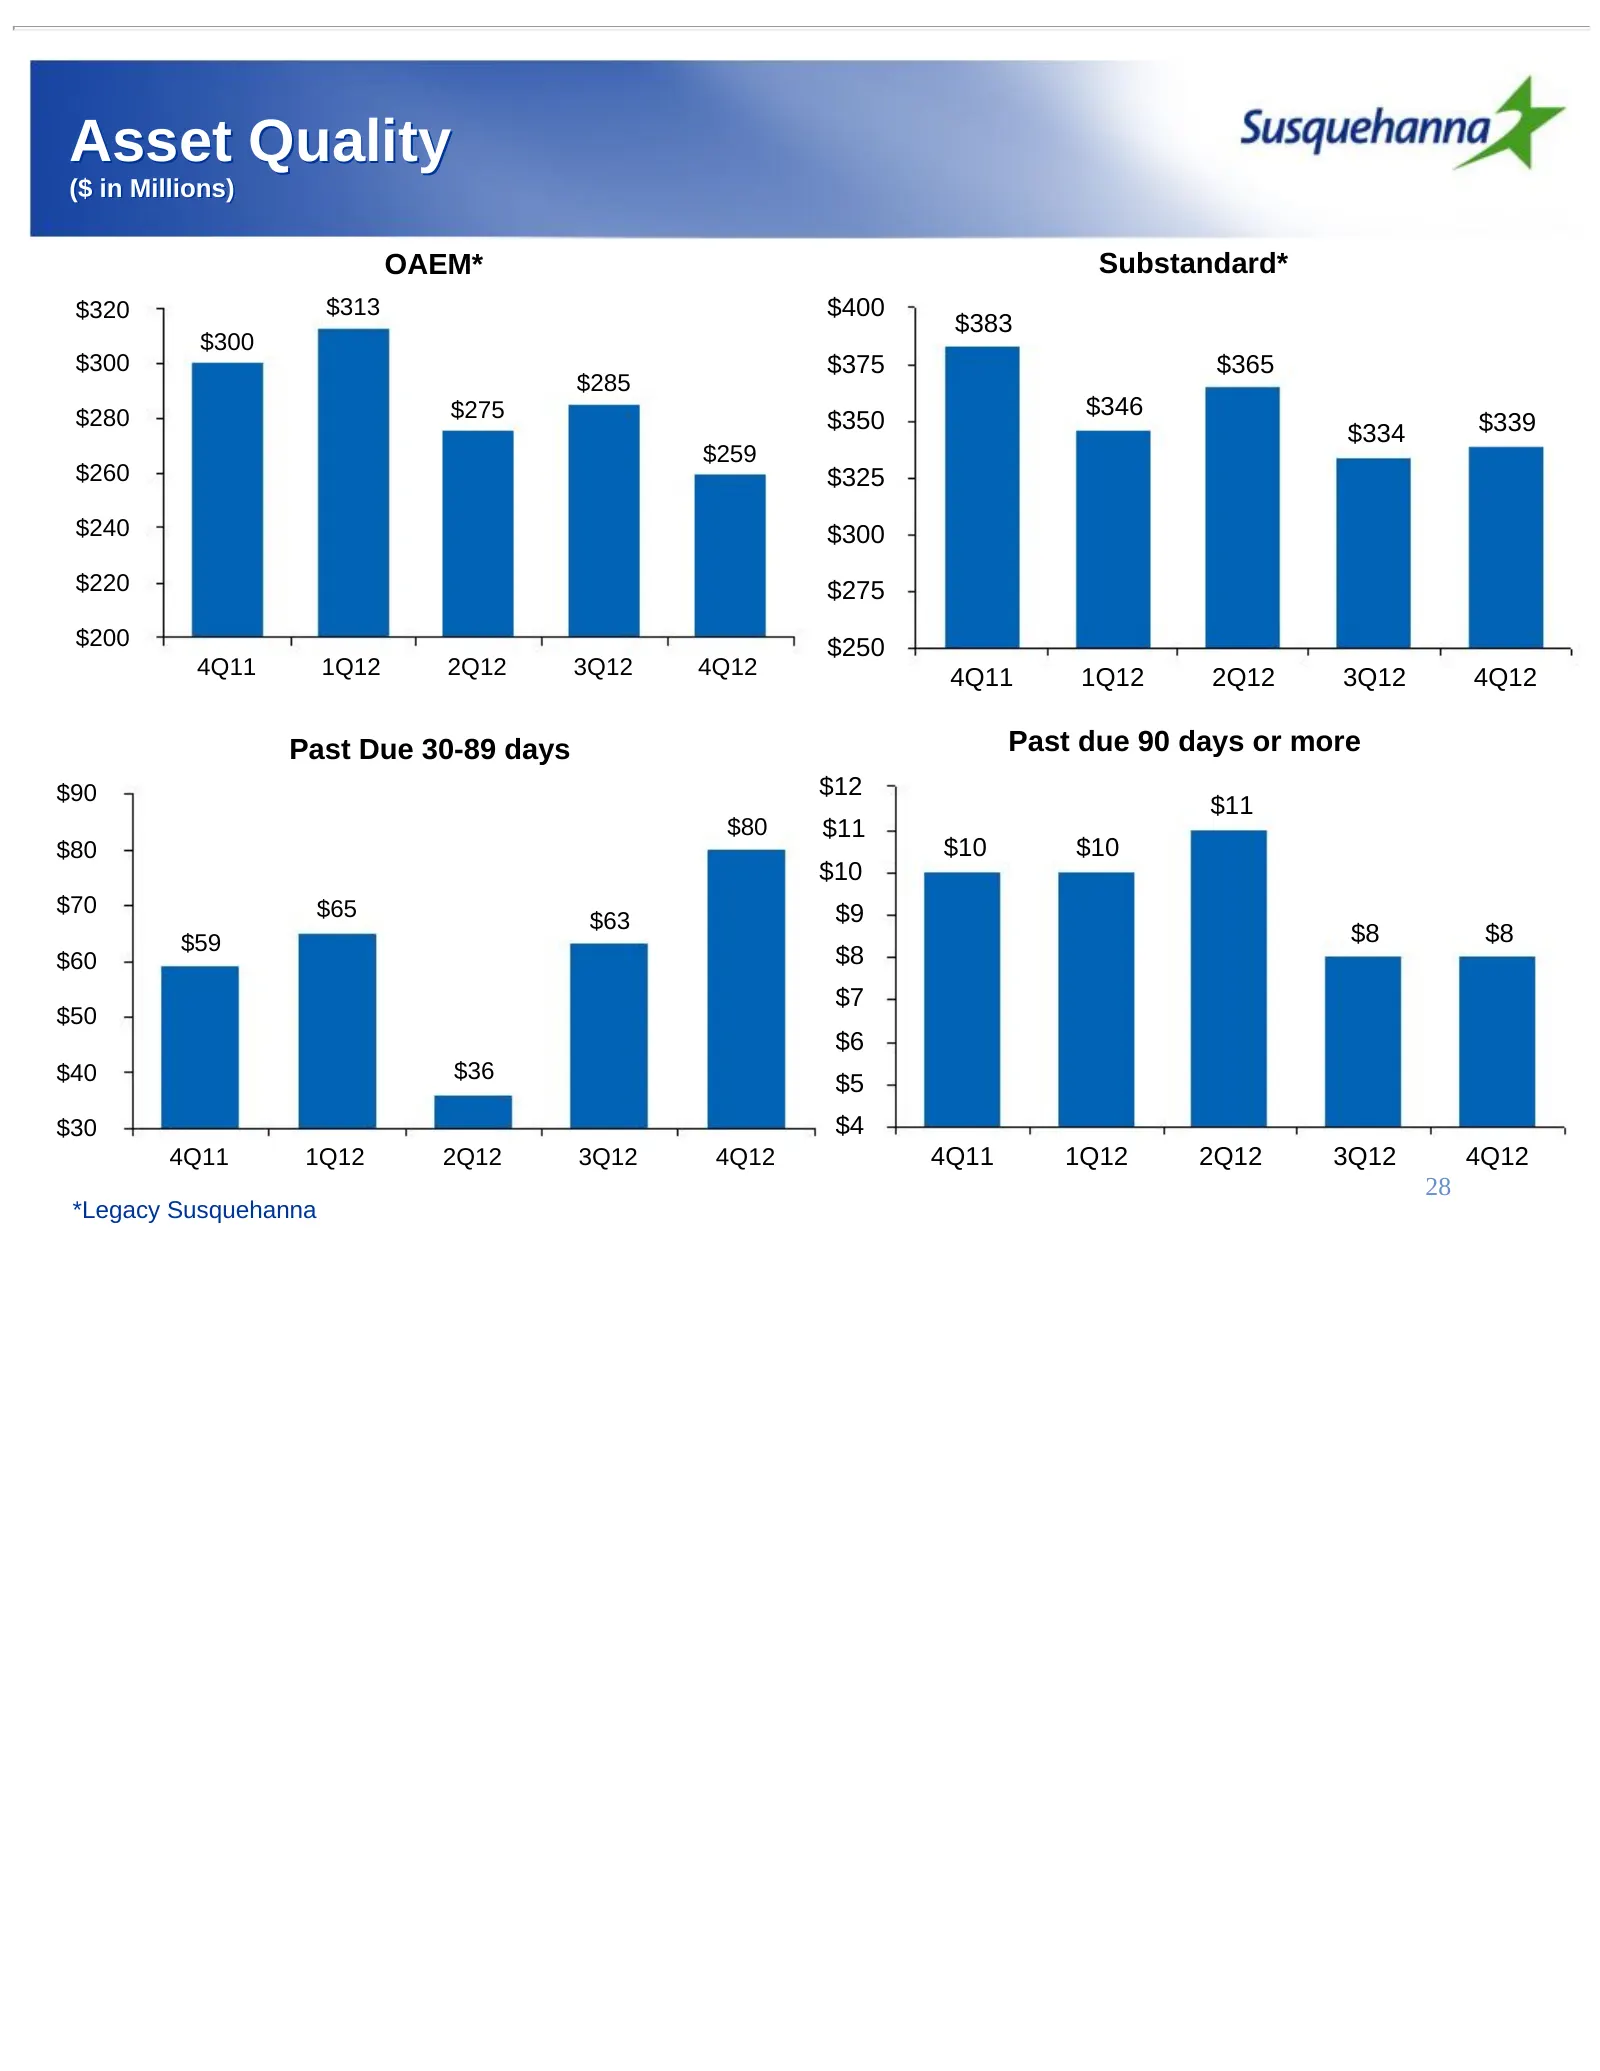
Slide 28: Asset Quality
Asset Quality ($ in Millions) OAEM* Substandard* $320 $313 $400 $383 $300 $300 $375 $365 $285 $280 $275 $346 $350 $334 $339 $259 $260 $325 $240 $300 $220 $275 $200 $250 4Q11 1Q12 2Q12 3Q12 4Q12 4Q11 1Q12 2Q12 3Q12 4Q12 Past Due 30-89 days Past due 90 days or more $90 $12 $11 $80 $11 $80 $10 $10 $10
Slide 29: Investment Securities
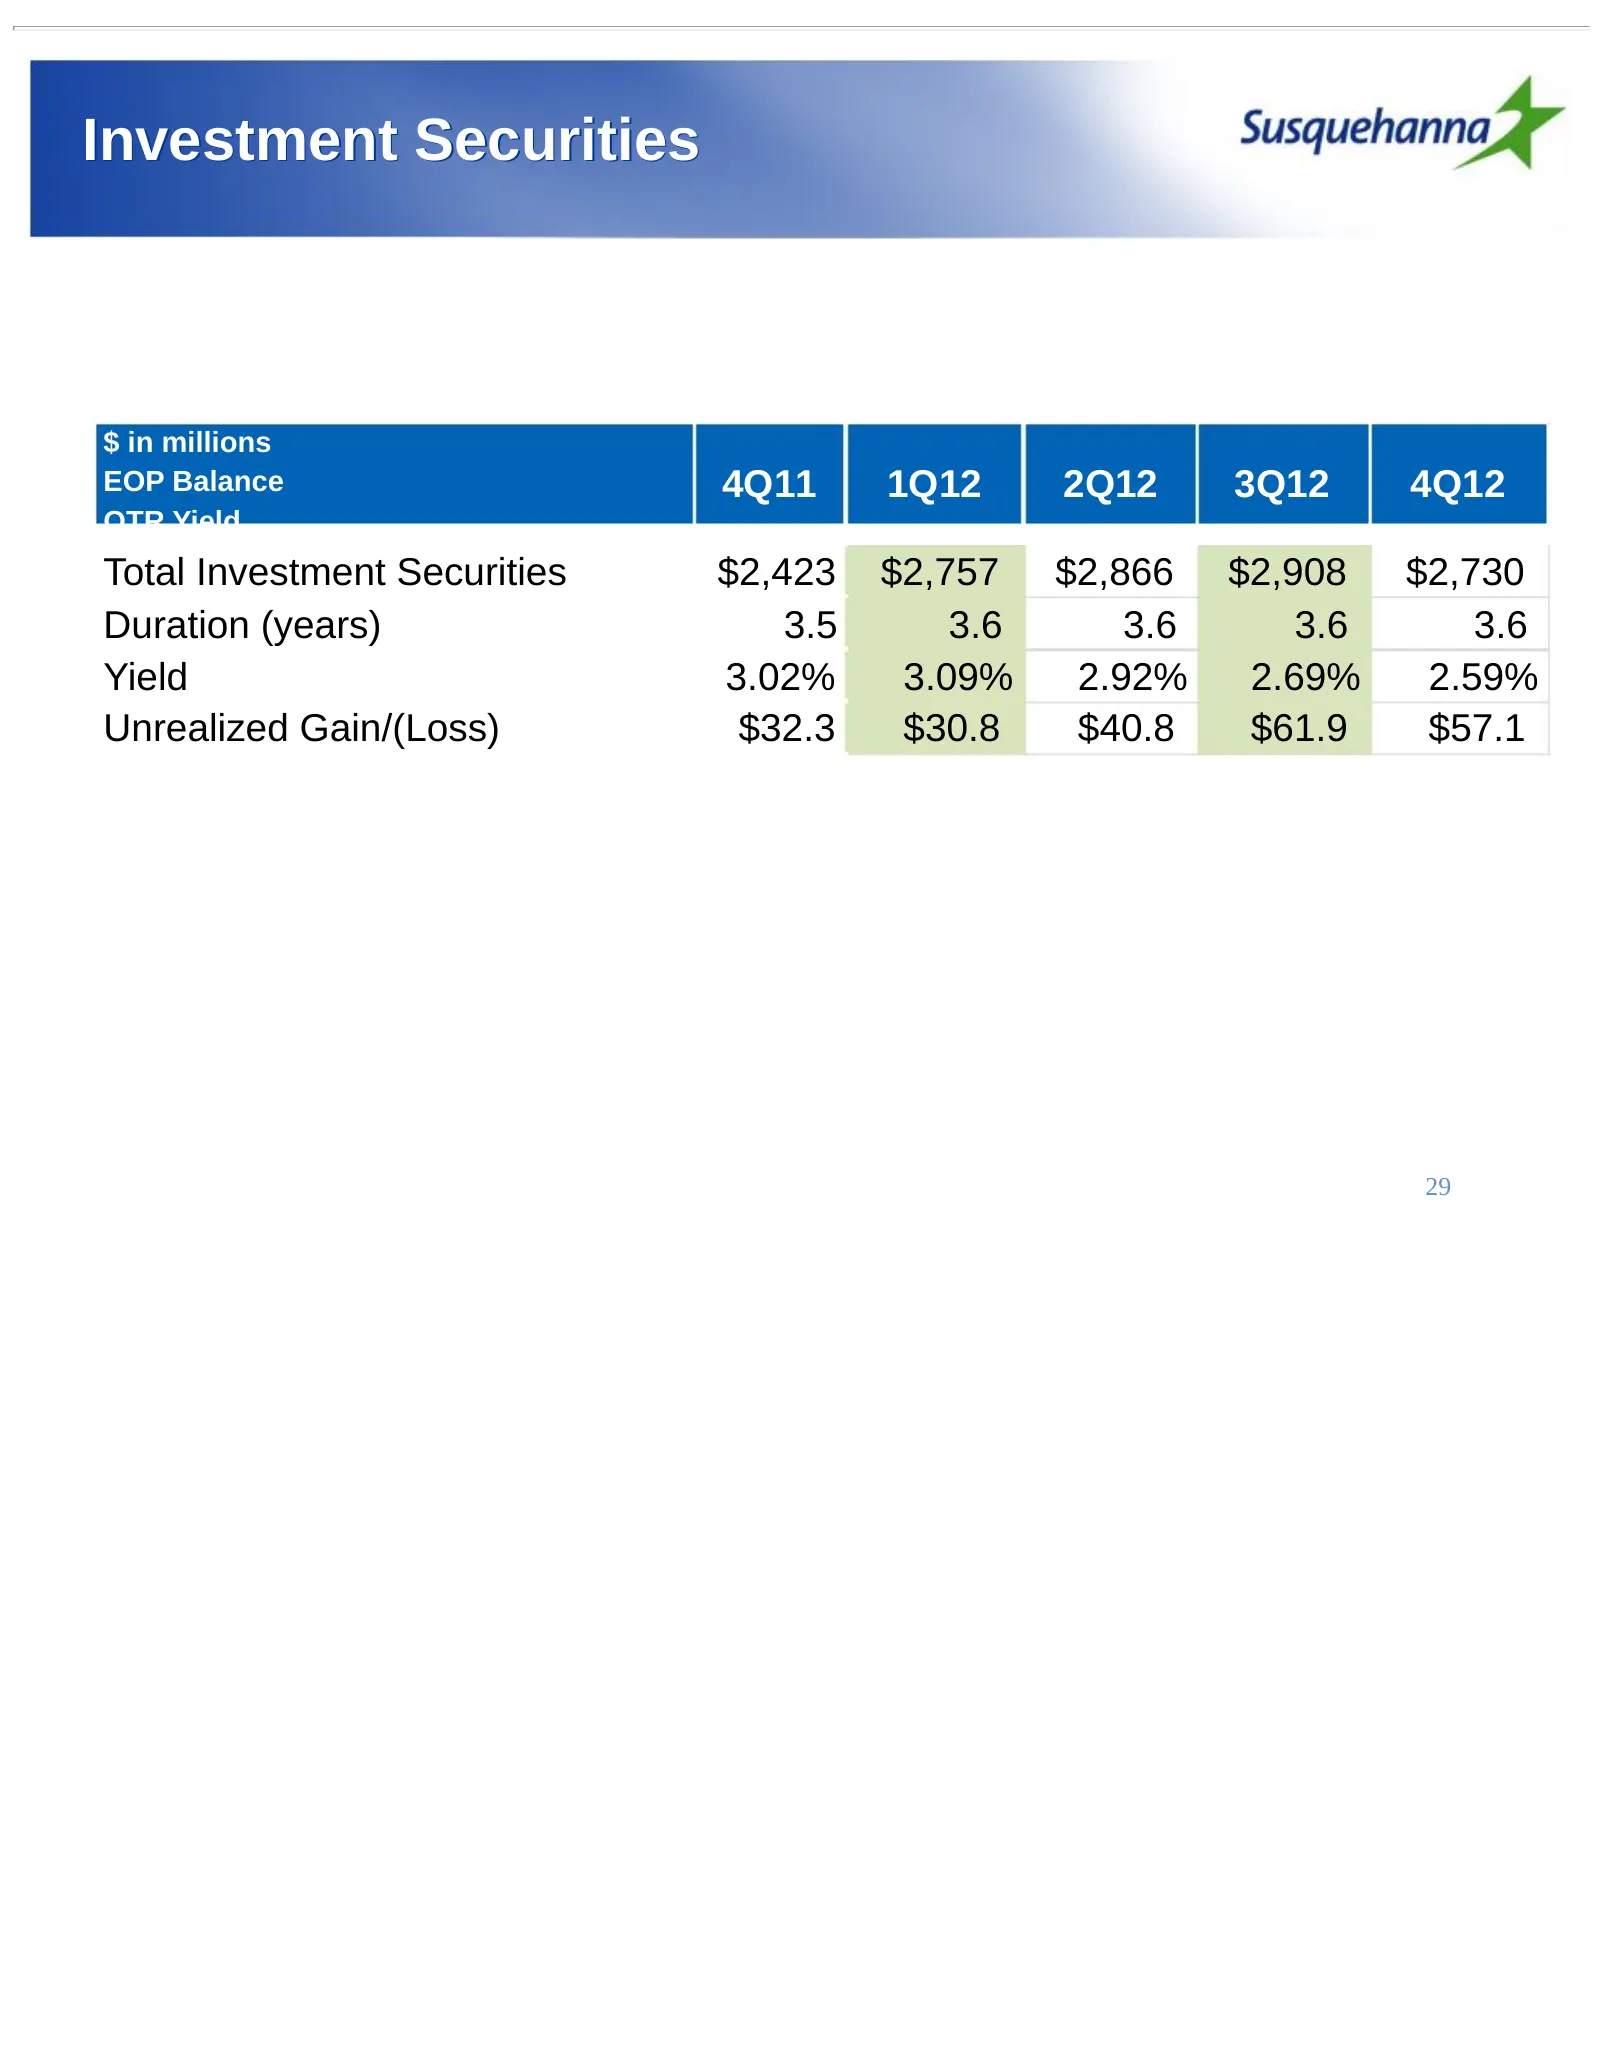
Investment Securities $ in millions EOP Balance 4Q11 1Q12 2Q12 3Q12 4Q12 QTR Yield Total Investment Securities $2,423 $2,757 $2,866 $2,908 $2,730 Duration (years) 3.5 3.6 3.6 3.6 3.6 Yield 3.02% 3.09% 2.92% 2.69% 2.59% Unrealized Gain/(Loss) $32.3 $30.8 $40.8 $61.9 $57.1 29
Slide 30: Deposit Mix & Cost by Product
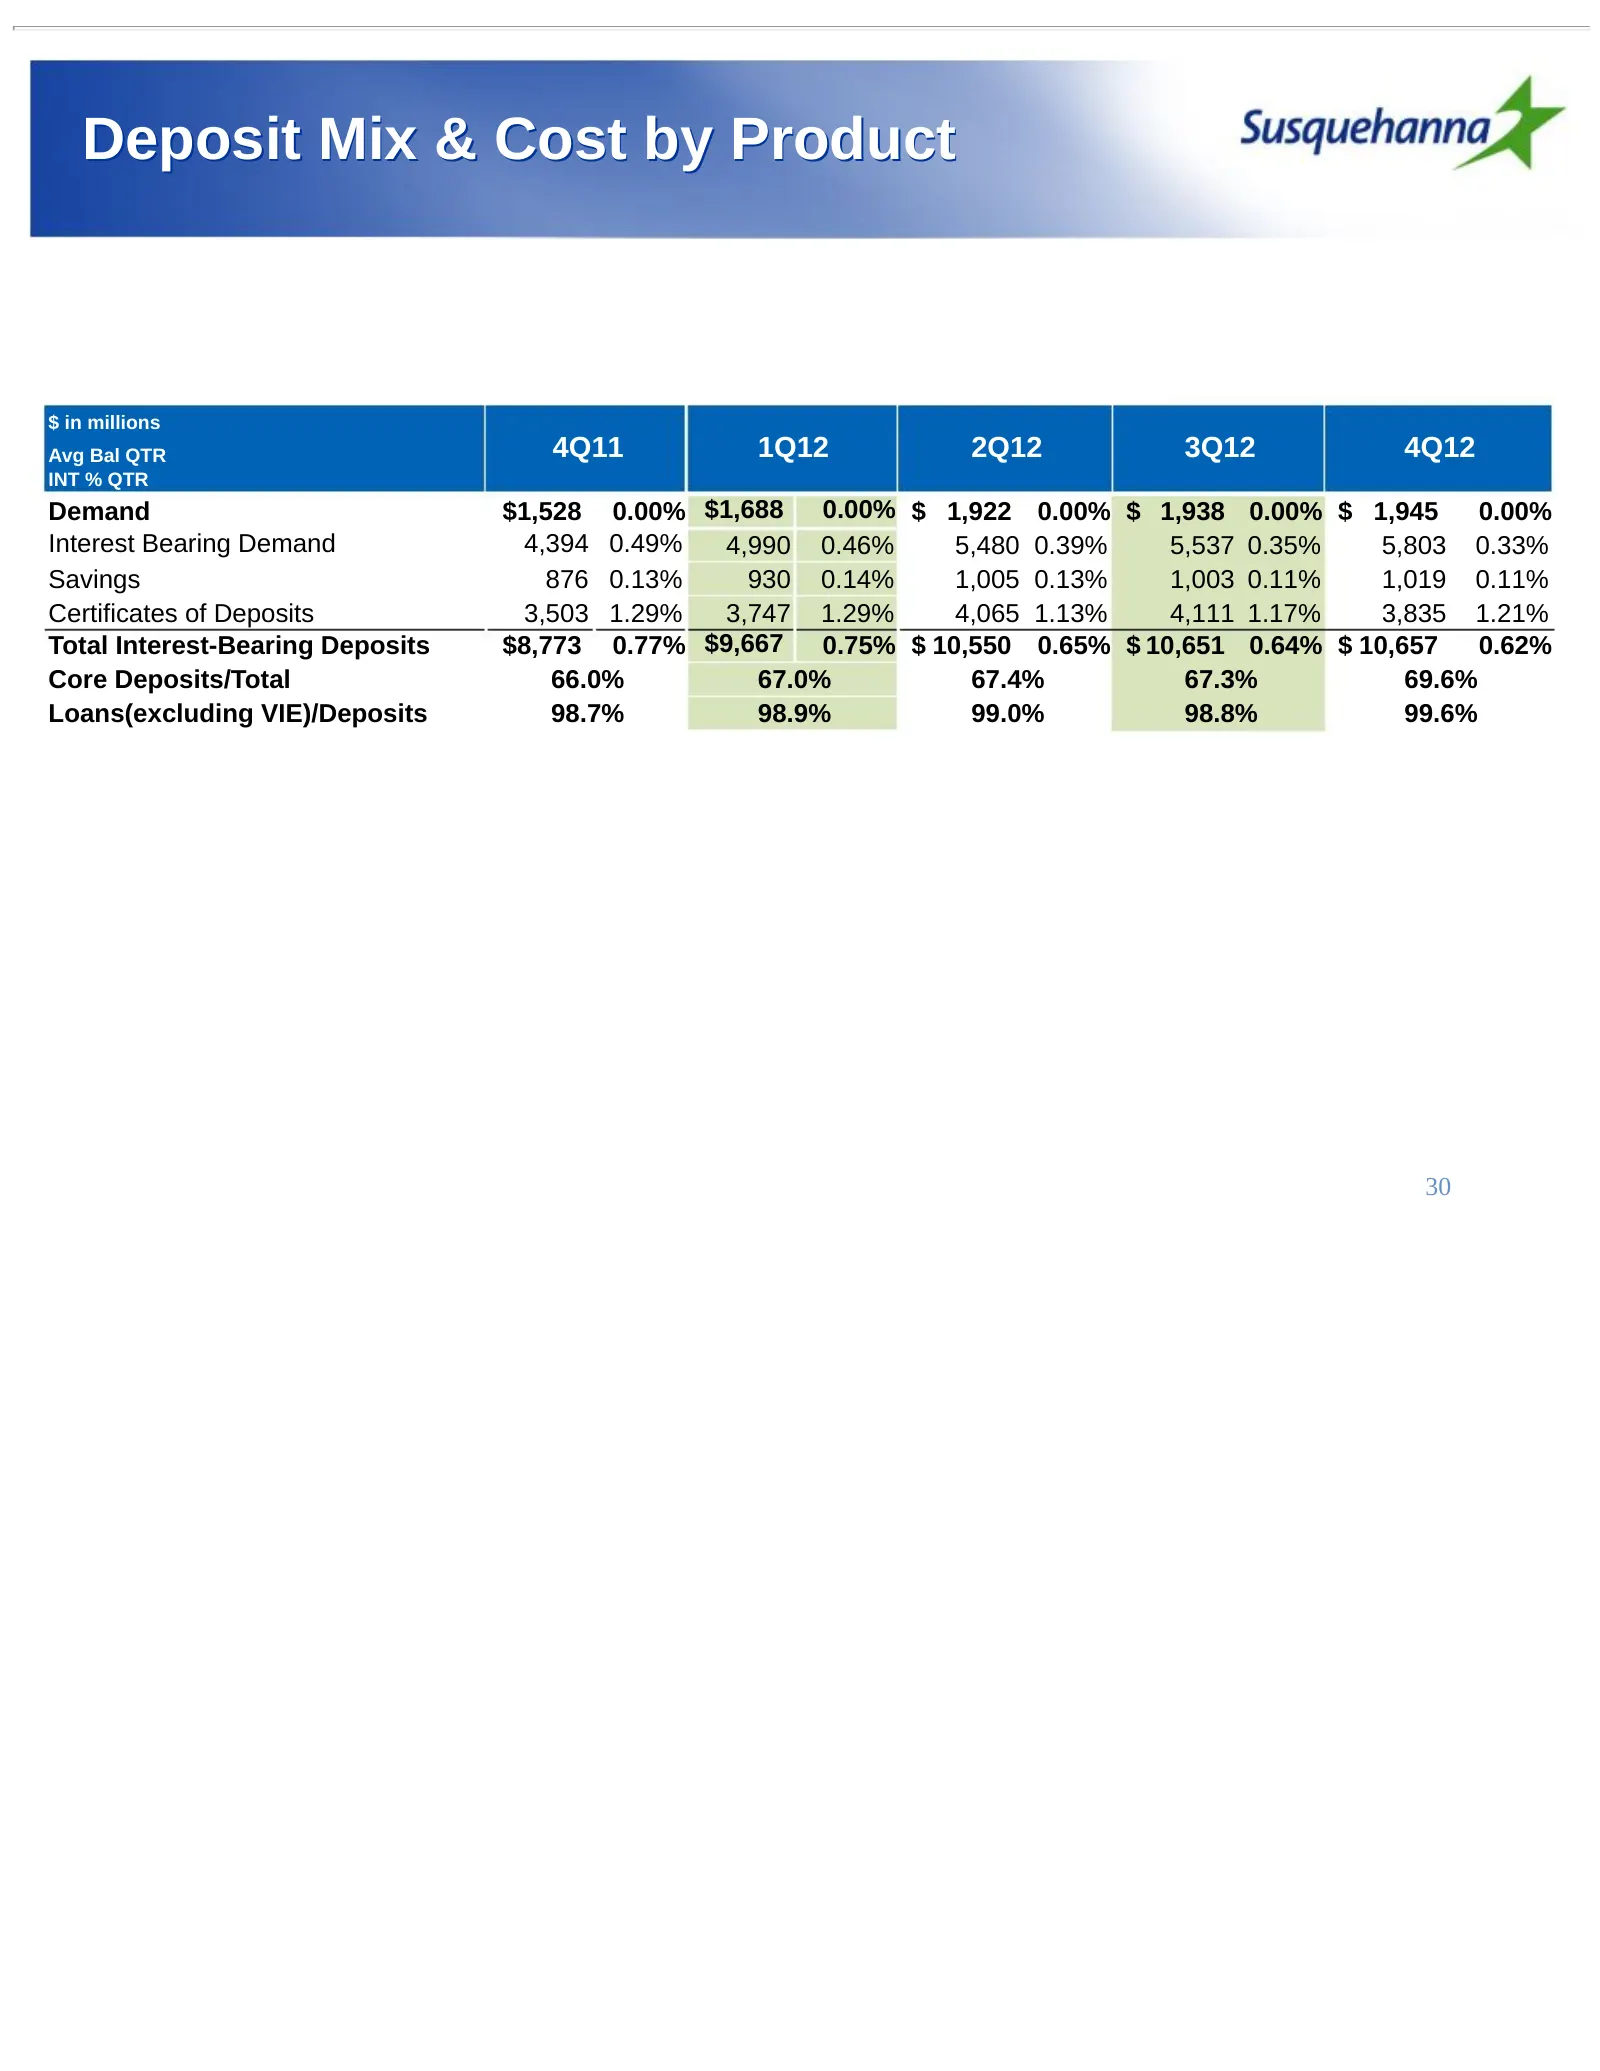
Deposit Mix & Cost by Product $ in millions Avg Bal QTR 4Q11 1Q12 2Q12 3Q12 4Q12 INT % QTR Demand $1,528 0.00% $1,688 0.00% $ 1,922 0.00% $ 1,938 0.00% $ 1,945 0.00% Interest Bearing Demand 4,394 0.49% 4,990 0.46% 5,480 0.39% 5,537 0.35% 5,803 0.33% Savings 876 0.13% 930 0.14% 1,005 0.13% 1,003 0.11
Slide 31: Borrowing Mix & Cost
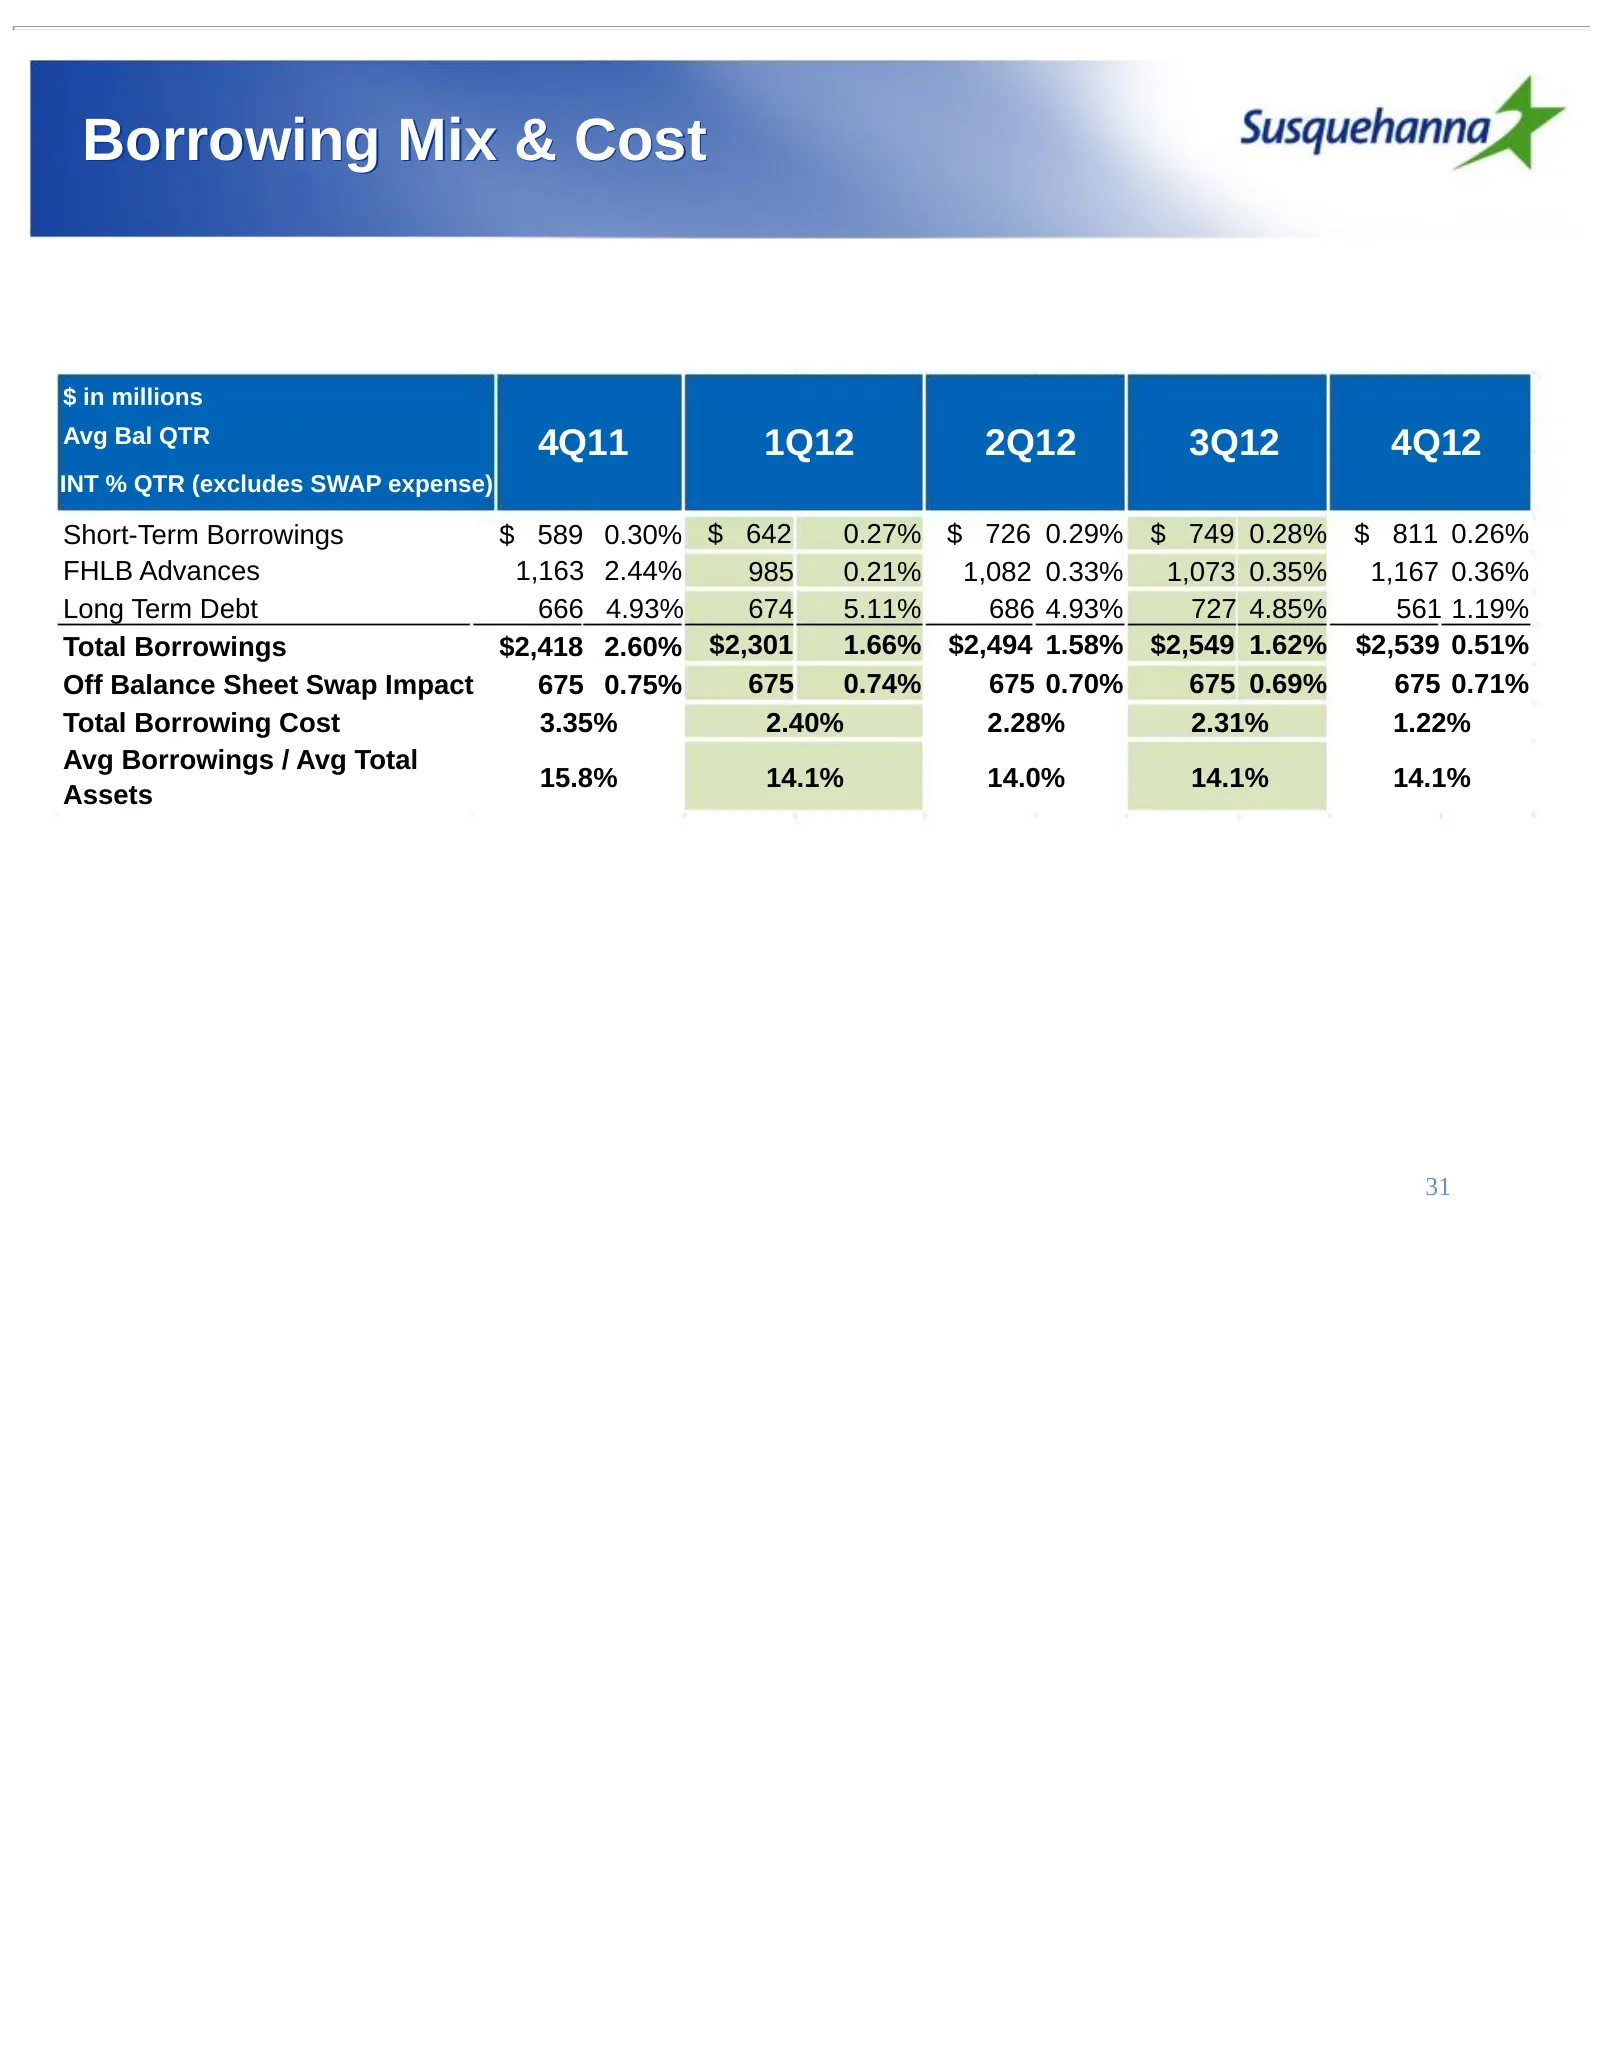
Borrowing Mix & Cost $ in millions Avg Bal QTR 4Q11 1Q12 2Q12 3Q12 4Q12 INT % QTR (excludes SWAP expense) Short-Term Borrowings $ 589 0.30% $ 642 0.27% $ 726 0.29% $ 749 0.28% $ 811 0.26% FHLB Advances 1,163 2.44% 985 0.21% 1,082 0.33% 1,073 0.35% 1,167 0.36% Long Term Debt 666 4.93% 674 5.11% 686 4
Slide 32: Quarterly Fee Revenue
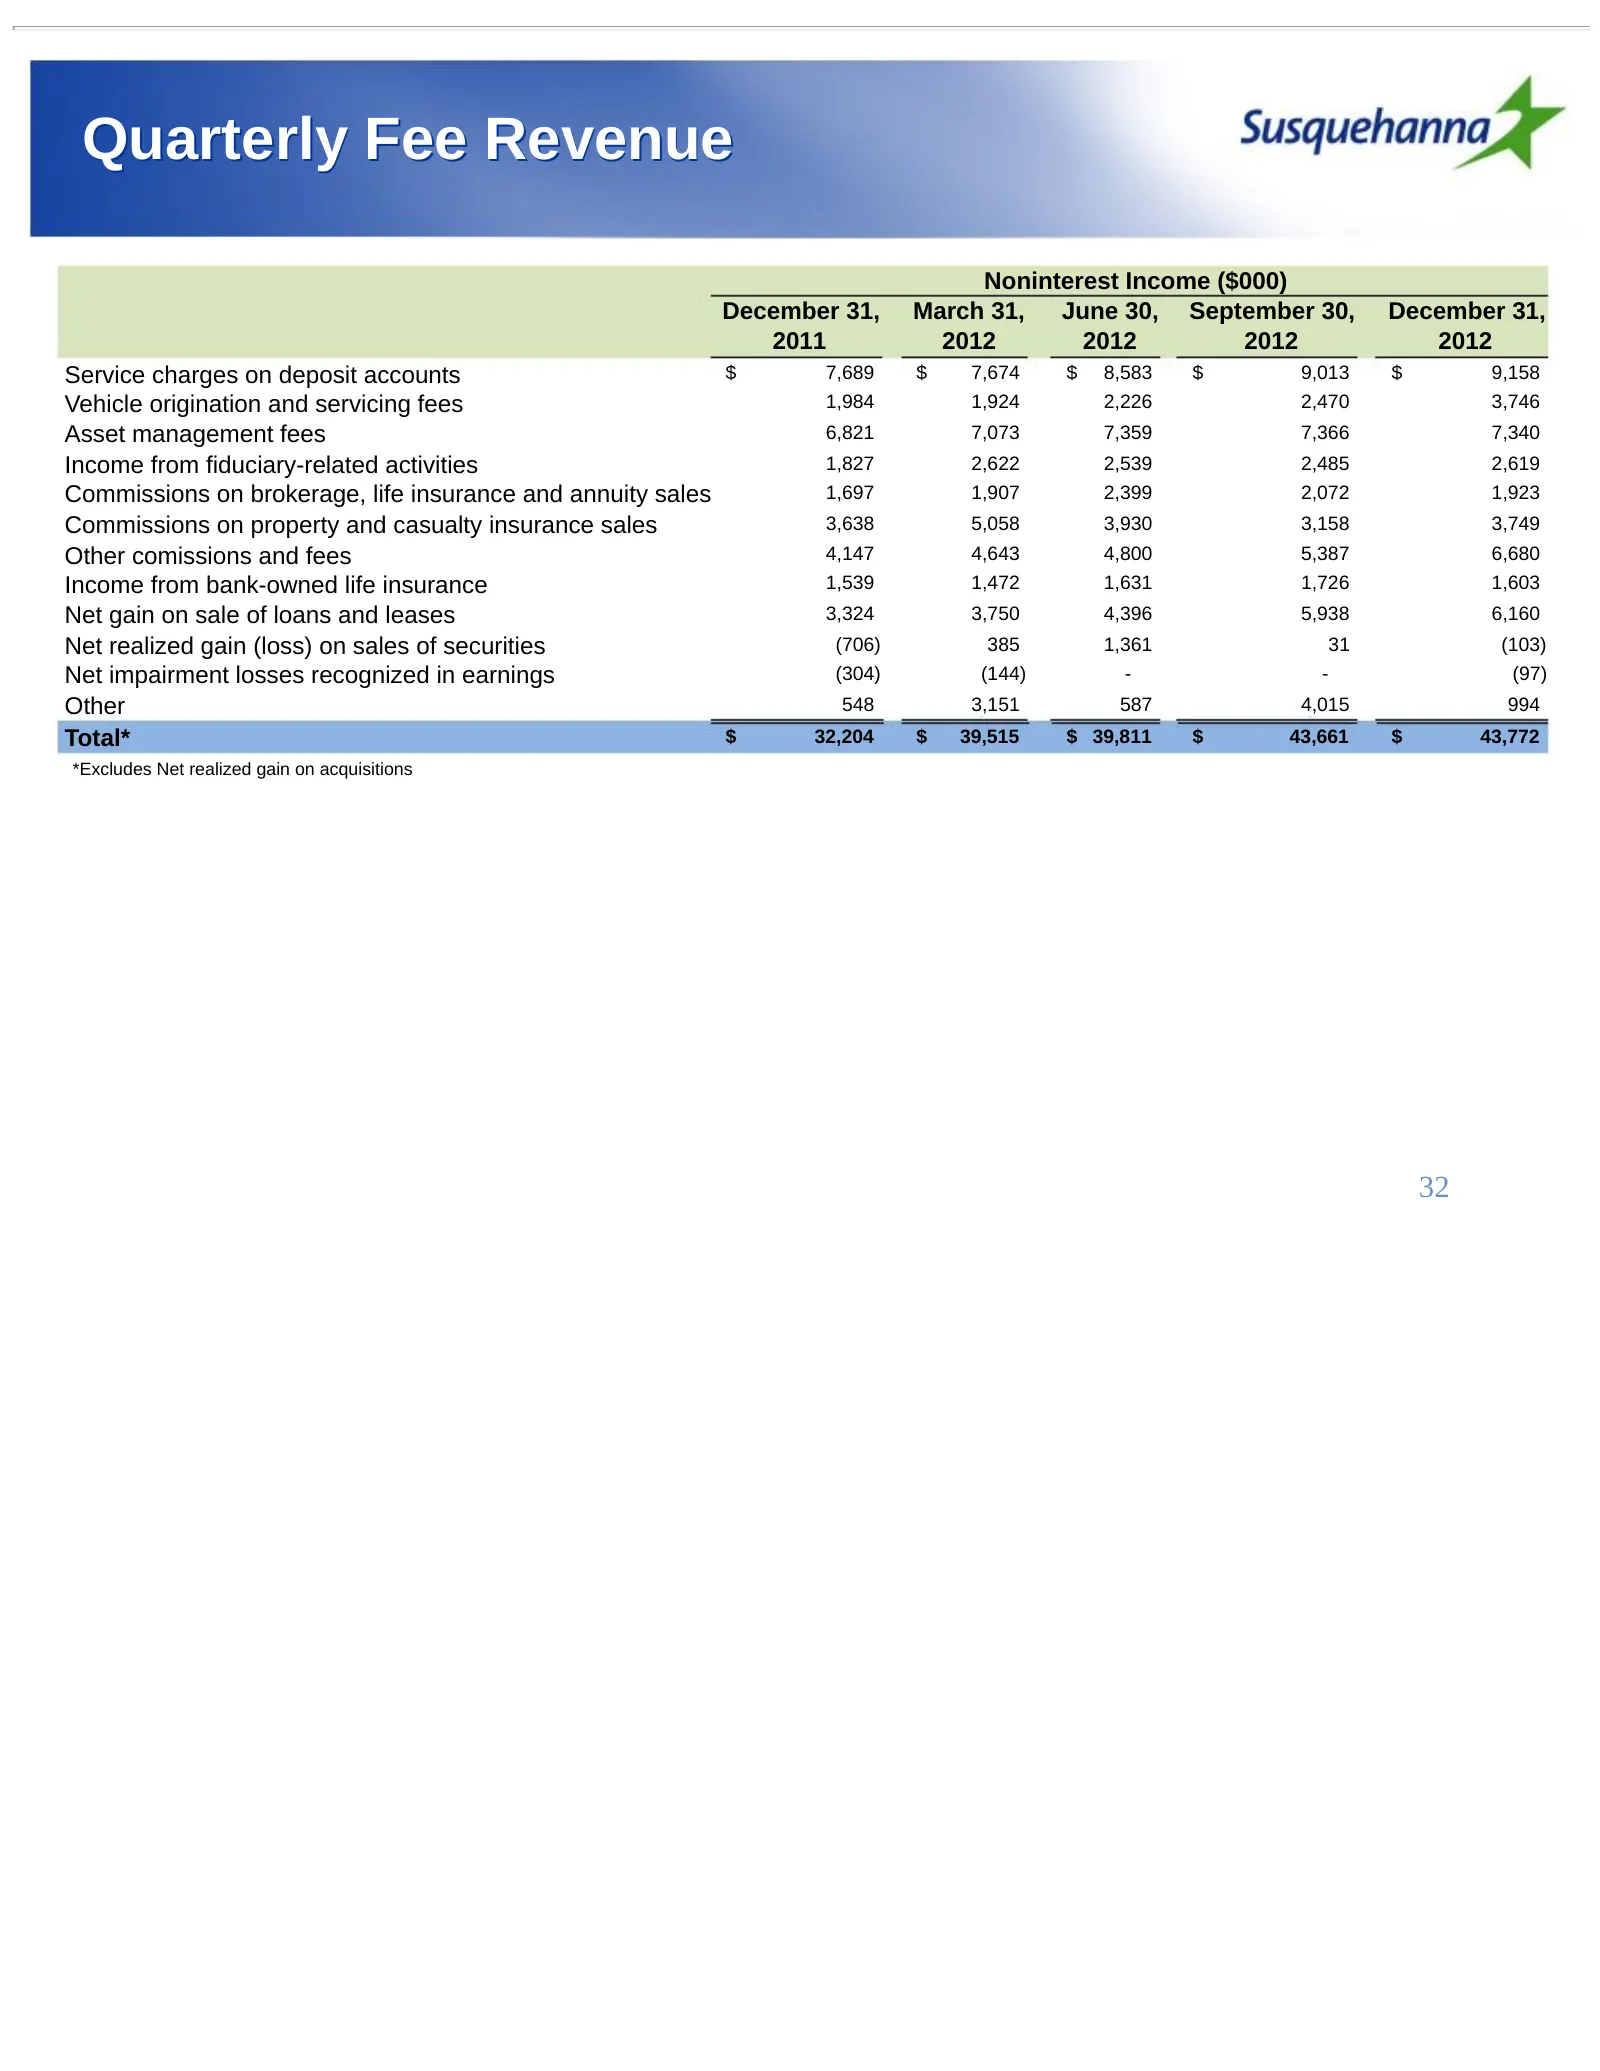
Quarterly Fee Revenue Noninterest Income ($000) December 31, March 31, June 30, September 30, December 31, 2011 2012 2012 2012 2012 Service charges on deposit accounts $ 7,689 $ 7,674 $ 8,583 $ 9,013 $ 9,158 Vehicle origination and servicing fees 1,984 1,924 2,226 2,470 3,746 Asset management fees 6
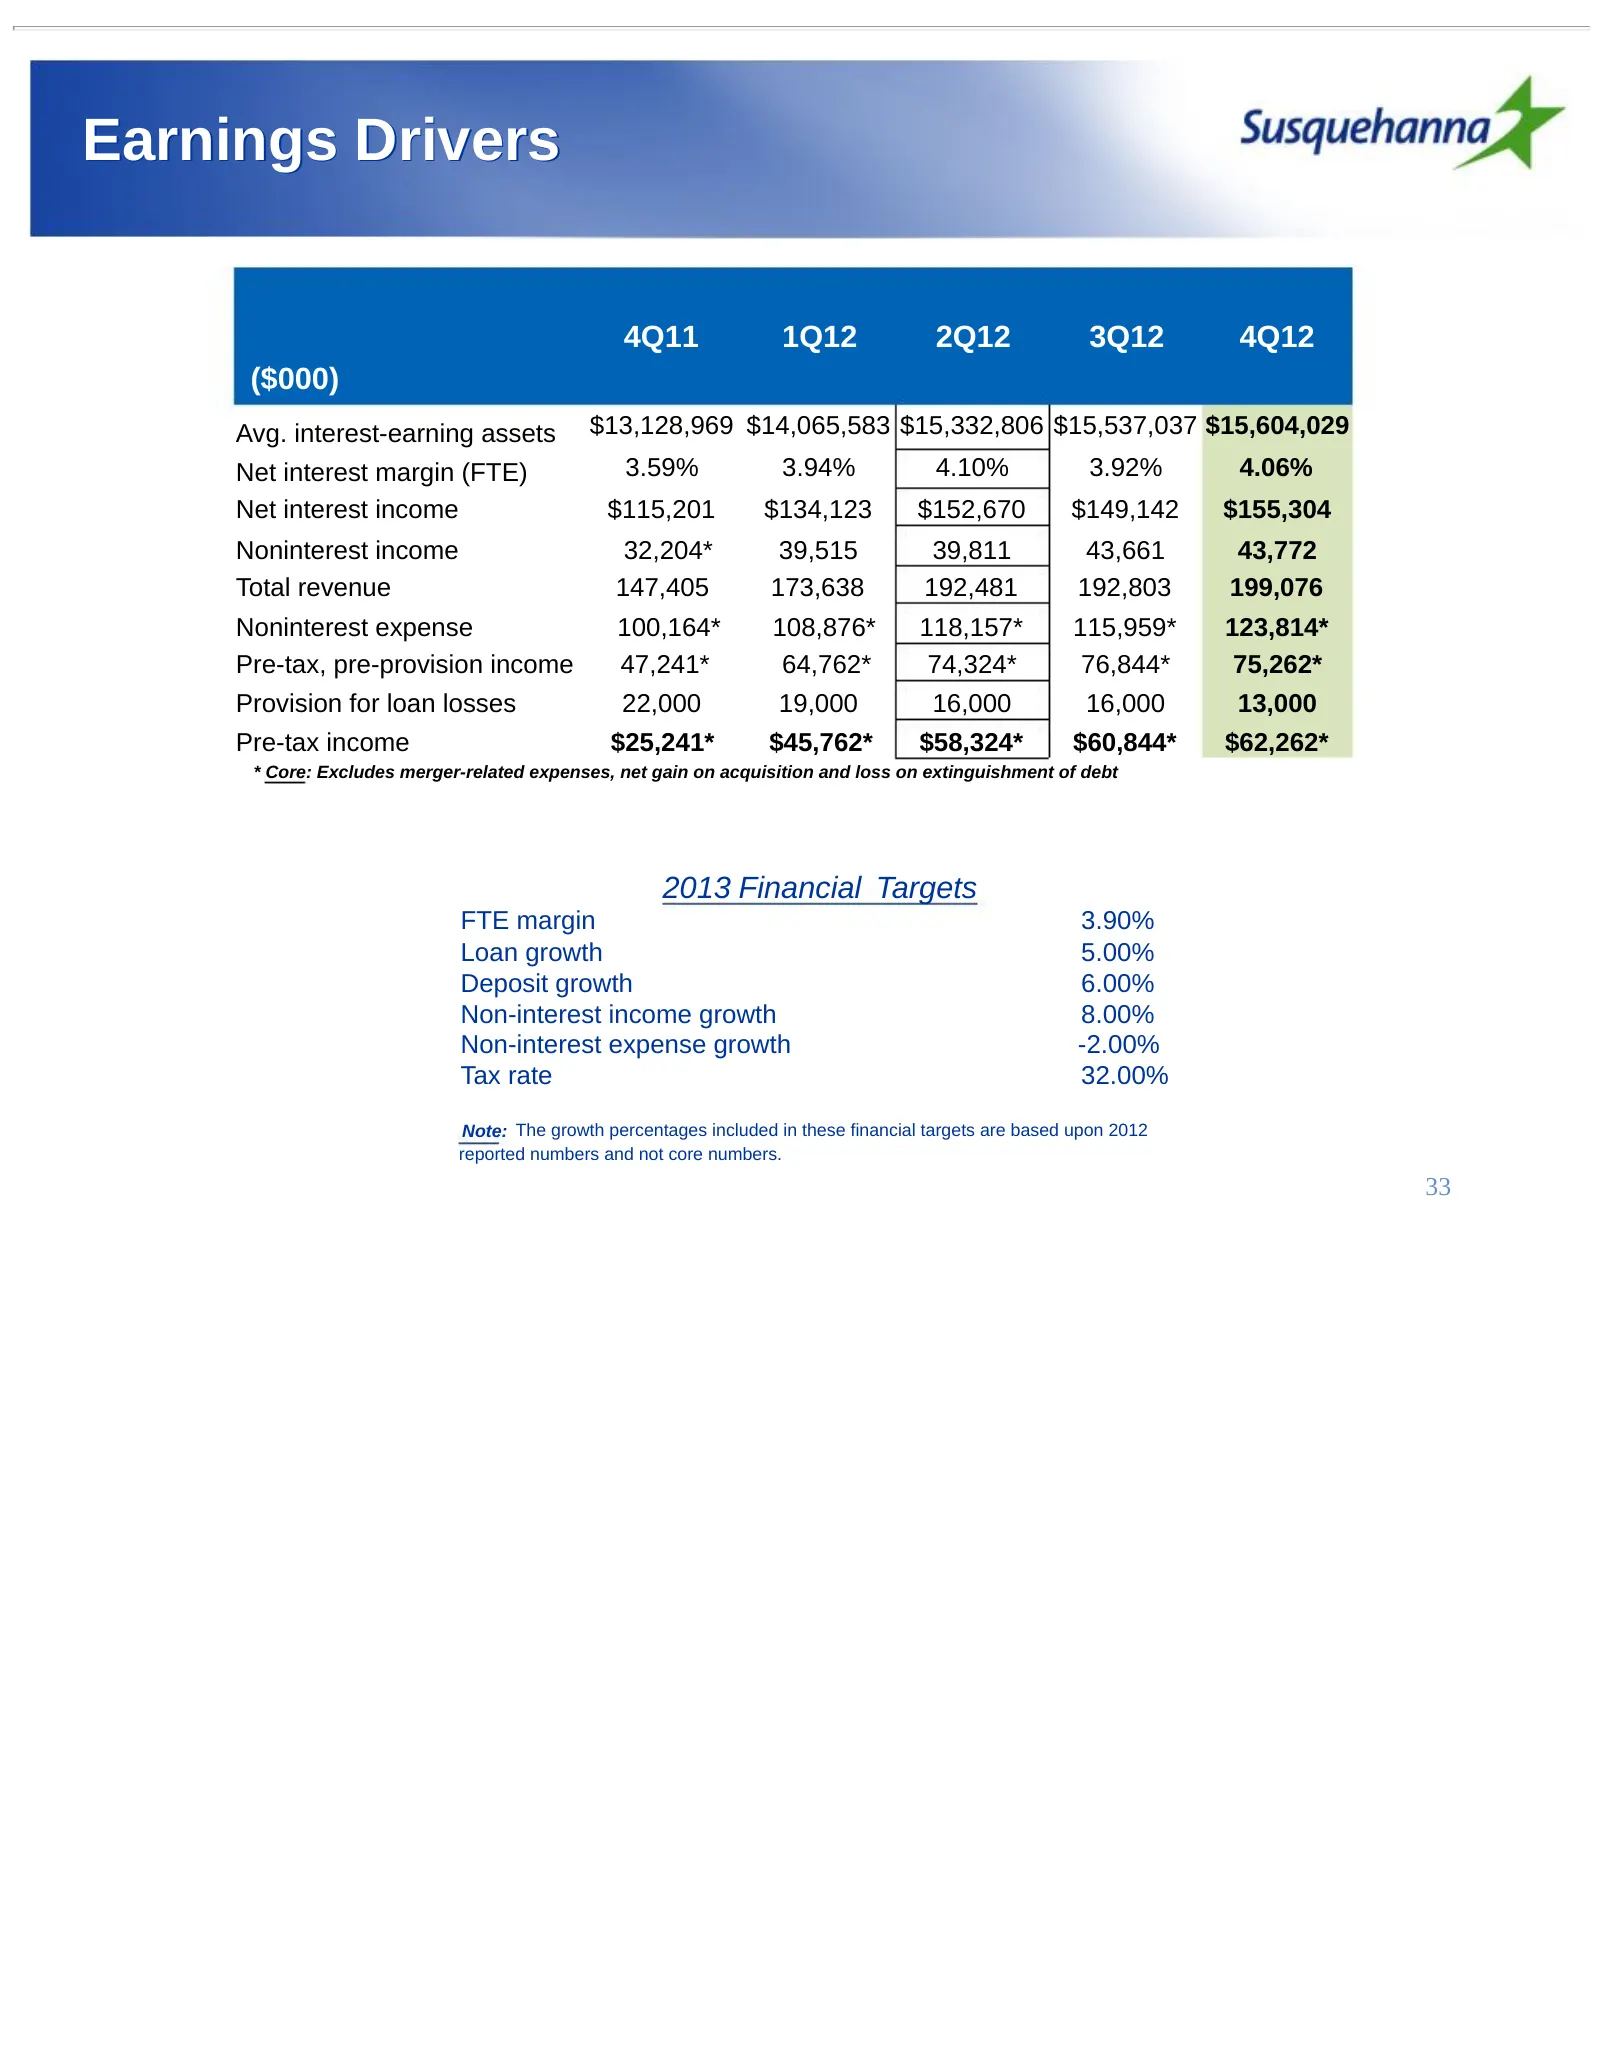
Slide 33: Earnings Drivers
Earnings Drivers 4Q11 1Q12 2Q12 3Q12 4Q12 ($000) Avg. interest-earning assets $13,128,969 $14,065,583 $15,332,806 $15,537,037 $15,604,029 Net interest margin (FTE) 3.59% 3.94% 4.10% 3.92% 4.06% Net interest income $115,201 $134,123 $152,670 $149,142 $155,304 Noninterest income 32,204* 39,515 39,811
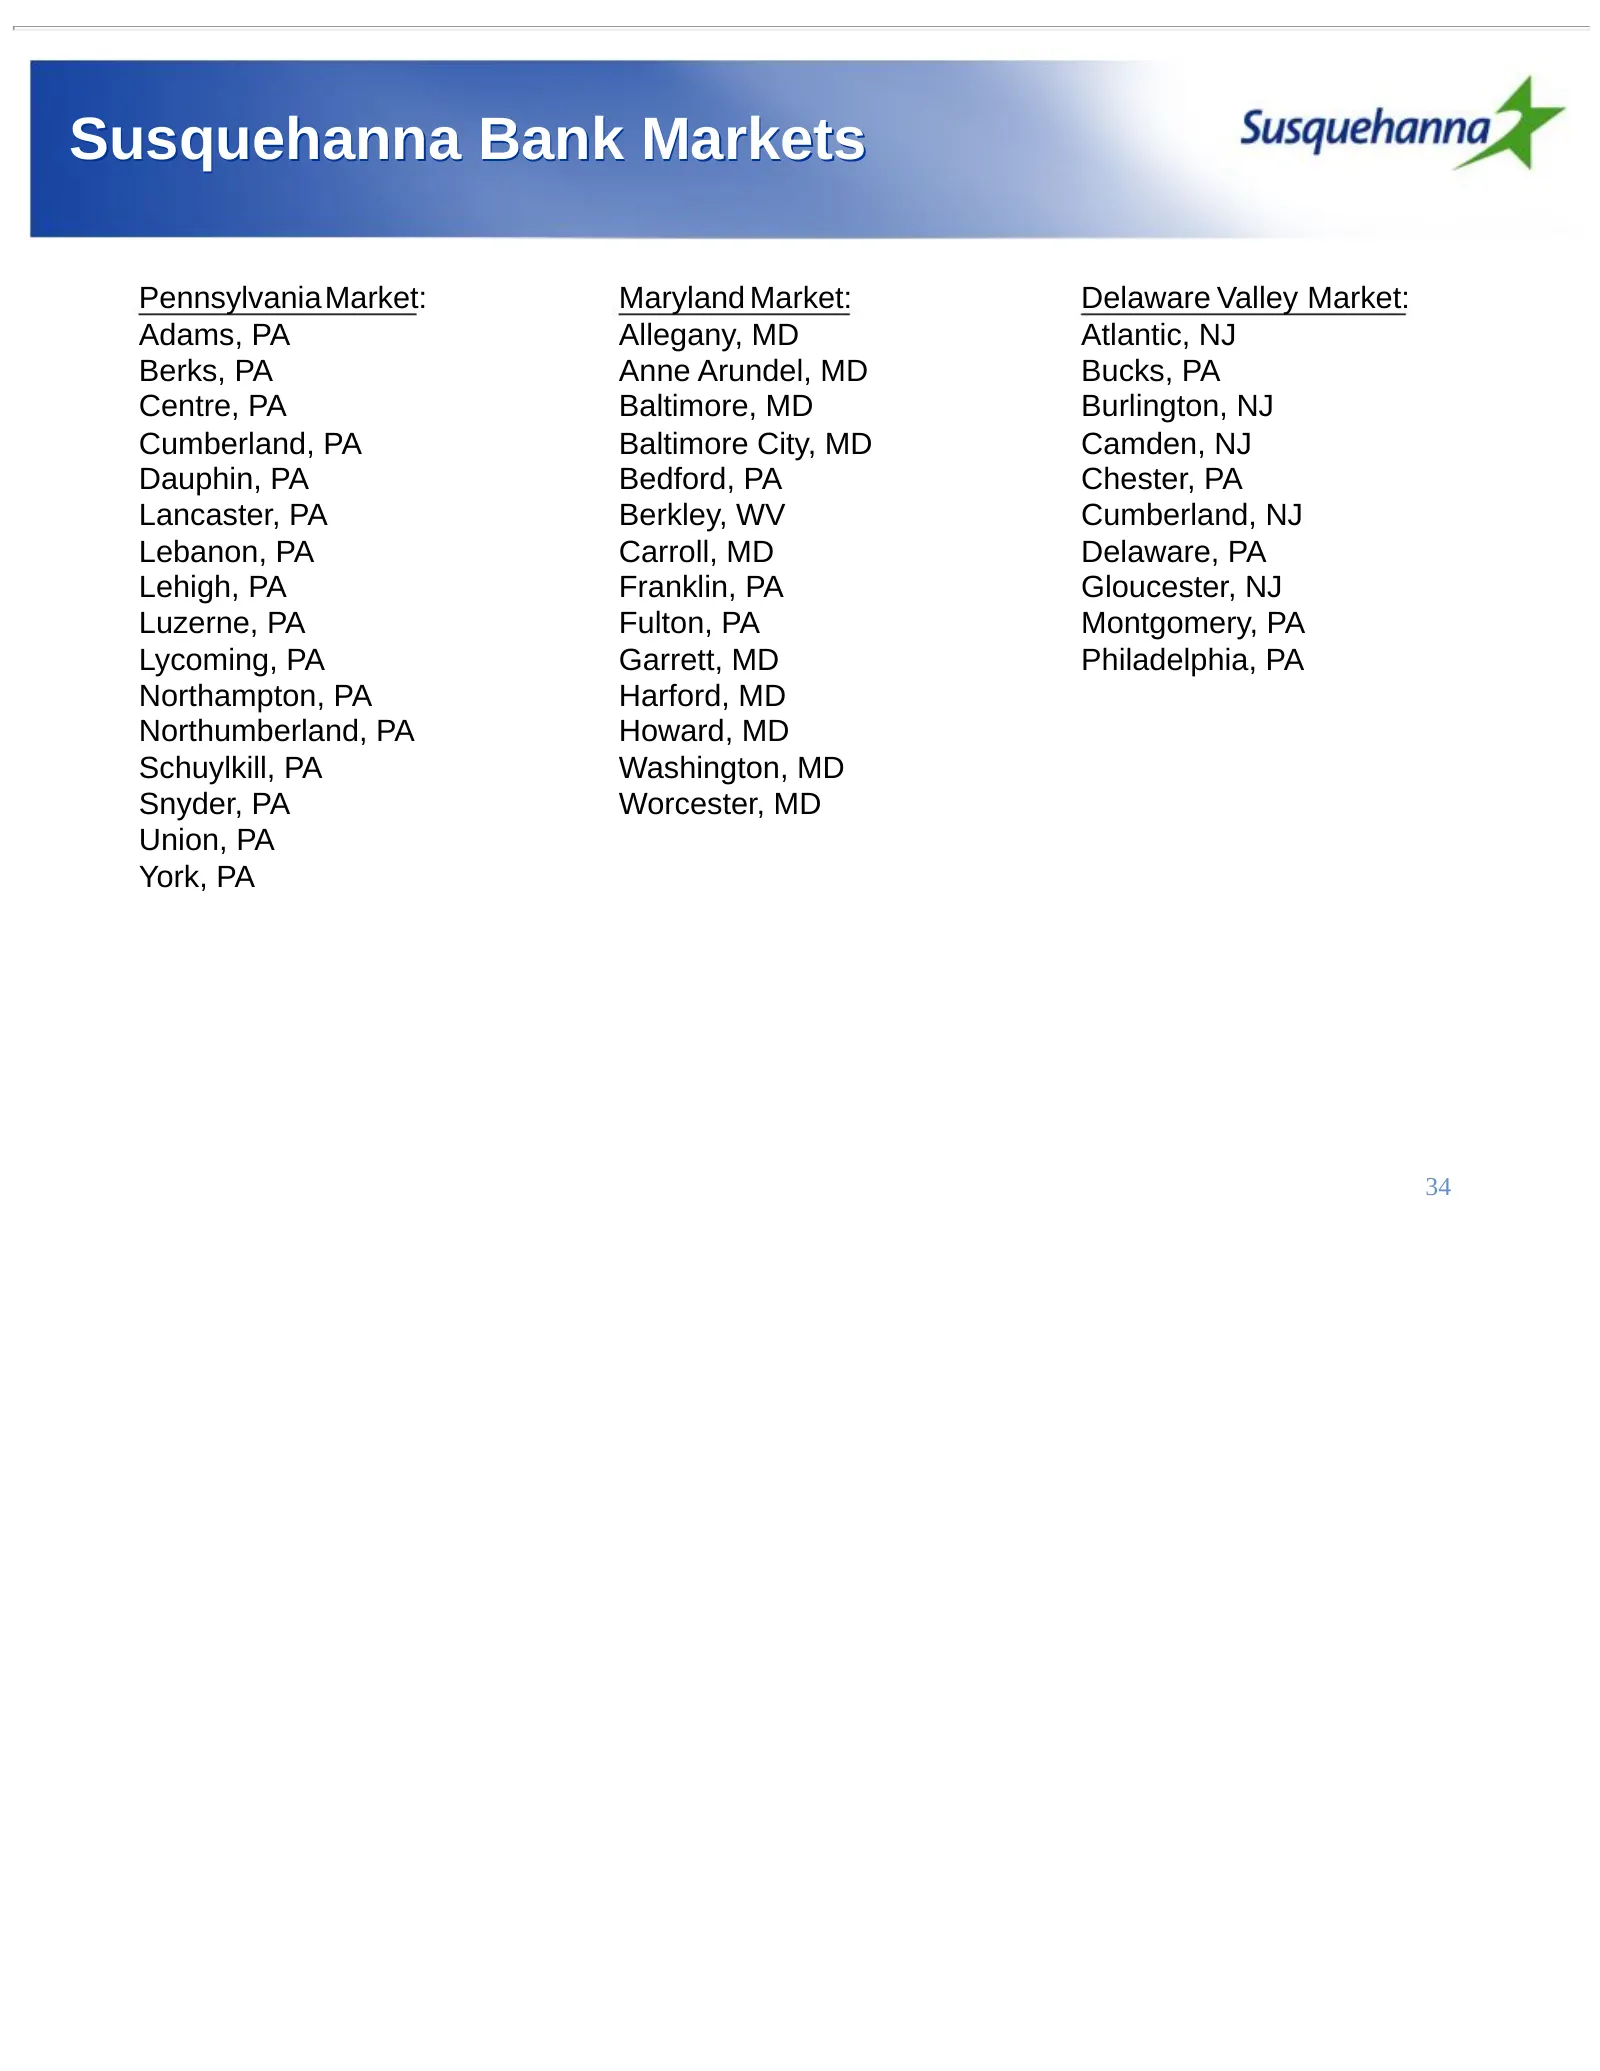
Slide 34: Susquehanna Bank Markets
Susquehanna Bank Markets Pennsylvania Market: Maryland Market: Delaware Valley Market: Adams, PA Allegany, MD Atlantic, NJ Berks, PA Anne Arundel, MD Bucks, PA Centre, PA Baltimore, MD Burlington, NJ Cumberland, PA Baltimore City, MD Camden, NJ Dauphin, PA Bedford, PA Chester, PA Lancaster, PA Berkl
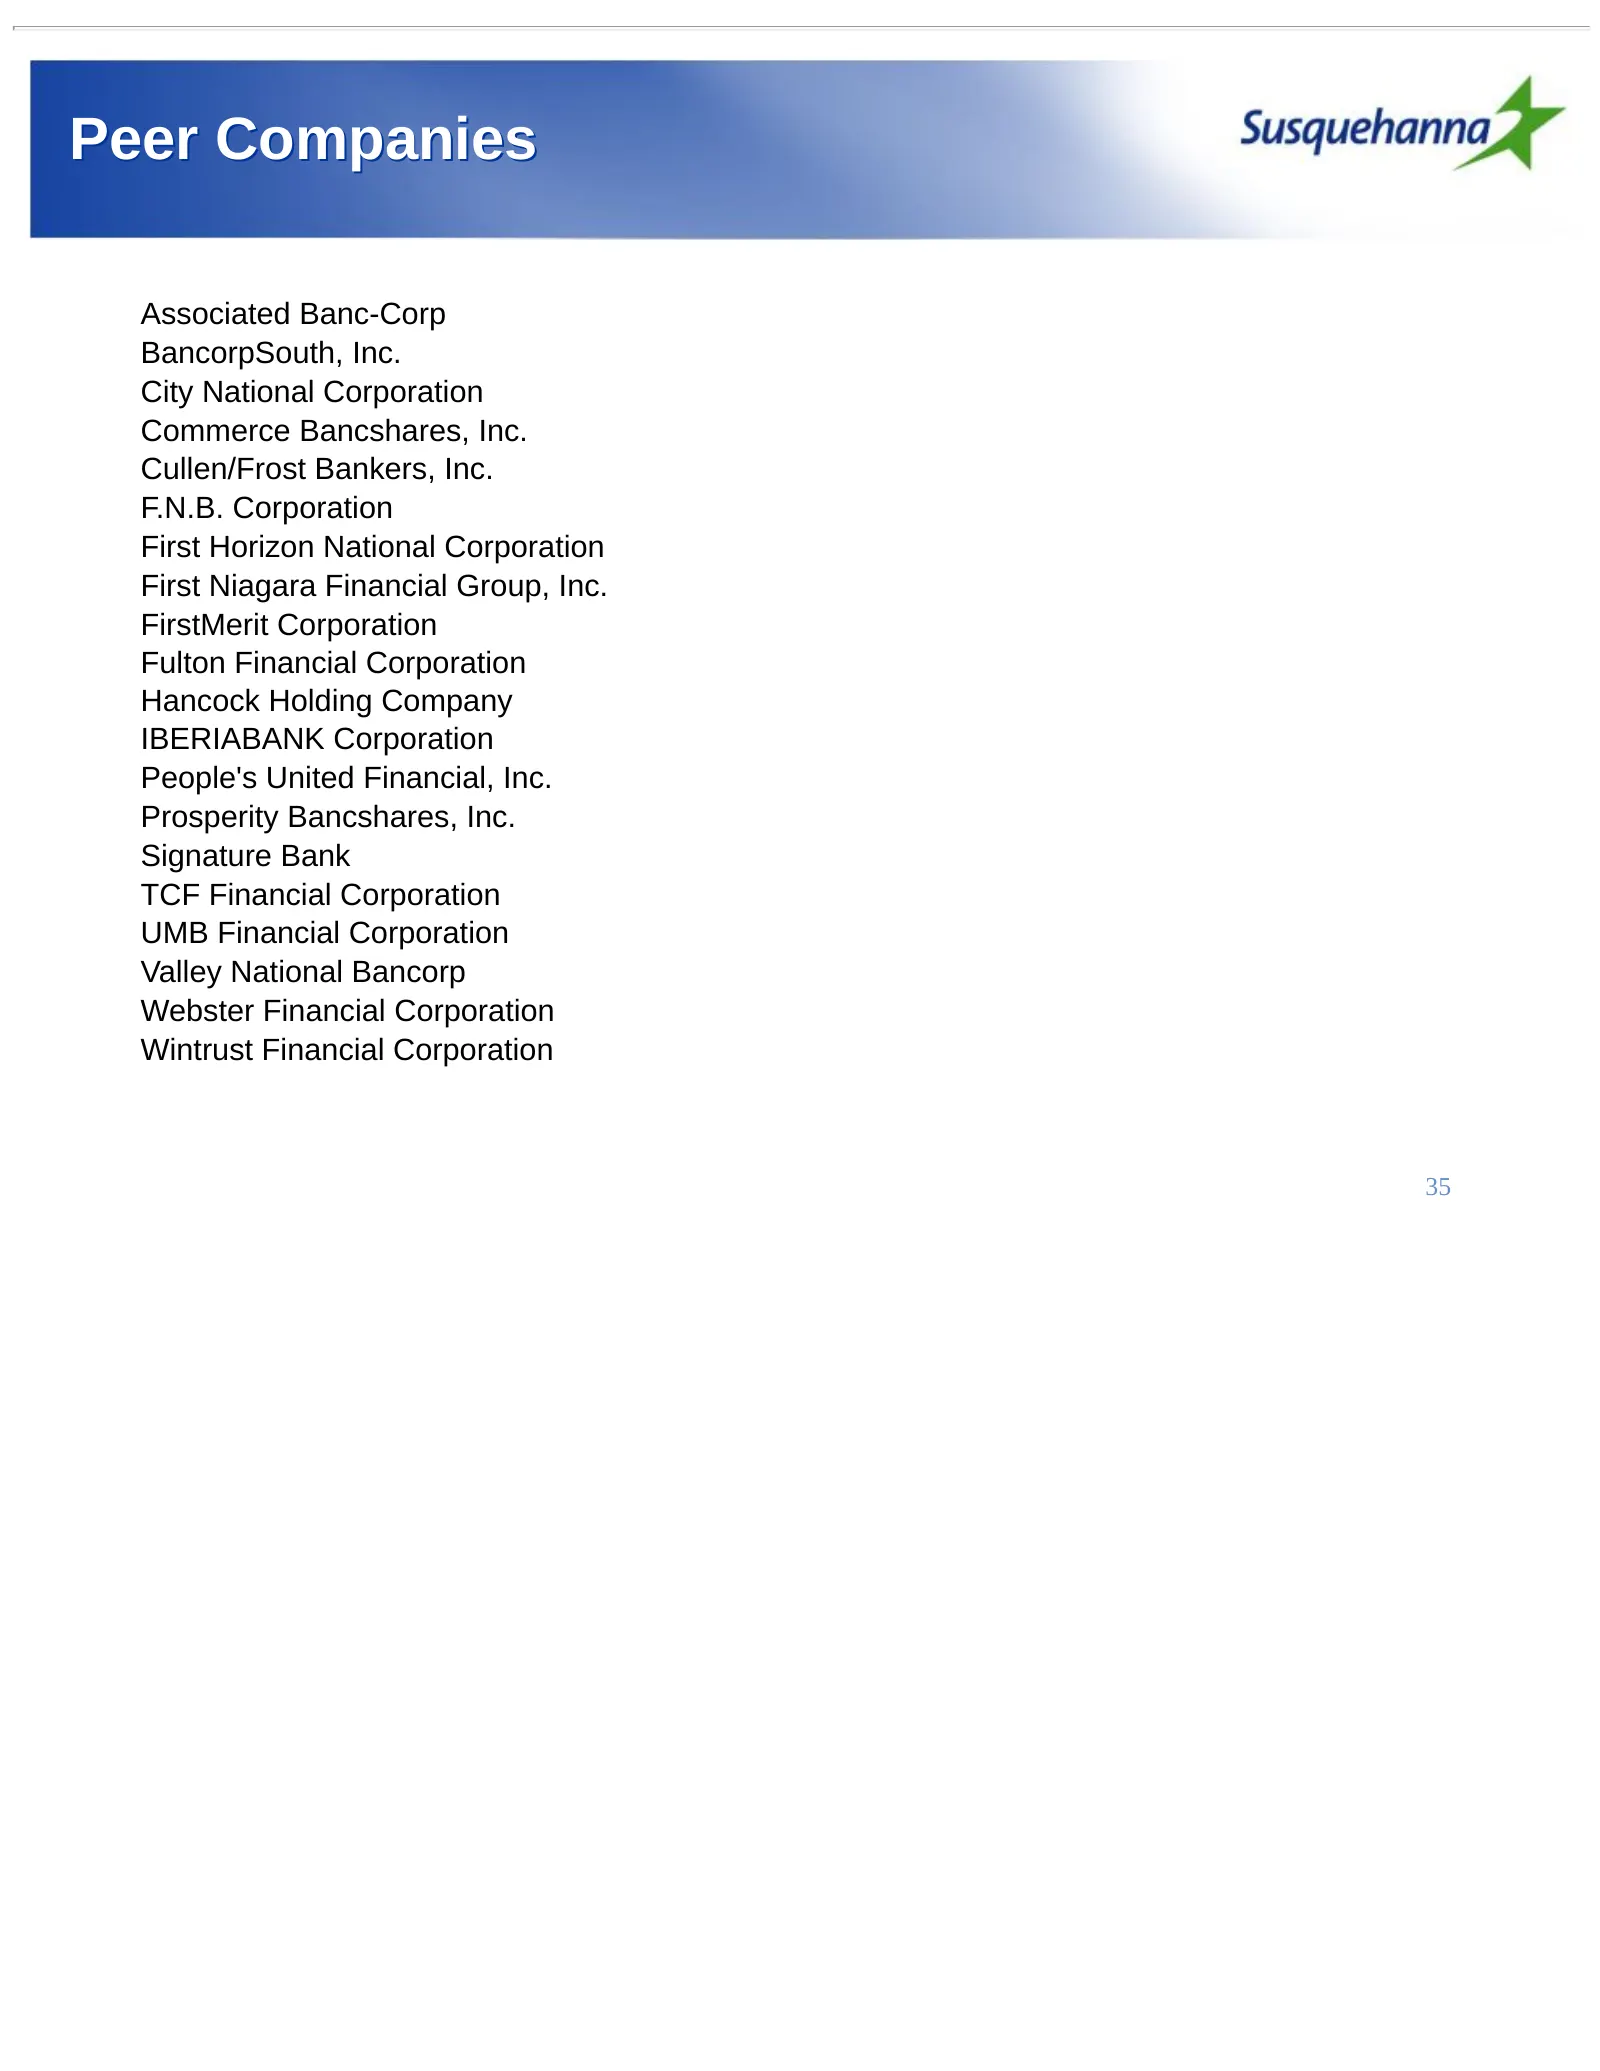
Slide 35: Peer Companies
Peer Companies Associated Banc-Corp BancorpSouth, Inc. City National Corporation Commerce Bancshares, Inc. Cullen/Frost Bankers, Inc. F.N.B. Corporation First Horizon National Corporation First Niagara Financial Group, Inc. FirstMerit Corporation Fulton Financial Corporation Hancock Holding Company
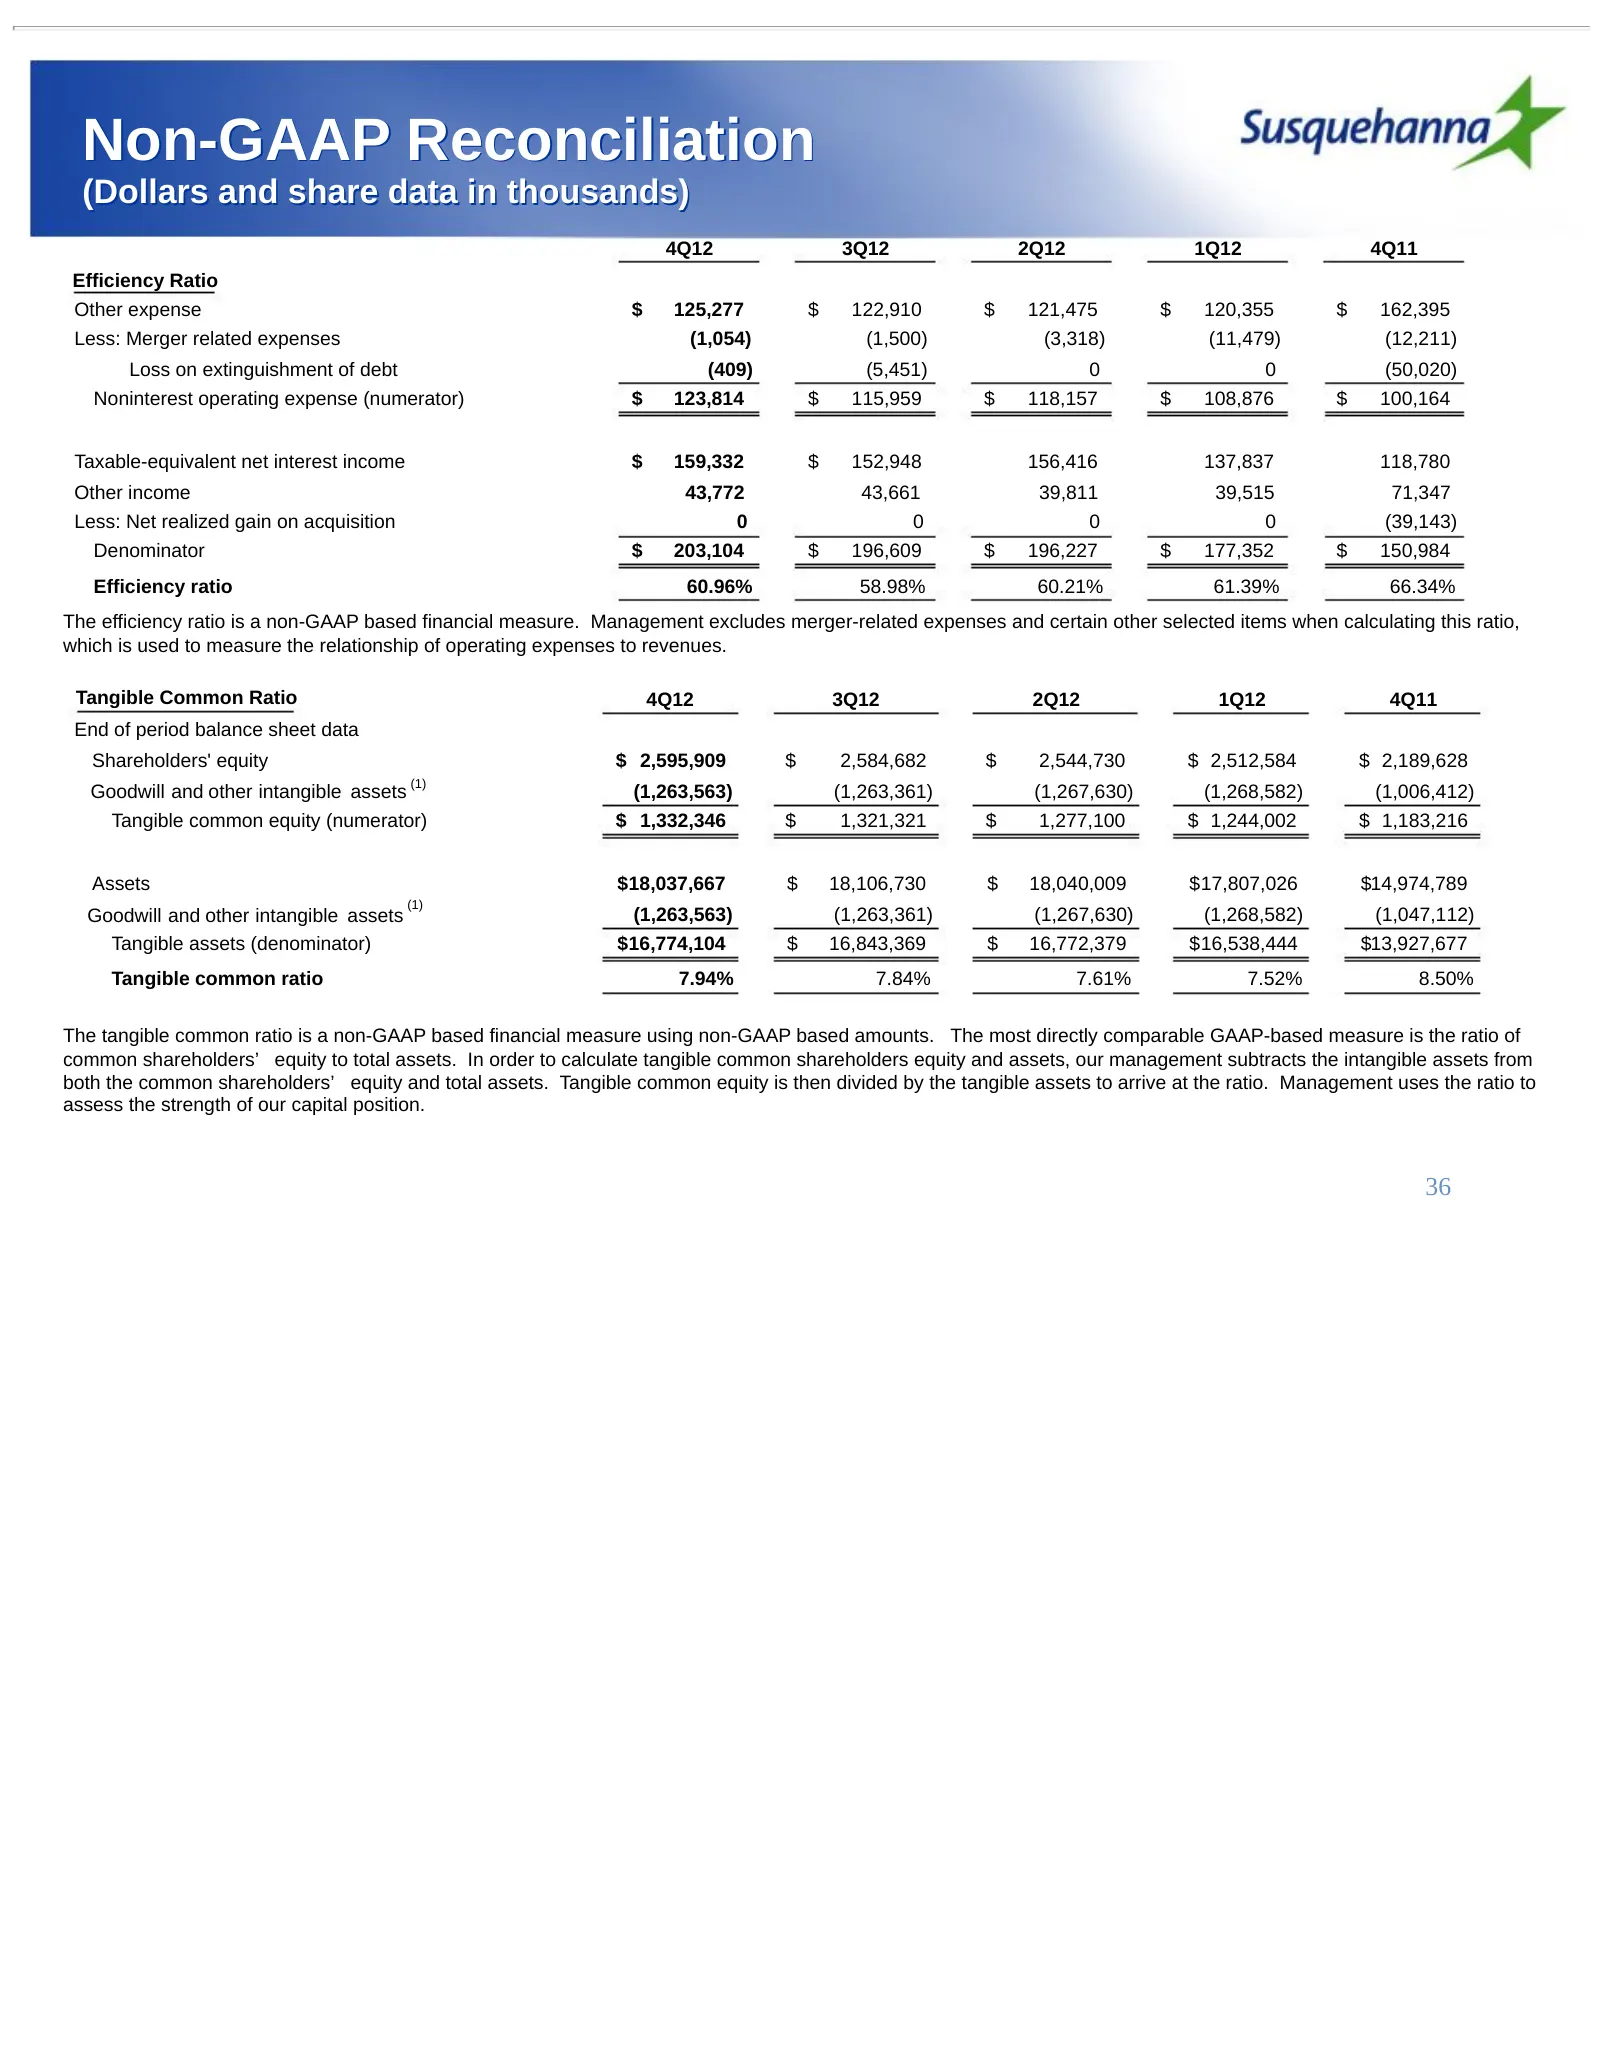
Slide 36: Non-GAAP Reconciliation
Non-GAAP Reconciliation (Dollars and share data in thousands) 4Q12 3Q12 2Q12 1Q12 4Q11 Efficiency Ratio Other expense $ 125,277 $ 122,910 $ 121,475 $ 120,355 $ 162,395 Less: Merger related expenses (1,054) (1,500) (3,318) (11,479) (12,211) Loss on extinguishment of debt (409) (5,451) 0 0 (50,020) No
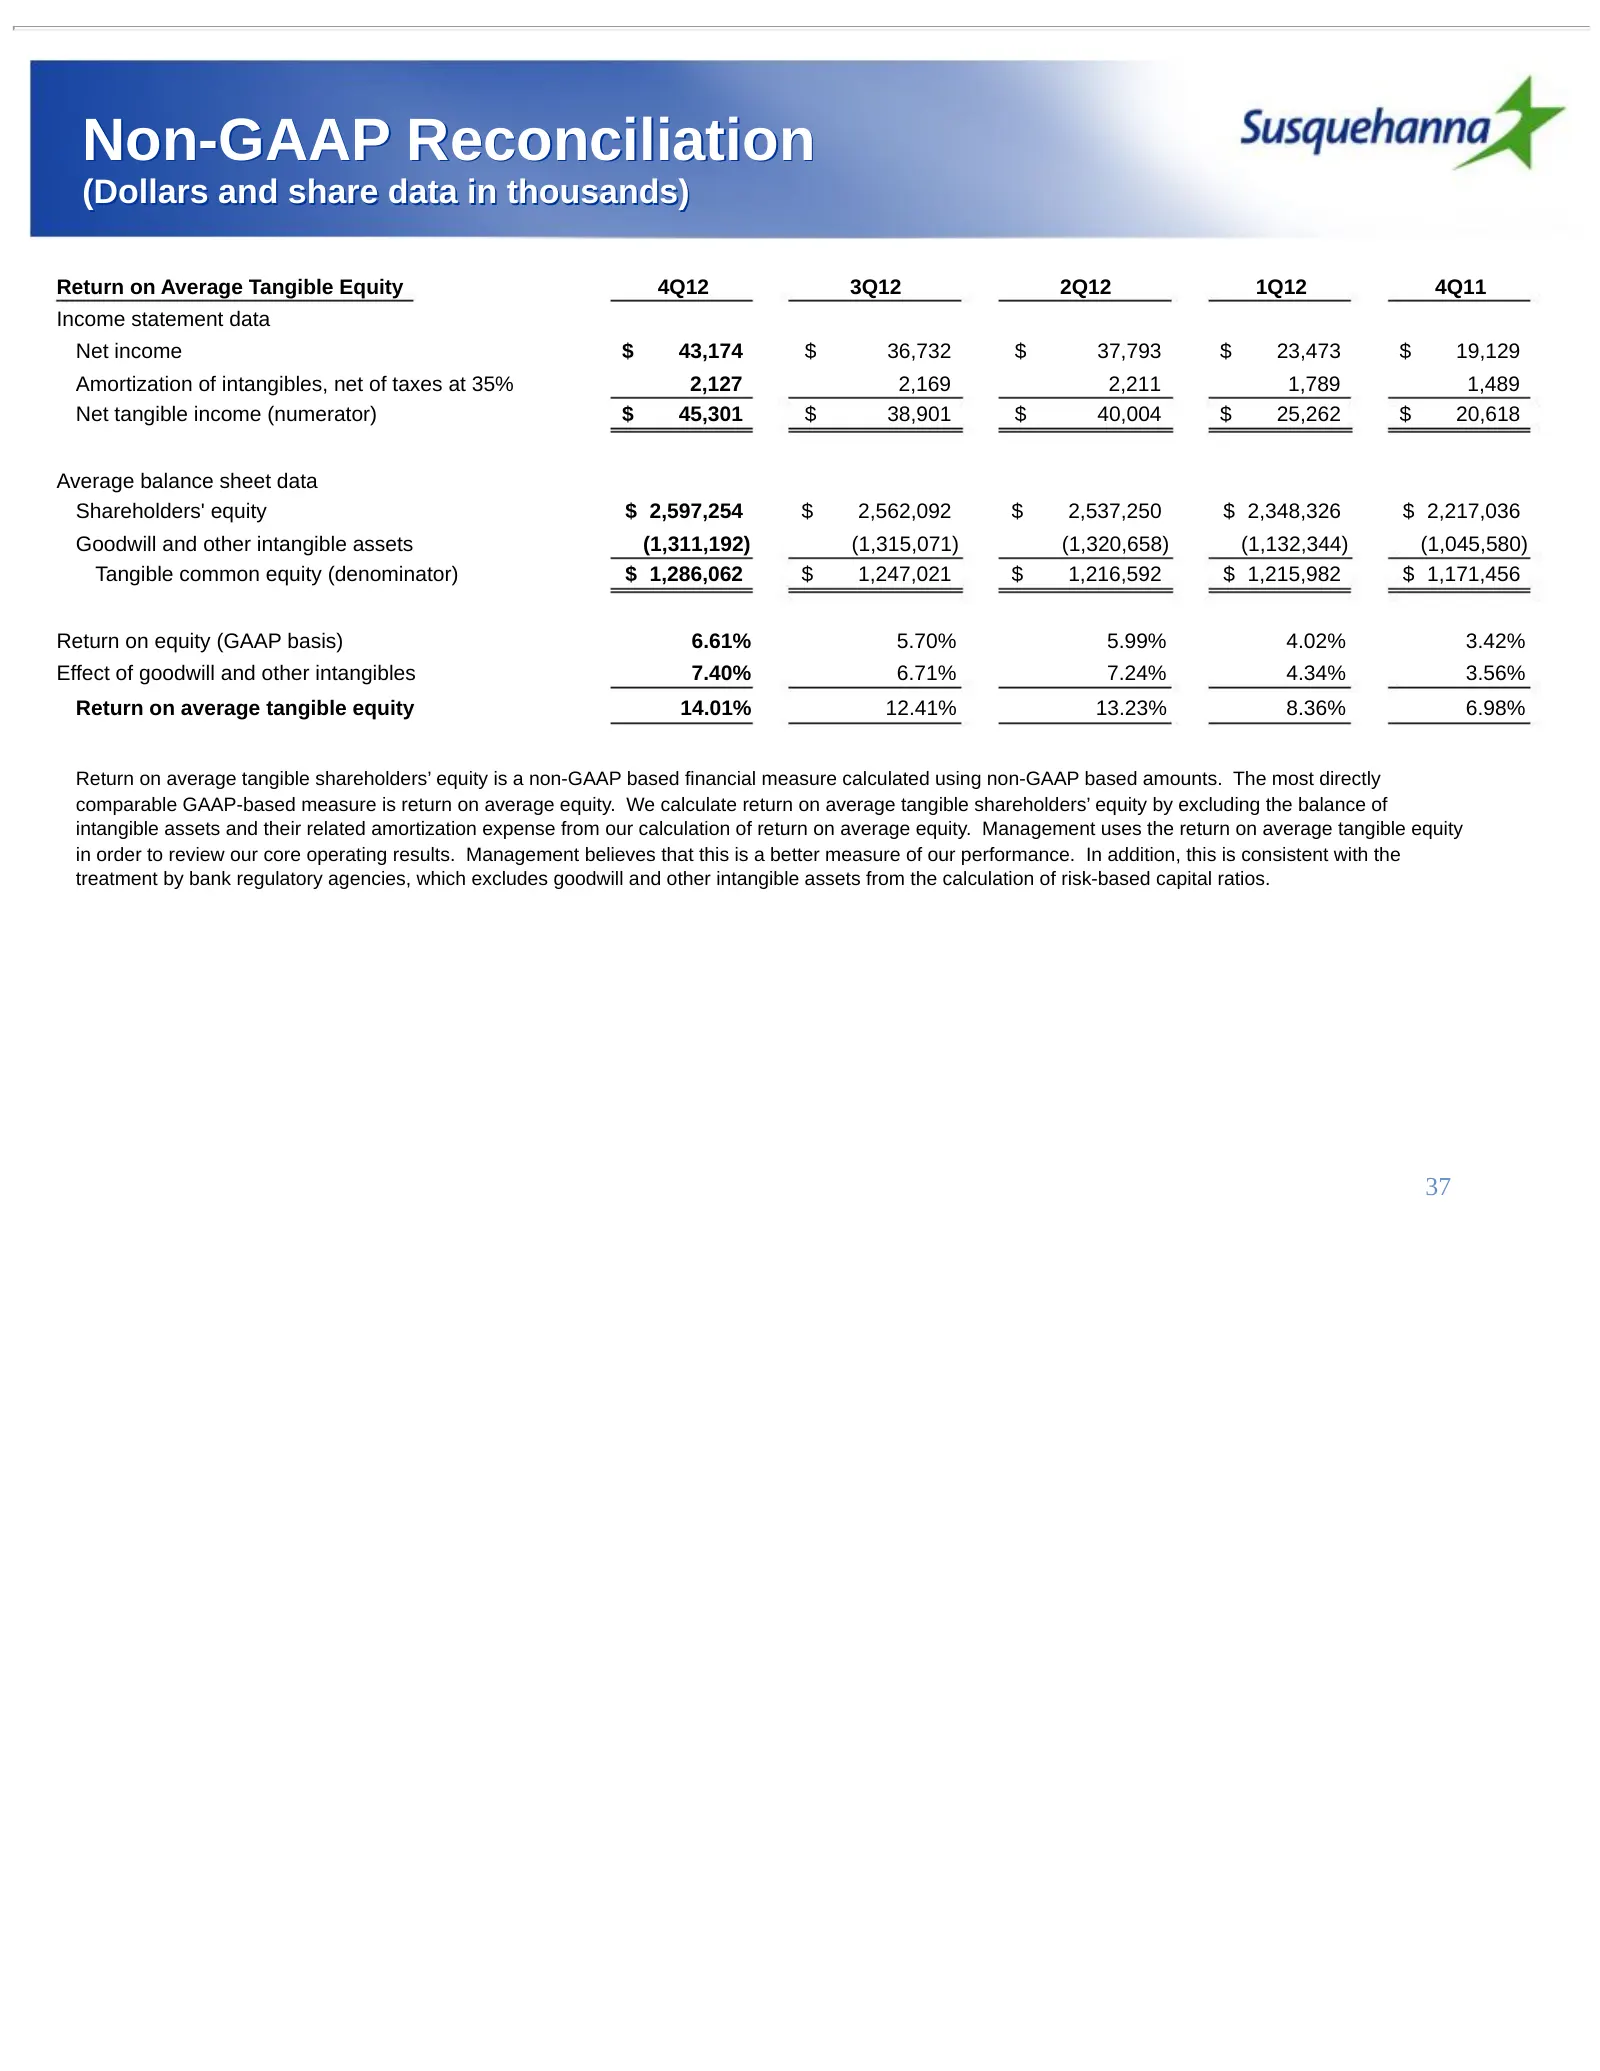
Slide 37: Non-GAAP Reconciliation
Non-GAAP Reconciliation (Dollars and share data in thousands) Return on Average Tangible Equity 4Q12 3Q12 2Q12 1Q12 4Q11 Income statement data Net income $ 43,174 $ 36,732 $ 37,793 $ 23,473 $ 19,129 Amortization of intangibles, net of taxes at 35% 2,127 2,169 2,211 1,789 1,489 Net tangible income (n
Source: SEC EDGAR · 8-K filed Feb 6, 2013
More decks from Susquehanna Bancshares Inc
 Investor Presentation (December 2014)51 slides · Dec 3, 2014
 Merger or Acquisition (November 2014)28 slides · Nov 17, 2014
 Merger or Acquisition (November 2014)13 slides · Nov 12, 2014
 Q2 2014 Earnings Presentation46 slides · Aug 11, 2014
 Investor Presentation (May 2014)44 slides · May 5, 2014
 Shareholder Meeting (May 2014)35 slides · May 2, 2014