Texas Industries — First Dallas Securities Investment Forum August 2006
25 slides from Texas Industries's conference presentation, Aug 31, 2006
Slide 1: First Dallas Securities Investment Forum
FIRST DALLAS SECURITIES INVESTMENT FORUM AUGUST 2006
Slide 2: Forward-Looking Statement
FORWARD-LOOKING STATEMENT Certain statements contained in this presentation are "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to risks, uncertainties and other factors, which could cause actual results to differ m
Slide 3: TXI — A Building Materials Company
TXI— A BUILDING MATERIALS COMPANY «Cement, Aggregate and Concrete Used in all types of construction «Cement accounts for approximately 75% of Earnings
Slide 4: TXI — Cement Plant
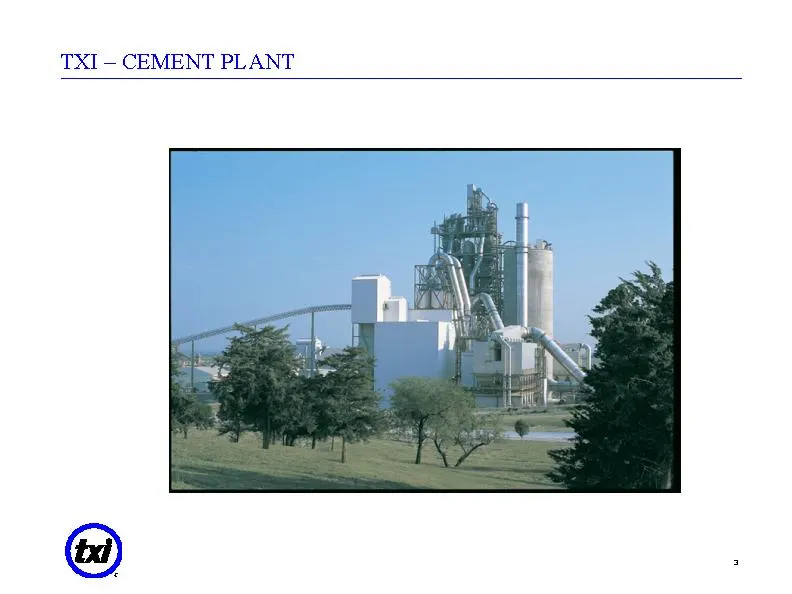
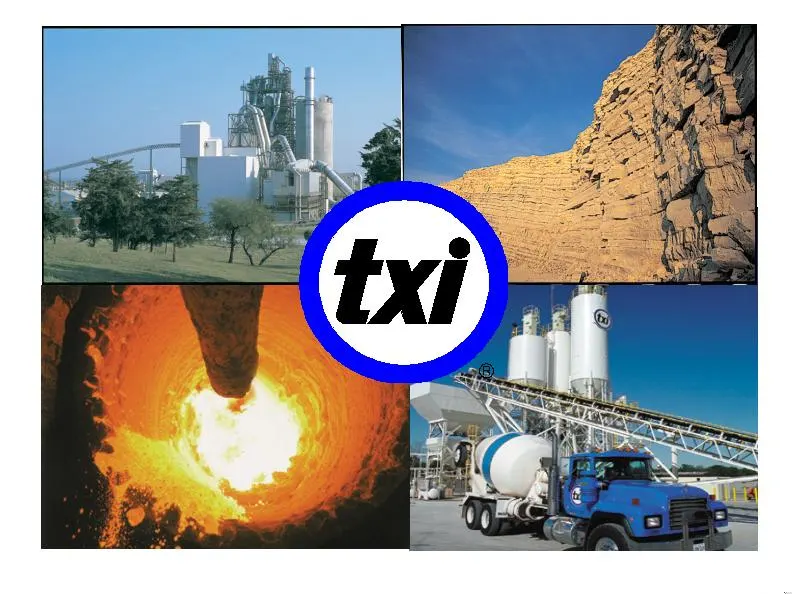
TXI — CEMENT PLANT
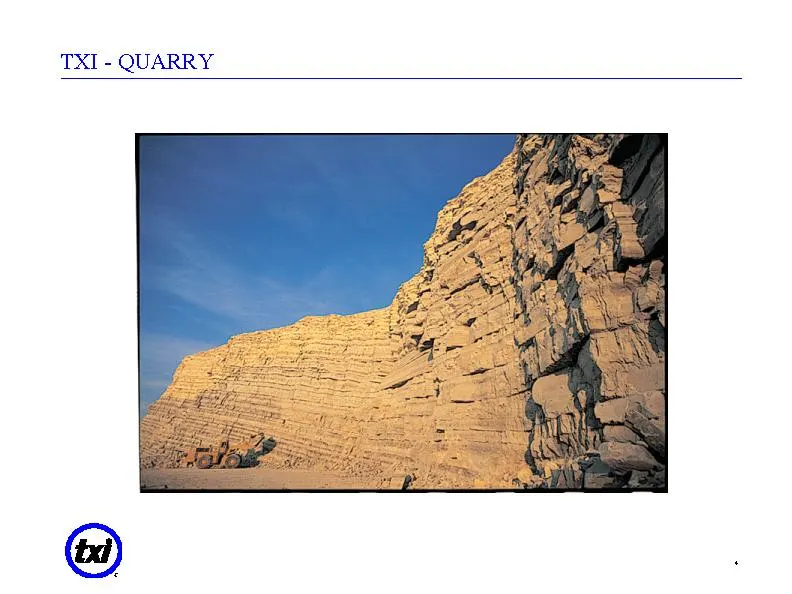
Slide 5: TXI - Quarry
TXI - QUARRY
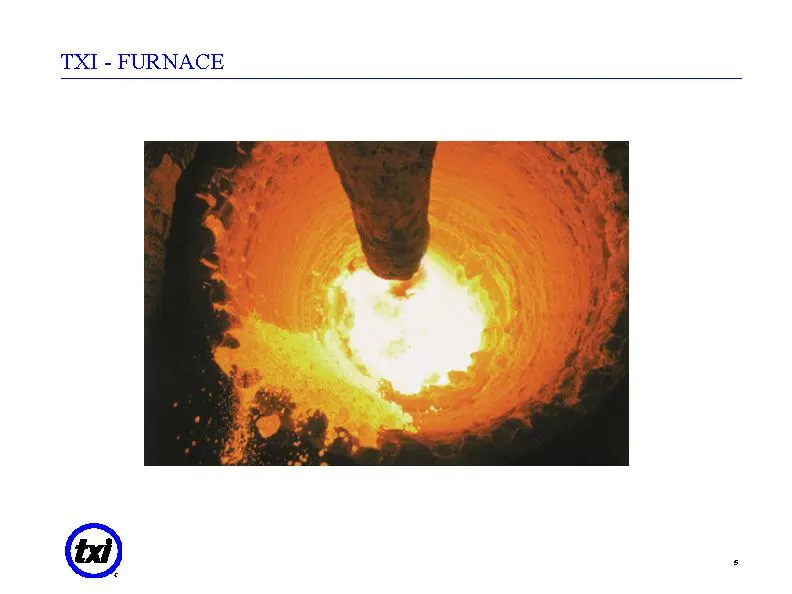
Slide 6: TXI - Furnace
TXI - FURNACE
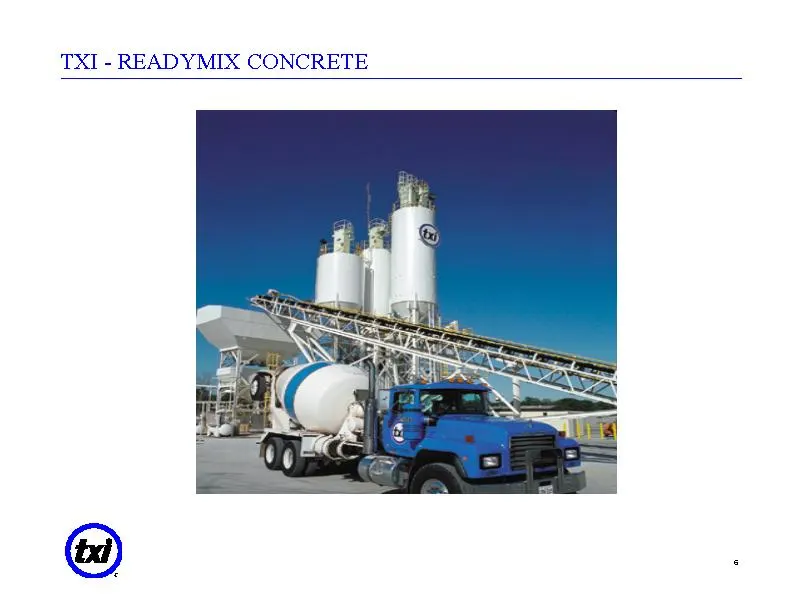
Slide 7: TXI - Readymix Concrete
TXI - READYMIX CONCRETE
Slide 8: Primary Earnings Drivers
PRIMARY EARNINGS DRIVERS ¢Significant Margin Expansion
Slide 9: Primary Earnings Drivers
PRIMARY EARNINGS DRIVERS Significant Margin Expansion Cement Capacity Expansion + From 6 milion tons per year to 7.6 million tons per year in4—5 years + Three Projects
Slide 10: TXI — In Summary
TXI—IN SUMMARY The U.S. cement industry is favorably structured Texas and California are attractive cement markets TXIis the largest cement supplier in Texas — and a low cast producer TXI's Califarnia cement plant project is underway Texas cement expansion projects will enhance competitive position
Slide 11: Cement Industry - Demand Drivers
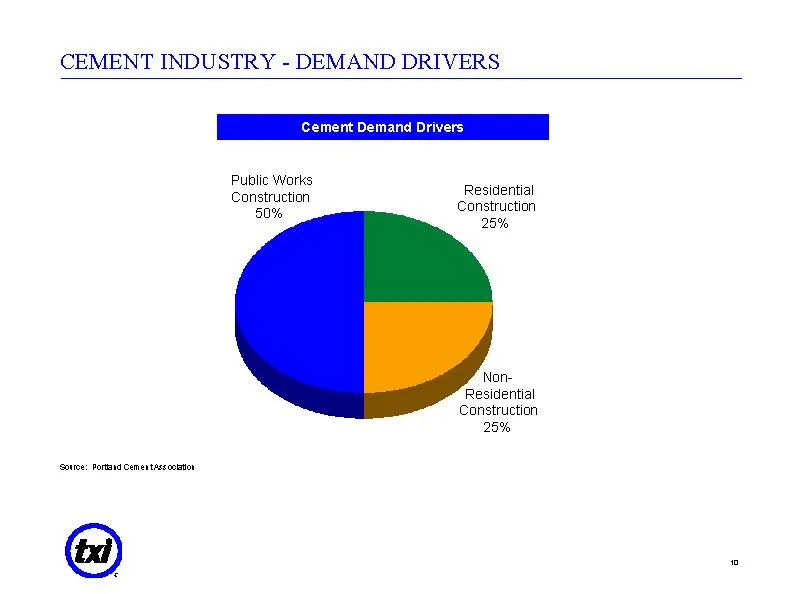
CEMENT INDUSTRY - DEMAND DRIVERS Cement Demand Drivers Public Works Construction 50% Residential Construction 25% Non- Residential Construction 25%
Slide 12: Favorable Industry Structure
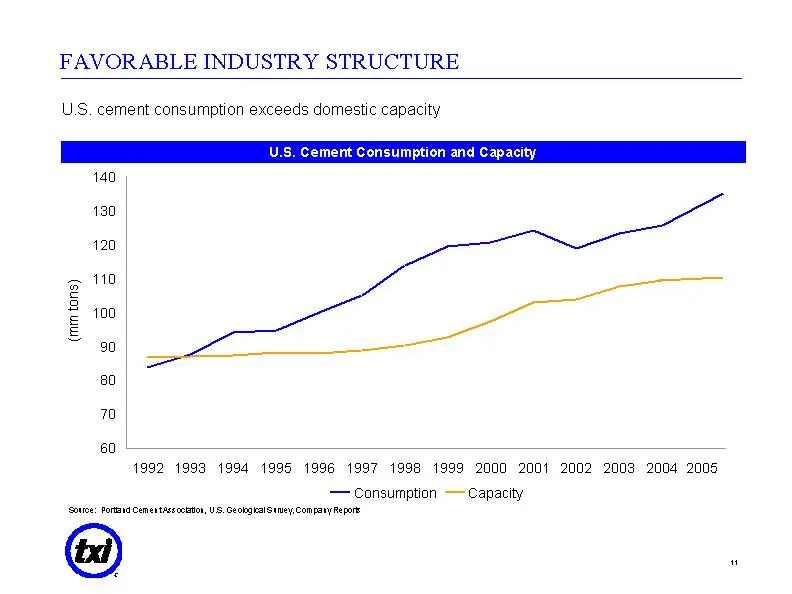
FAVORABLE INDUSTRY STRUCTURE U.S. cement consumption exceeds domestic capacity U.S. Cement Consumption and Capacity 140 130 120 110 100 (mm tons) 90 80 70 60 1992 1998 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 — Consumption — Capacity ‘ove: Portis Cemertas como, US, GeckgkalSuney.C
Slide 13: Favorable Industry Structure (continued)
FAVORABLE INDUSTRY STRUCTURE (continued) The Supply of Cement Is Constrained U.S. cement capacity and import terminals are largely owned or controlled by international producers @ High barriers to entry exist for new cement capacity
Slide 14: Favorable Industry Structure (continued)
FAVORABLE INDUSTRY STRUCTURE (continued) The Supply of Cement Is Constrained U.S. cement capacity and import terminals are largely owned or controlled by international producers @ High barriers to entry exist for new cement capacity Cement Demand Should Be Sustainable Residential construction still
Slide 15: Strong Positions in Attractive Markets
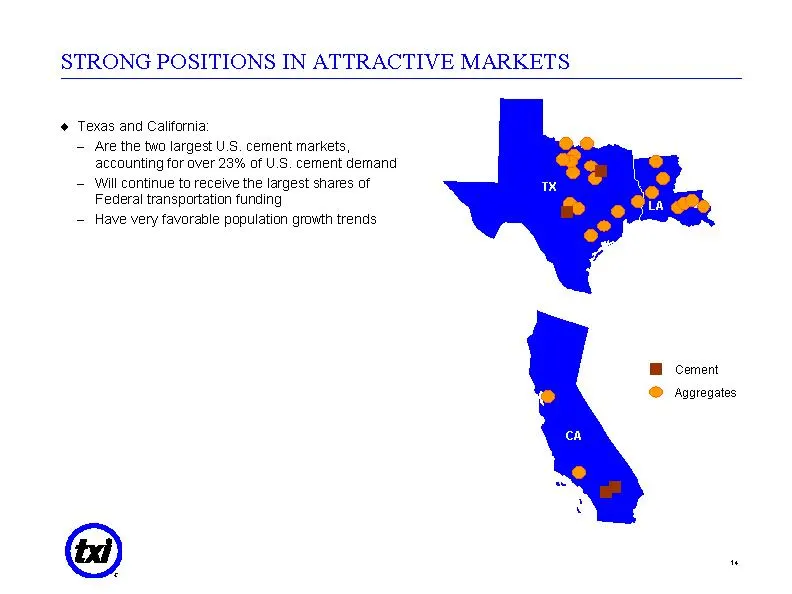
STRONG POSITIONS IN ATTRACTIVE MARKETS @ Texas and California Are the two largest U.S. cement markets, accounting for over 23% of U.S. cement demand Will continue to receive the largest shares of Federal transportation funding Have very favorable population growth trends @ Cement @ Agaregates
Slide 16: Strong Positions in Attractive Markets
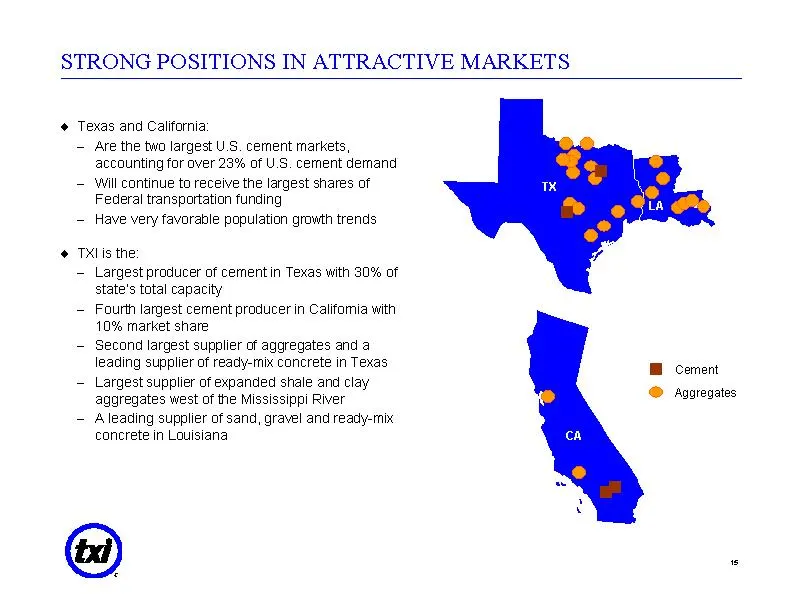
STRONG POSITIONS IN ATTRACTIVE MARKETS Texas and California — Are the two largest U.S. cement markets, accounting for aver 23% of U.S. cement demand — Will continue to receive the largest shares of Federal transportation funding — Have very favorable population growth trends Txlis the — Largest prod
Slide 17: Low Cost Operations Are Key
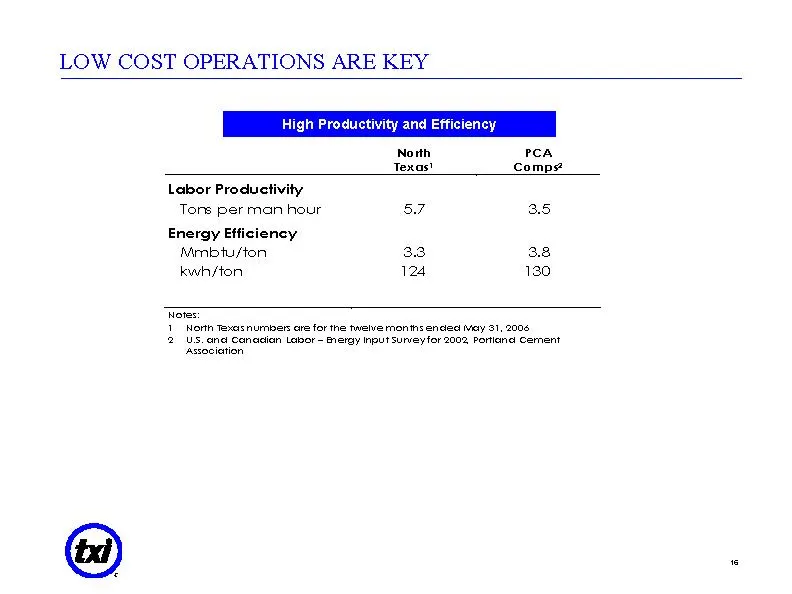
LOW COST OPERATIONS ARE KEY High Productivity and Efficiency Notth PCA Texas! Comps Labor Productivity Tons per man hour 57 3.5 Energy Efficiency Mmbbtu/ton 33 38 kwh/ton 124 130 1 North Texels hurnbes one for the rwalvernontns endad Wty 31, 2005 2 US. ana Cemadian Labor Brergy Input Survey fer 2002
Slide 18: California Plant Modernization and Expansion
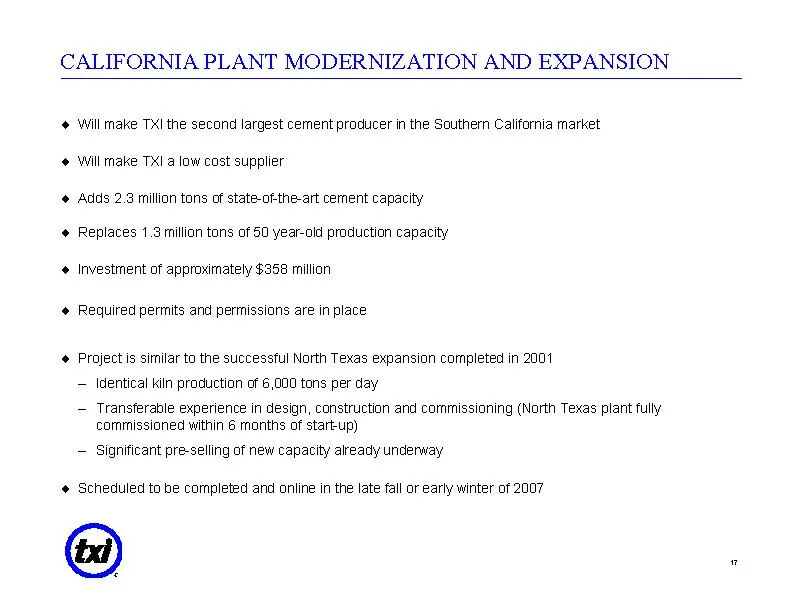
CALIFORNIA PLANT MODERNIZATION AND EXPANSION Will make TXI the second largest cement producer in the Southern California market Will make TX! a low cost supplier ¢ Adds 2.3 millian tons of state-of-the-art cement capacity . Replaces 1.3 millian tans of 50 year-old production capacity ¢ Investment of
Slide 19: Cement Plant Expansion Projects
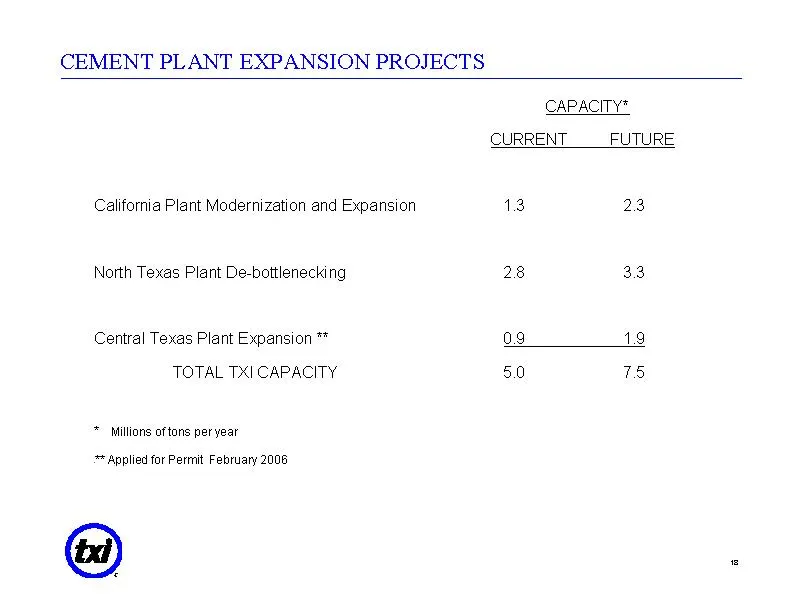
CEMENT PLANT EXPANSION PROJECTS CAPACITY* CURRENT FUTURE California Plant Modernization and Expansion 13 North Texas Plant De-bottlenecking 28 Central Texas Plant Expansion ** og TOTAL TXI CAPACITY. 5.0 * Millions oftons per year Applied for Permit February 2006 2a 33 19 75
Slide 20: TXI Earnings Potential
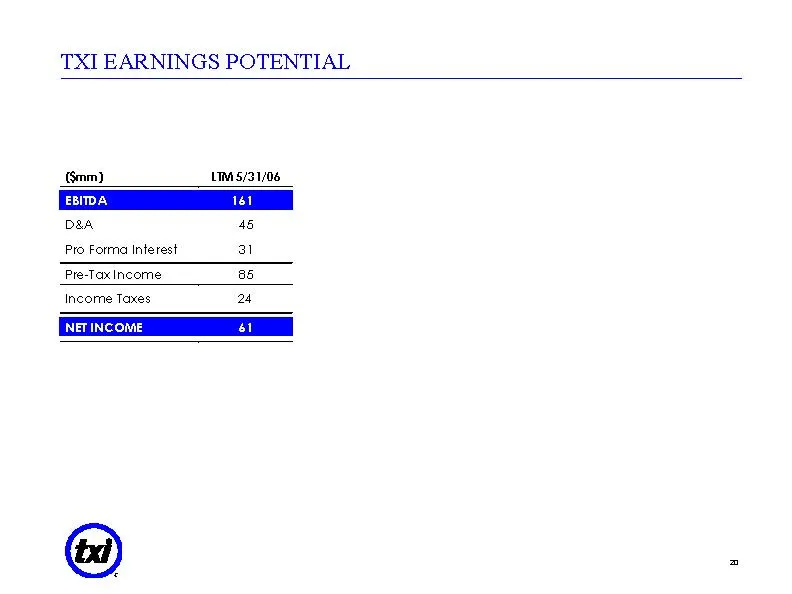
TXI EARNINGS POTENTIAL
Slide 21: TXI Earnings Potential
TXI EARNINGS POTENTIAL mm) 11M 5/31/06 Daa 45 Pro Forma Interest 31 Pre-Tax Income: 85 Income Taxes 24
Slide 22: TXI Earnings Potential (continued)
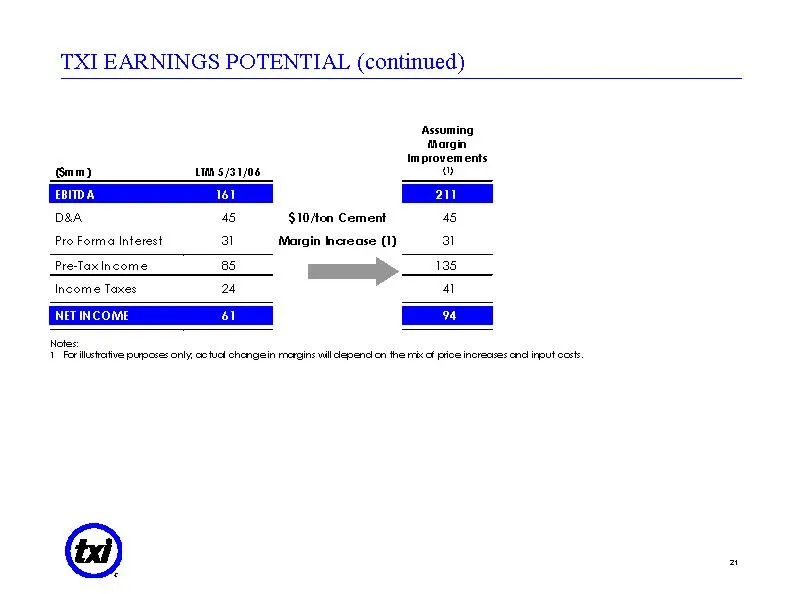
TXI EARNINGS POTENTIAL (continued) Assuming orgn Improvements mm) Lian 5/31/06 ay EBITDA 161 =a) DBA 45 $10/ton Cement 45 Pro Forma Interest 31 Margin Increase (1) al Fielancome OCS Tas Income Taxes 24 . 4) NETINCOME or [om | Notes 1) Fev ishetve purpesas only, aotuel chengsin reegin wll lapencn the
Slide 23: TXI Earnings Potential (continued)
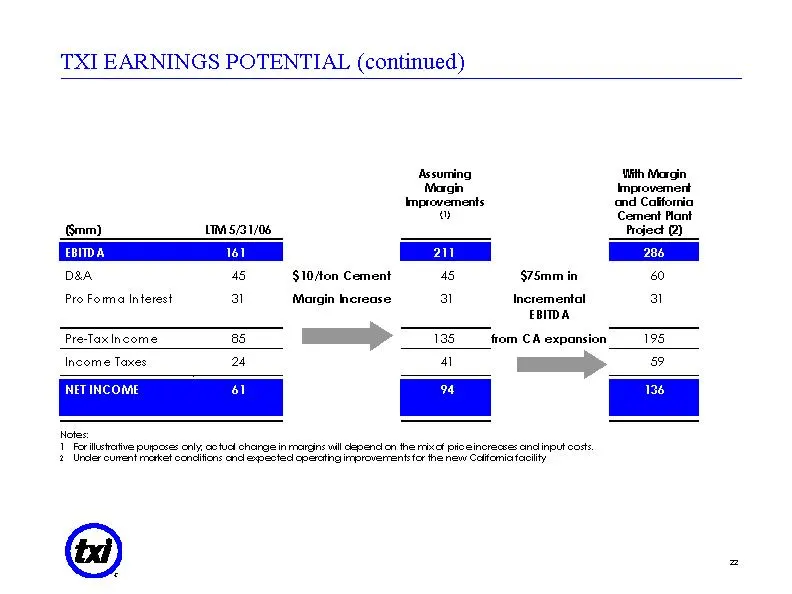
TXI EARNINGS POTENTIAL (continued) Assuring Wth Margin ‘Margin Improvement Improvements end Caifornia o mm) 11M 5/31/06 EBITDA 161 DBA 45 $10/ton Cement 45 75mm in 60 Pro Fora Interest al Margin increase al Incremental al EBITDA, PreTax income 85 135 from CA expans 198 Tncometaxes A eal “_ Ea | Note
Slide 24: Primary Earnings Drivers
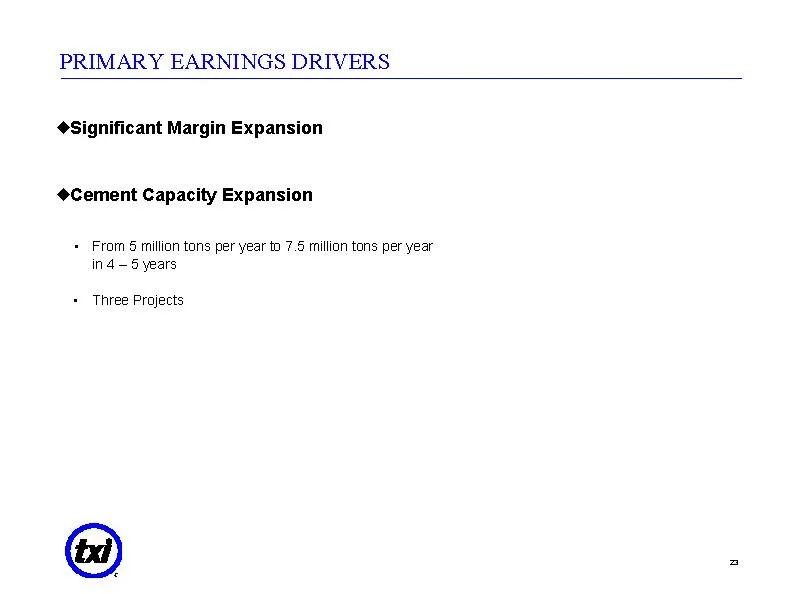
PRIMARY EARNINGS DRIVERS Significant Margin Expansion Cement Capacity Expansion + From 6 milion tans per year to 7.6 million tons per year in4—5 years + Three Projects
Slide 25: [Logo of TXI]
[LOGO OF TXI] FIRST DALLAS SECURITIES INVESTMENT FORUM AUGUST 2006 FORWARD-LOOKING STATEMENT Certain statements contained in this presentation are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to risks, uncertaint
Source: SEC EDGAR · 8-K filed Aug 31, 2006
More decks from Texas Industries Inc
 BB&T 8th Annual Commercial & Industrial Investor Conference (March 2014)26 slides · Mar 26, 2014
 Merger or Acquisition (January 2014)16 slides · Jan 28, 2014
 Stephens Conference 201337 slides · Nov 12, 2013
 Investor Presentation (March 2013)39 slides · Mar 5, 2013
 Investor Presentation (September 2012)33 slides · Sep 11, 2012
 Bank of America Merrill Lynch Leveraged Finance Conference 201133 slides · Dec 1, 2011