Citizens Republic Bancorp — Citizens Banking — Midwest Super-Community Bank Conference 2006
28 slides from Citizens Republic Bancorp's conference presentation, Feb 28, 2006
Slide 1: Midwest Super-Community Bank Conference March 1, 2006
Midwest Super-Community Bank Conference March 1, 2006
Slide 2: Safe Harbor Statement
Safe Harbor Statement Discussions in this release that are not statements of historical fact (including statements that include terms such as "will" "may," "should," "believe," "expect," "anticipate," "estimate," "intend," and "plan") are forward-looking statements that involve risks and uncertainti
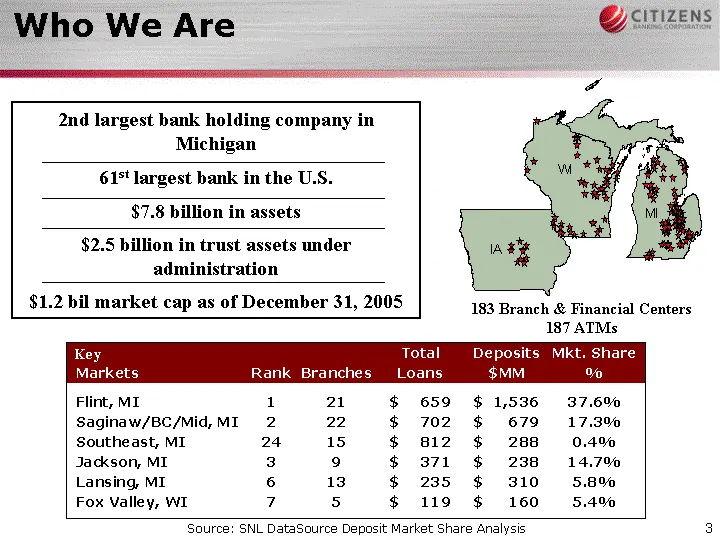
Slide 3: Who We Are
Who We Are 2nd largest bank holding company in Michigan 61st largest bank in the U.S. $7.8 billion in assets $2.5 billion in trust assets under administration $1.2 bil market cap as of December 31, 2005 183 Branch & Financial Centers 187 ATMs Source: SNL DataSource Deposit Market Share Analysis
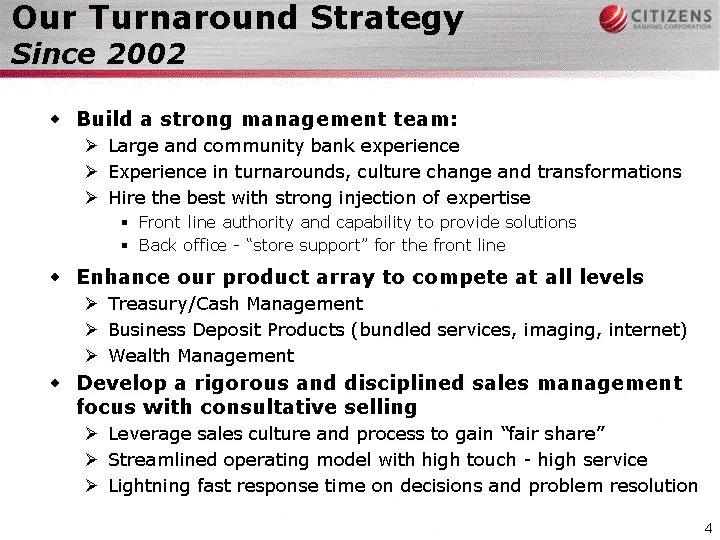
Slide 4: Our Turnaround Strategy Since 2002
Our Turnaround Strategy Since 2002 Build a strong management team: Large and community bank experience Experience in turnarounds, culture change and transformations Hire the best with strong injection of expertise Front line authority and capability to provide solutions Back office - "store support"
Slide 5: Our Turnaround Strategy Since 2002 (continued)
Our Turnaround Strategy Since 2002 Invest into high growth markets enhancing our footprint Southeast Michigan New Management Team and seasoned personnel in Wisconsin Make the necessary people and process changes to enhance our operating model Enterprise risk management Program management process wit
Slide 6: Proven Ability to Execute
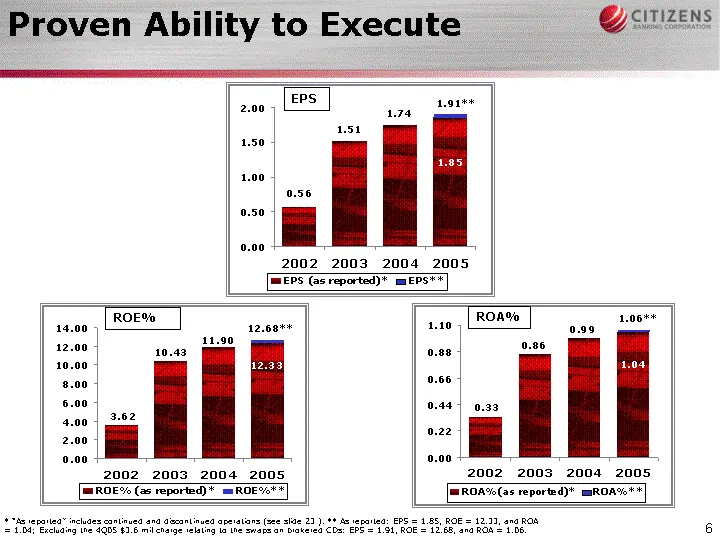
Proven Ability to Execute * "As reported" includes continued and discontinued operations (see slide 23 ). ** As reported: EPS = 1.85, ROE = 12.33, and ROA = 1.04; Excluding the 4Q05 $3.6 mil charge relating to the swaps on brokered CDs: EPS = 1.91, ROE = 12.68, and ROA = 1.06. 2002 2003 2004 2005 RO
Slide 7: Consistent Loan Growth Trends After a Period of Rationalizing Credit
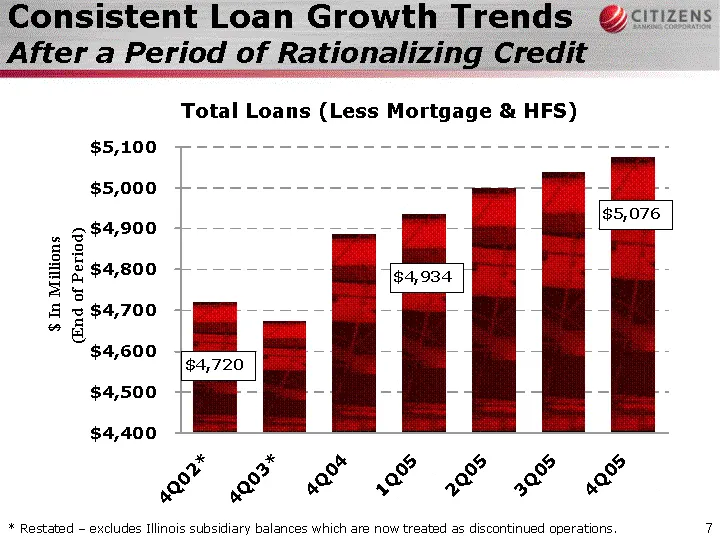
Consistent Loan Growth Trends After a Period of Rationalizing Credit 4Q01 1Q02 2Q02 3Q02 4Q02* 1Q03 2Q03 3Q03 4Q03* 1Q04* 2Q04* 3Q04 4Q04 1Q05 2Q05 3Q05 4Q05 Consumer Loans Total Loans (Less Mortgage & HFS) 4873 4828 4897 4855 4720 4706 4705 4737 4672 4724 4820 4801 4885 4934 4998 5037 5076 Illinois
Slide 8: Proven Ability to Execute: Southeast Michigan Initiative
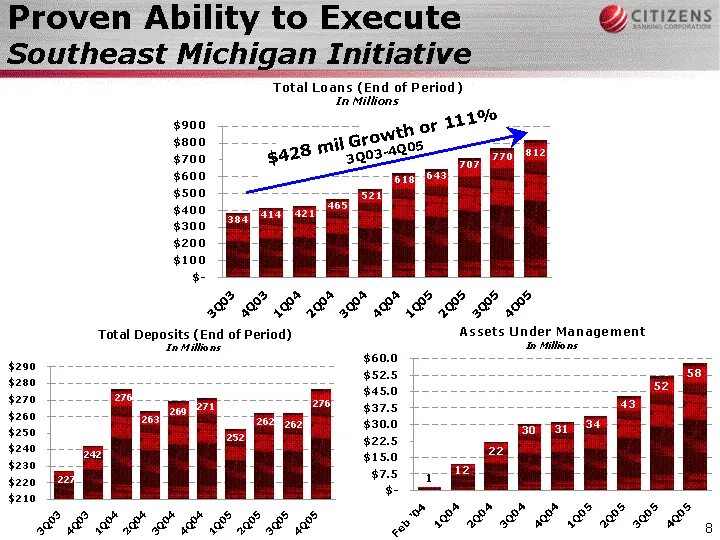
Proven Ability to Execute Southeast Michigan Initiative 2Q03 3Q03 4Q03 1Q04 2Q04 3Q04 4Q04 1Q05 2Q05 3Q05 4O05 Average Loans 366 384 414 421 465 521 618 643 707 770 812 2Q03 3Q03 4Q03 1Q04 2Q04 3Q04 4Q04 1Q05 2Q05 3Q05 4Q05 Average Deposits 232 227 242 276 263 269 271 252 262 262 276 $428 mil Growth
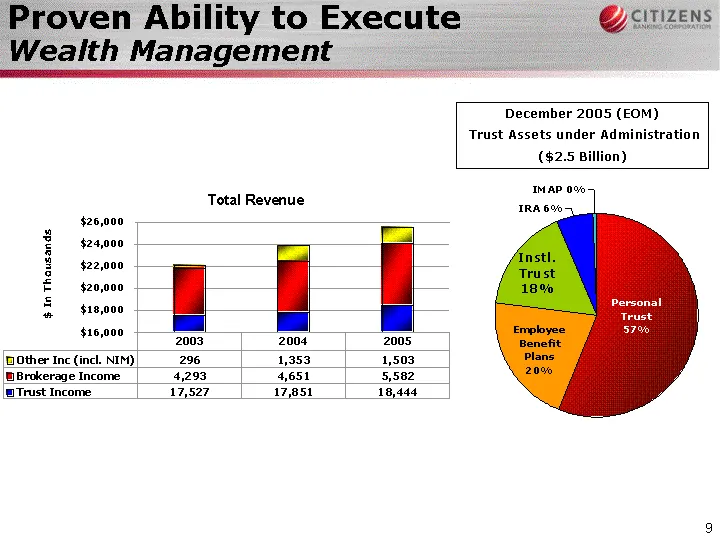
Slide 9: Proven Ability to Execute: Wealth Management
Proven Ability to Execute Wealth Management 2003 2004 2005 Trust Income 17527 17851 18444 Brokerage Income 4293 4651 5582 Other Inc (incl. NIM) 296 1353 1503 Personal Trust Employee Benefit Plans Institutional Trust IRA IMAP December 2004 Trust Assets 1420 527 423 149 11 December 2005 (EOM) Trust As
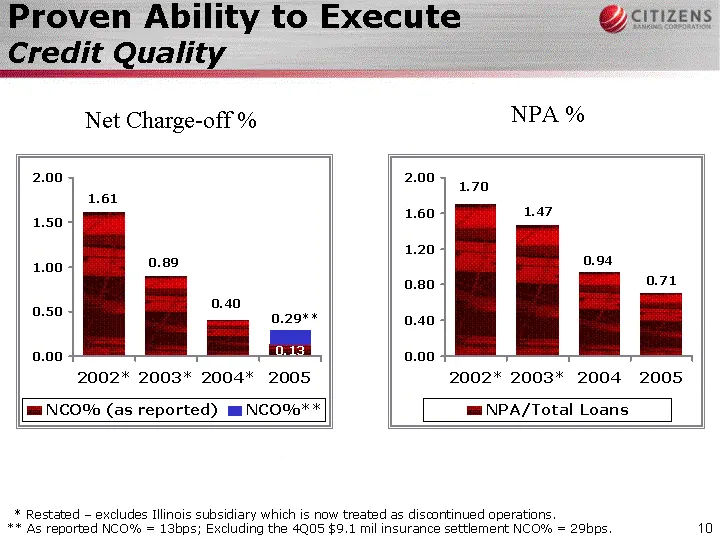
Slide 10: Proven Ability to Execute: Credit Quality
2002* 2003* 2004* 2005 NCO% (as reported) 1.61 0.89 0.4 0.13 NCO%** 0.16 0.29** 2002* 2003* 2004 2005 NPA/Total Loans 1.7 1.47 0.94 0.71 ** As reported NCO% = 13bps; Excluding the 4Q05 $9.1 mil insurance settlement NCO% = 29bps. Proven Ability to Execute Credit Quality * Restated - excludes Illinois
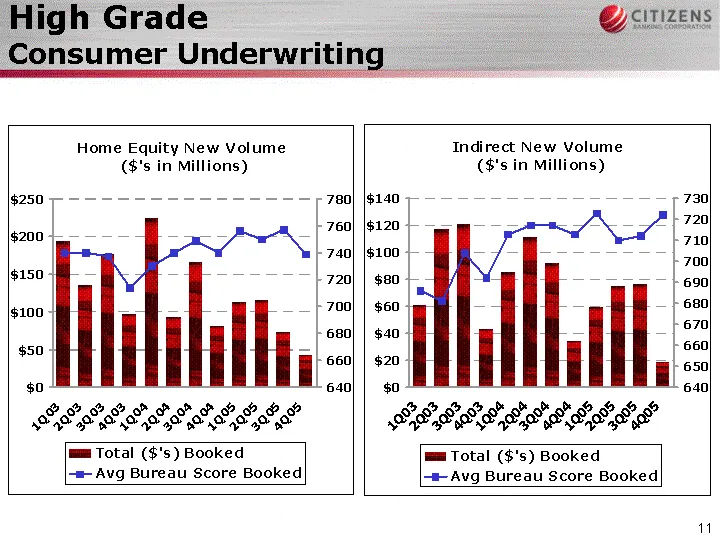
Slide 11: High Grade Consumer Underwriting
High Grade Consumer Underwriting 1Q03 2Q03 3Q03 4Q03 1Q04 2Q04 3Q04 4Q04 1Q05 2Q05 3Q05 4Q05 Total ($'s) Booked 193162 135047 176331 96173 223908 91912 165608 80020 112862 115444 72269 43000 Avg Bureau Score Booked 740 740 737 714 730 740 749 740 756 750 757 739 1Q03 2Q03 3Q03 4Q03 1Q04 2Q04 3Q04 4Q
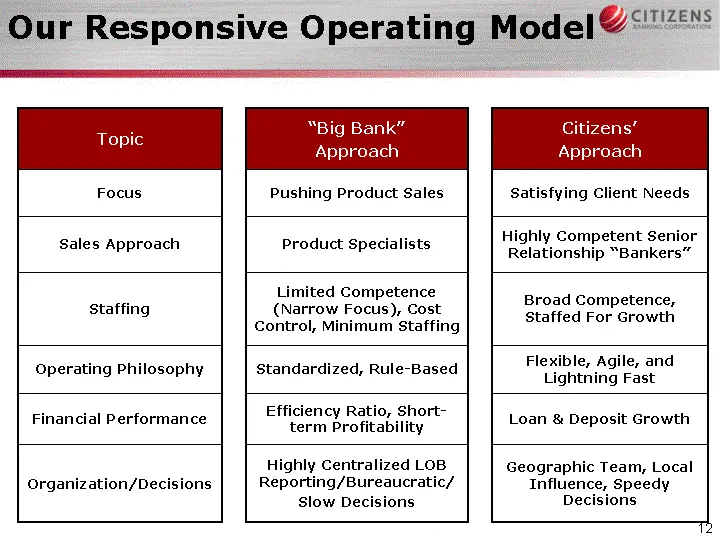
Slide 12: Our Responsive Operating Model
Our Responsive Operating Model Topic "Big Bank" Approach Citizens' Approach Focus Pushing Product Sales Satisfying Client Needs Sales Approach Product Specialists Highly Competent Senior Relationship "Bankers" Staffing Limited Competence (Narrow Focus), Cost Control, Minimum Staffing Broad Competenc
Slide 13: Industry Challenges for 2006
Industry Challenges for 2006 Margins will struggle Flat or inverted curve Spread compression on loans and deposits Price competition for non-maturity deposits will continue to increase Tough regulatory environment requiring significant focus while costs continue to rise Early signs of consumer econo
Slide 14: 2006 Growth Strategy
2006 Growth Strategy Developed and implemented new strategic plan Conducted planning process Sept. through January Goal was to develop a strategy that delivers our key corporate objectives Improved levels of Return on Equity Organic revenue growth leading to profitability growth Consistent and disci
Slide 15: What We Identified From Our Situation Analysis
What We Identified From Our Situation Analysis We did an assessment to determine our growth and profit potential After analyzing several peer groups ~ 50% with similar markets and business mix achieve attractive results (not skewed toward MI): Our findings indicated there is no correlation between l
Slide 16: Our Highest Strategic Priorities
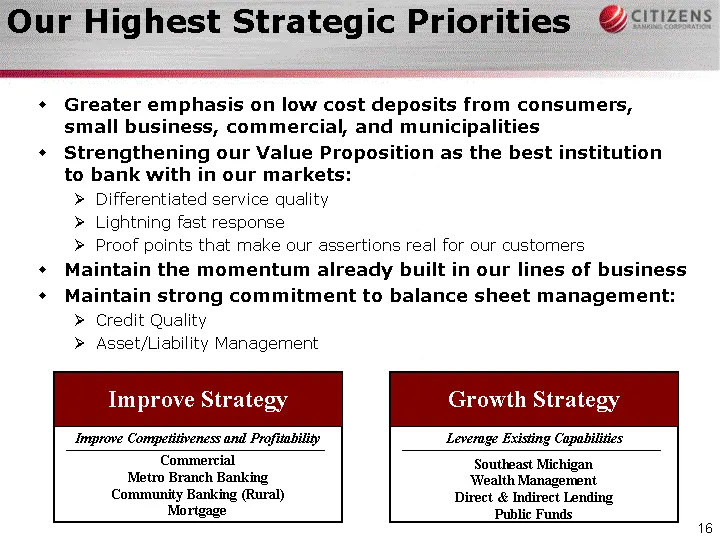
Our Highest Strategic Priorities Greater emphasis on low cost deposits from consumers, small business, commercial, and municipalities Strengthening our Value Proposition as the best institution to bank with in our markets: Differentiated service quality Lightning fast response Proof points that make
Slide 17: Commercial Strategy Highlights
Commercial Strategy Highlights Value Proposition Serving clients and prospects with the best Commercial Bankers in all of our markets Be highly skilled and responsive in delivering service Have superior industry knowledge and solutions to meet client needs Have "boundaryless" access and support from
Slide 18: Metro Branch Banking Strategy Highlights
Metro Branch Banking Strategy Highlights Value Proposition Treat clients and prospects with fairness and respect and care for everyone as an individual Strategy Provide a consistent positive service experience Enhance our ability to sell and retain low-cost consumer and small business deposits Incre
Slide 19: Community Banking in Rural Markets
Community Banking in Rural Markets Strategy Highlights Value Proposition Serving clients and prospects with the best Community Bankers in all of our markets Skill and capability to be the "Go-to Person" in each market Lives in the community Strategy Provide a consistent positive service experience I
Slide 20: Wealth Management Strategy Highlights
Wealth Management Strategy Highlights Value Proposition Providing superior results through expert advice, effective financial solutions and service you would expect from a true partner Strategy Provide high-touch, high quality, solutions based sales process and client experience Deliver objective an
Slide 21: Indirect Lending Strategy Highlights
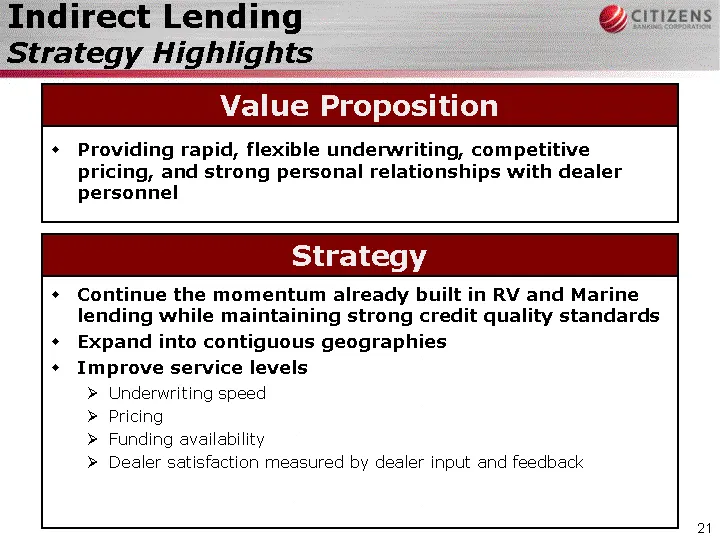
Indirect Lending Strategy Highlights Value Proposition Providing rapid, flexible underwriting, competitive pricing, and strong personal relationships with dealer personnel Strategy Continue the momentum already built in RV and Marine lending while maintaining strong credit quality standards Expand i
Slide 22: Financial Highlights
: Ocinzens Financial Highlights / /
Slide 23: Summary Income Statement
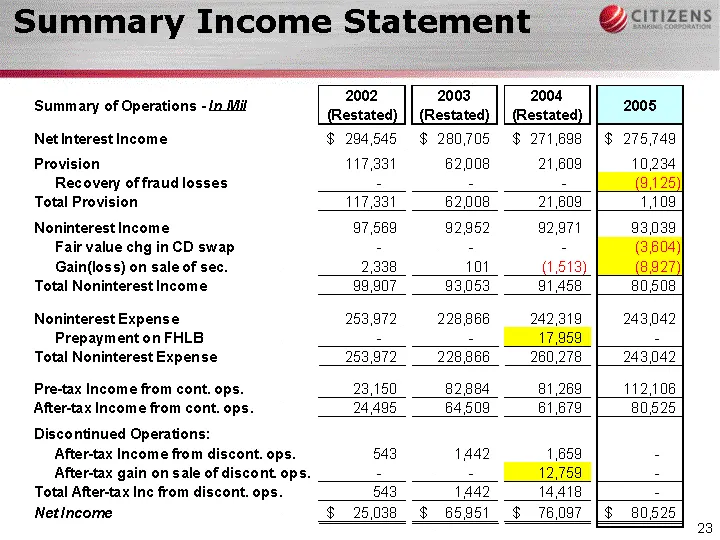
Summary Income Statement Summary Income Statement
Slide 24: Balance Sheet Highlights
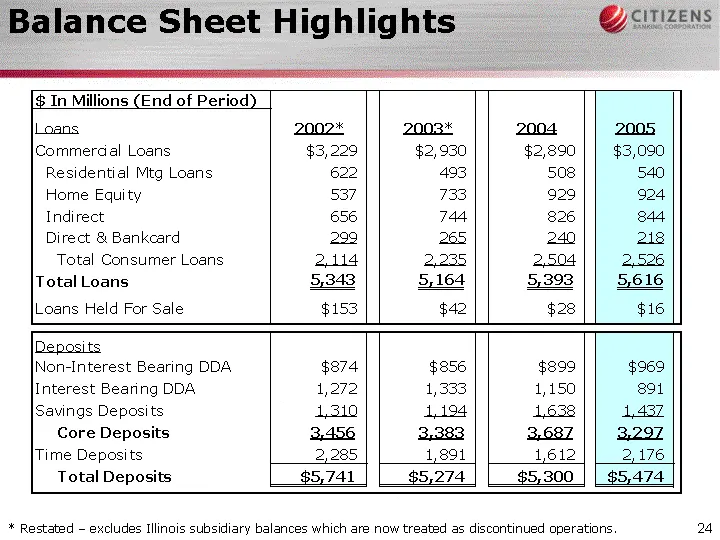
Balance Sheet Highlights Balance Sheet Highlights * Restated - excludes Illinois subsidiary balances which are now treated as discontinued operations.
Slide 25: Key Ratios: Credit Quality & Capital
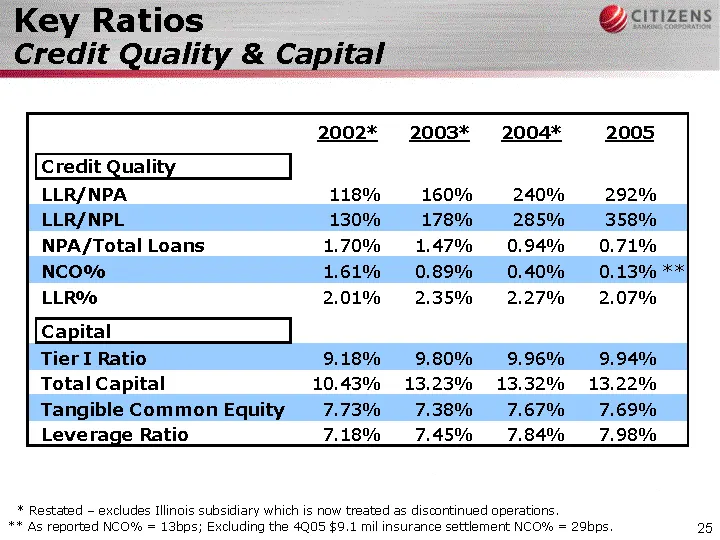
Key Ratios Credit Quality & Capital 2002* 2003* 2004* 2005 Credit Quality LLR/NPA 118% 160% 240% 292% LLR/NPL 130% 178% 285% 358% NPA/Total Loans 1.70% 1.47% 0.94% 0.71% NCO% 1.61% 0.89% 0.40% 0.13% ** LLR% 2.01% 2.35% 2.27% 2.07% Capital Tier I Ratio 9.18% 9.80% 9.96% 9.94% Total Capital 10.43% 13.
Slide 26: Citizens Opportunities in 2006
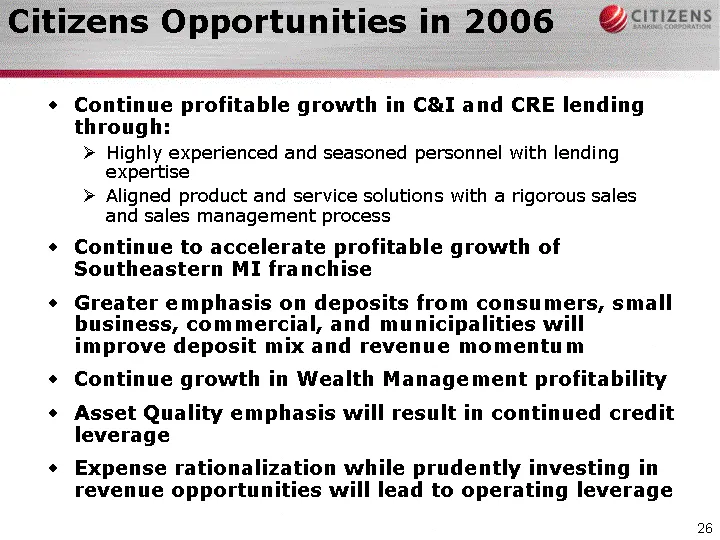
Citizens Opportunities in 2006 Continue profitable growth in C&I and CRE lending through: Highly experienced and seasoned personnel with lending expertise Aligned product and service solutions with a rigorous sales and sales management process Continue to accelerate profitable growth of Southeastern
Slide 27: Why Invest In Citizens?
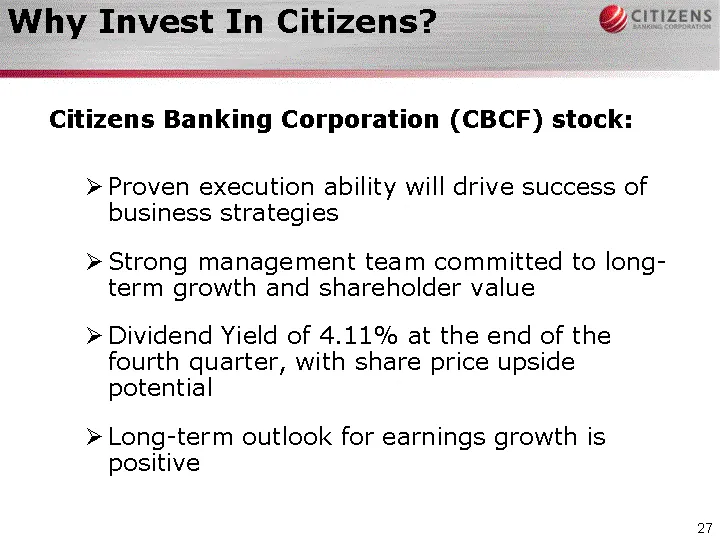
Why Invest In Citizens? Citizens Banking Corporation (CBCF) stock: Proven execution ability will drive success of business strategies Strong management team committed to long- term growth and shareholder value Dividend Yield of 4.11% at the end of the fourth quarter, with share price upside potentia
Slide 28: Let's Make It Happen
Source: SEC EDGAR · 8-K filed Feb 28, 2006
More decks from Citizens Republic Bancorp Inc
 Debt Investor Presentation (January 2013)30 slides · Jan 23, 2013
 Q4 2012 Earnings Presentation47 slides · Jan 22, 2013
 Q3 2012 Earnings Presentation47 slides · Oct 26, 2012
 Merger or Acquisition (September 2012)28 slides · Sep 13, 2012
 Q2 2012 Earnings Presentation47 slides · Jul 30, 2012
 Q1 2012 Earnings Presentation49 slides · Apr 27, 2012