American Railcar Industries Inc
American Railcar Industries — Investor Presentation (November 2015)
30 slides from American Railcar Industries's investor presentation, Nov 6, 2015
Slide 1: American Railcar Industries, Inc. Investor Presentation — November 2015
American Railcar Industries, Inc. INVESTOR PRESENTATION — NOVEMBER 2015 INVESTOR CONTACT: (636) 940-6000 WEBSITE: WWW.AMERICANRAILCAR.COM
Slide 2: Forward Looking Disclaimer
© Forward Looking Disclaimer Sate Harbor Statement without limitation, statements services, operating margin, revenues, Pepe Speer iiss saree ors ape tees eae se escherere ee ee cea et eae leer ven Sicteye sep ar a ree gully needs and inancieg pars, ancipaed benelis fom expansion and dveritealion of
Slide 3: North American Fleet by Railcar Type
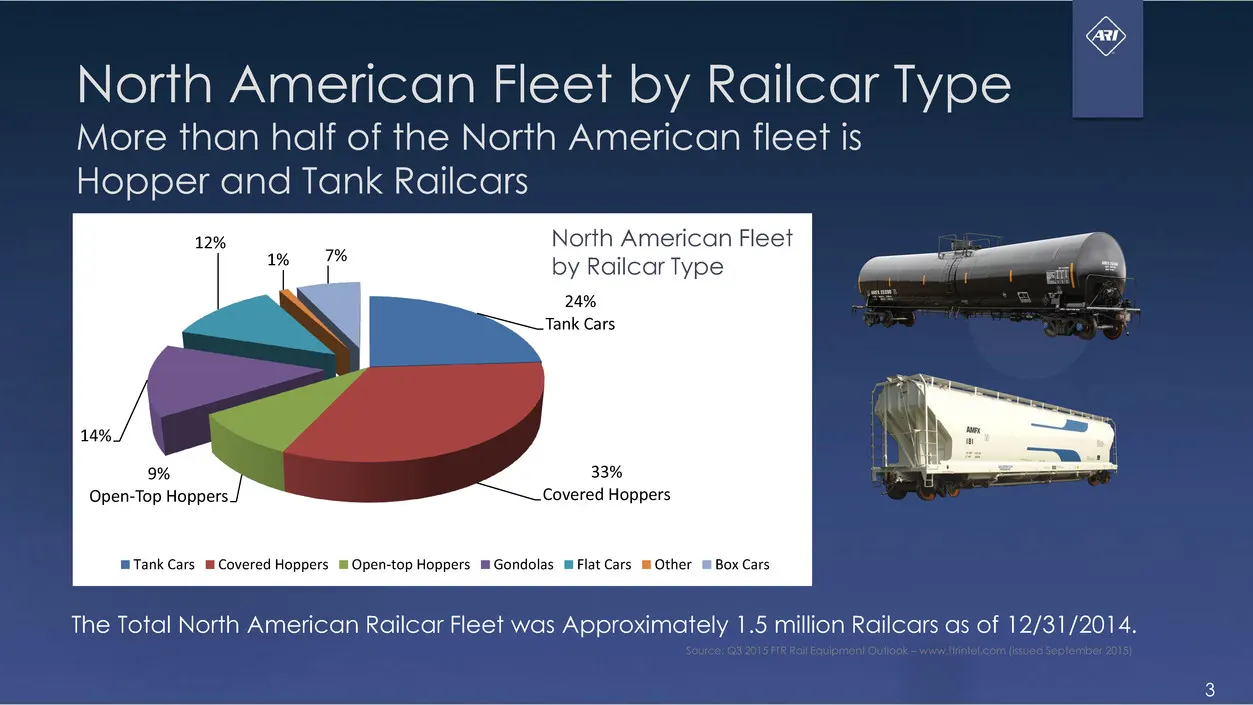
North American Fleet by Railcar Type More than half of the North American fleet is Hopper and Tank Railcars North American Fleet by Railcar Type 24% Tank Cars 9% Covered Hoppers % Open-Top Hoppers mTank Cars m Covered Hoppers mOpen-top Hoppers mGondolas mFlat Cars mOther s Box Cars The Total North A
Slide 4: Cyclical Industry Trends
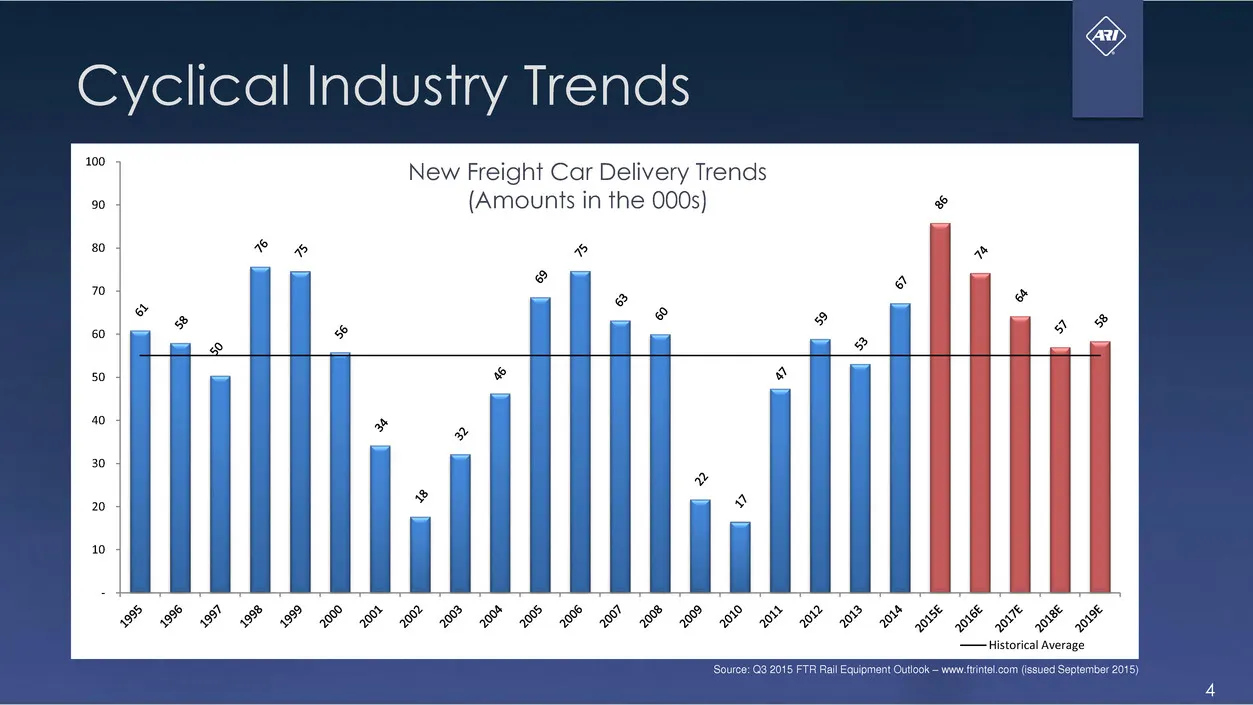
Cyclical Industry Trends New Freight Car Delivery Trends (Amounts in the 000s) @ e r Sj. 9 # SF SX gt —Historical Average ‘Source: 03 2015 FTR Rall Equipment Outlook ~ www frintl.com (issued September 2015)
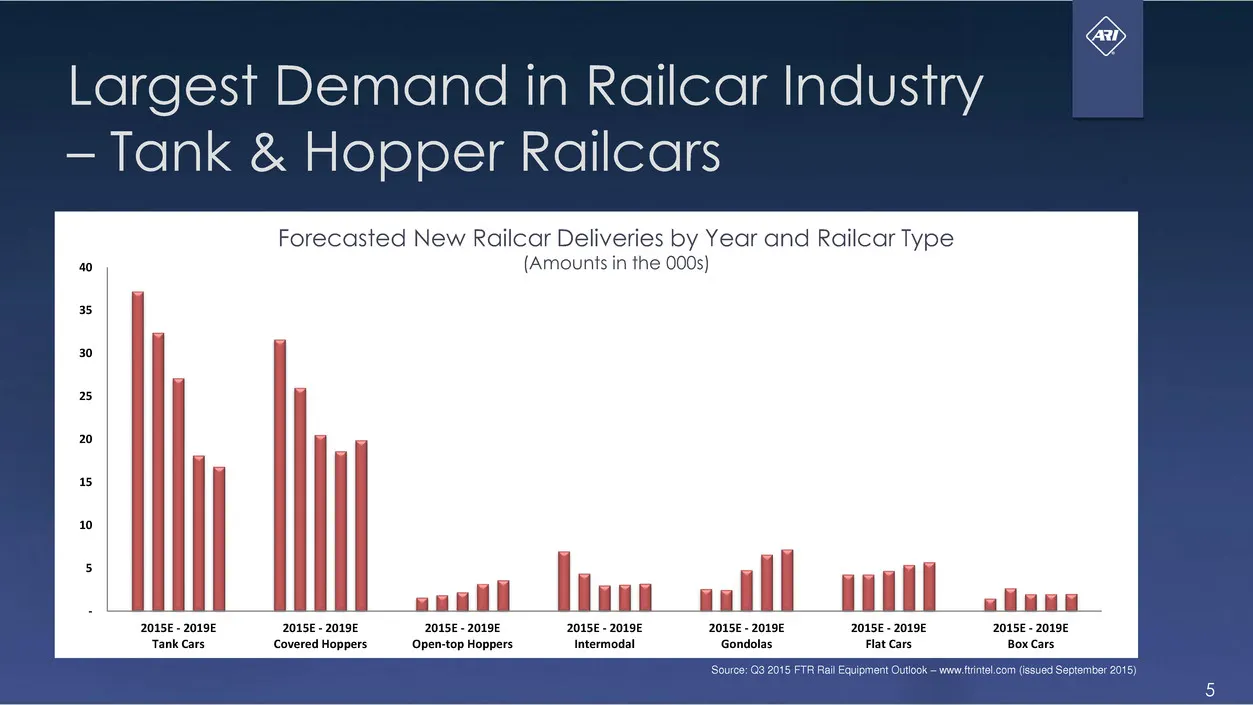
Slide 5: Largest Demand in Railcar Industry
Largest Demand in Railcar Industry Tank & Hopper Railcars Forecasted New Railcar Deliveries by Year and Railcar Type (Amounts in the 000s) BORER soe Re alll Tih oi 2015€ - 2019E 2015E - 2019E 2015E - 2019E 2015€ - 2019E 2015E - 20196 2015E - 2019 Covered Hoppers Open-top Hoppers Intermodal Gondolas
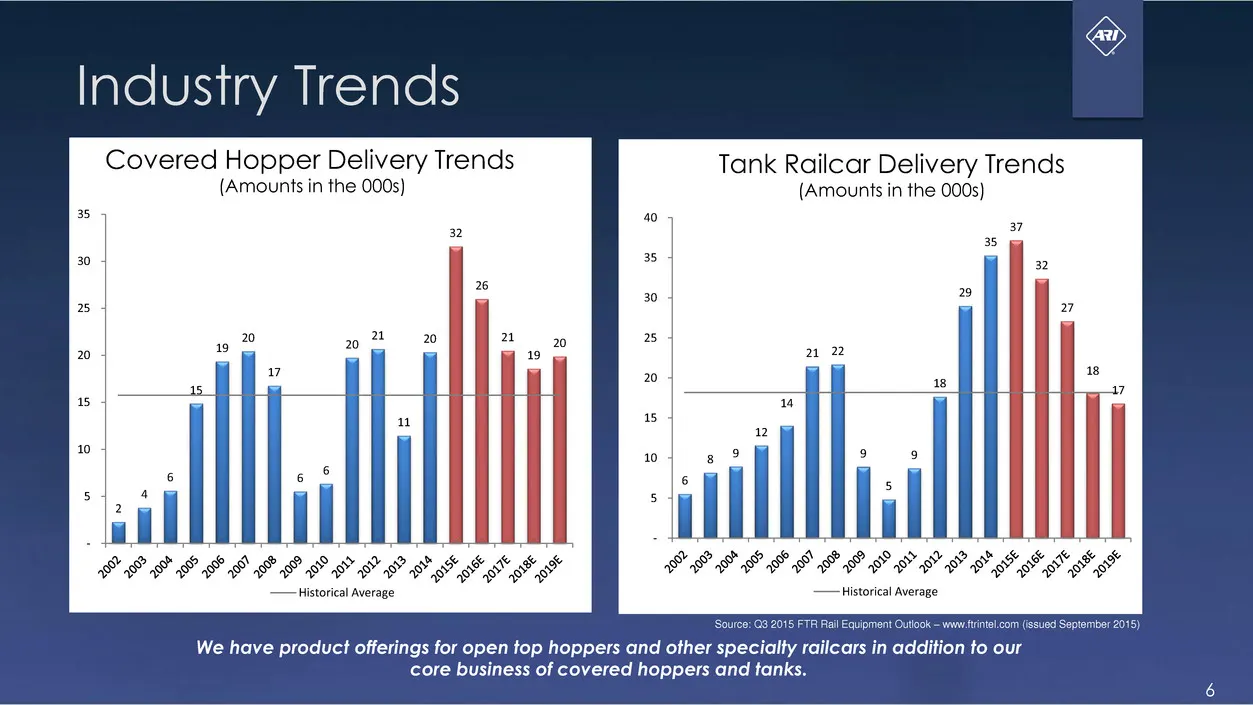
Slide 6: Industry Trends
Industry Trends Covered Hopper Delivery Trends (Amounts in the 000s) Tank Railcar Delivery Trends (Amounts in the 000s) ey & & FP SPS? PO SEK KS FIL LPP PL PI PK Kgs re LIL LS —Historical Average —Historical Average We have product offerings for open top hoppers and other specialty railcars in addit
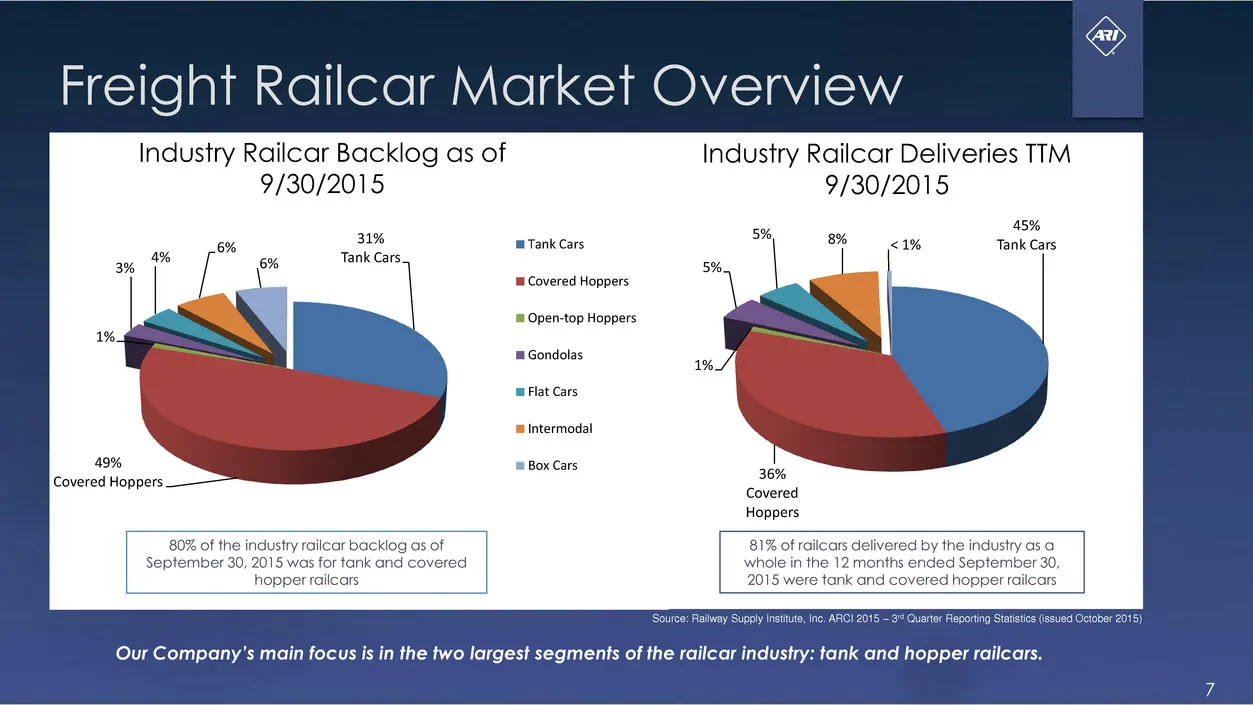
Slide 7: Freight Railcar Market Overview
Freight Railcar Market Overview Industry Railcar Backlog as of Industry Railcar Deliveries TIM 9/30/2015 9/30/2015 45% 31% m Tank Cars Tank Cars Tank Cars. Covered Hoppers = Open-top Hoppers Gondolas mFlat Cars Intermodal 49% = Box Cars Covered Hoppers. Covered Hoppers 80% of the industry railcar ba
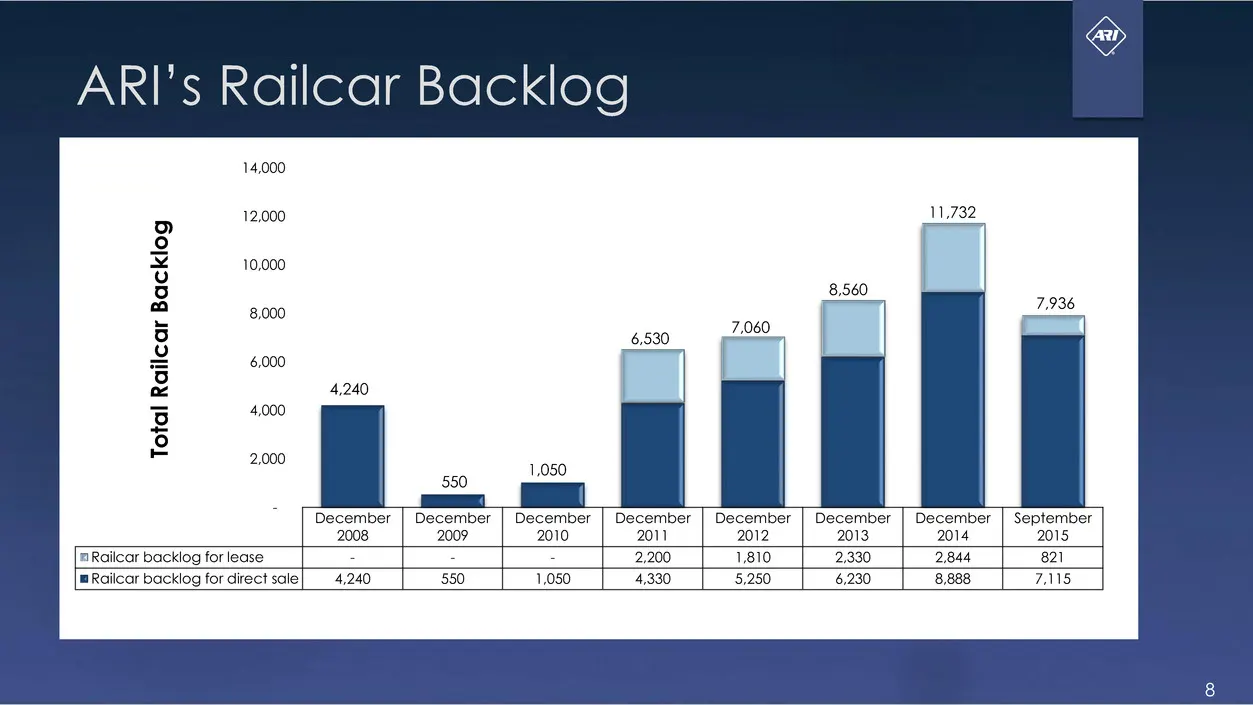
Slide 8: ARI’s Railcar Backlog
ARI’s Railcar Backlog D 3 x u 5 a - fe] o 5 a 3 ° 2 December December [ December | December | September 2008 2009 2010 2001 [BRailcar backlog forlease __| Z [ [iio [a0 [aa fo [mRoilcar backlog for direct sale] 4,240
Slide 9: ARI Key Railcar Markets
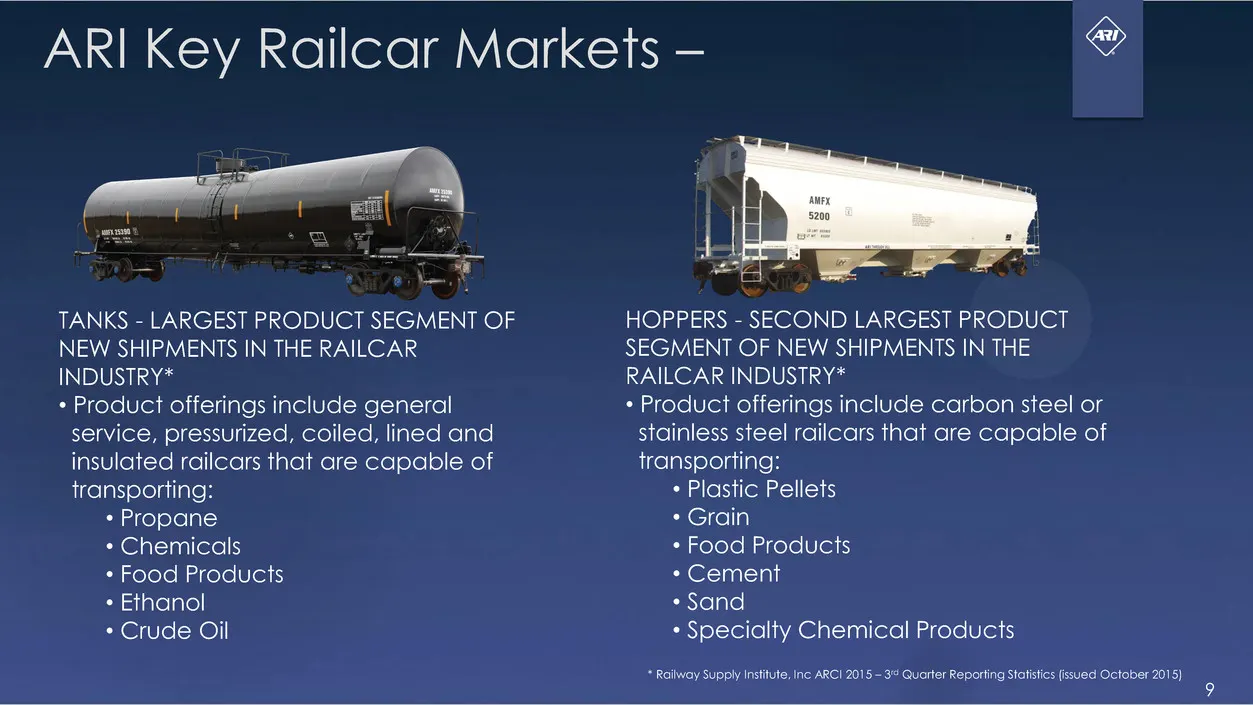
ARI Key Railcar Markets — TANKS - LARGEST PRODUCT SEGMENT OF NEW SHIPMENTS IN THE RAILCAR INDUSTRY* + Product offerings include general service, pressurized, coiled, lined and insulated railcars that are capable of transporting: + Propane + Chemicals + Food Products + Ethanol + Crude Oil HOPPERS - S
Slide 10: Tank Car Regulatory Changes
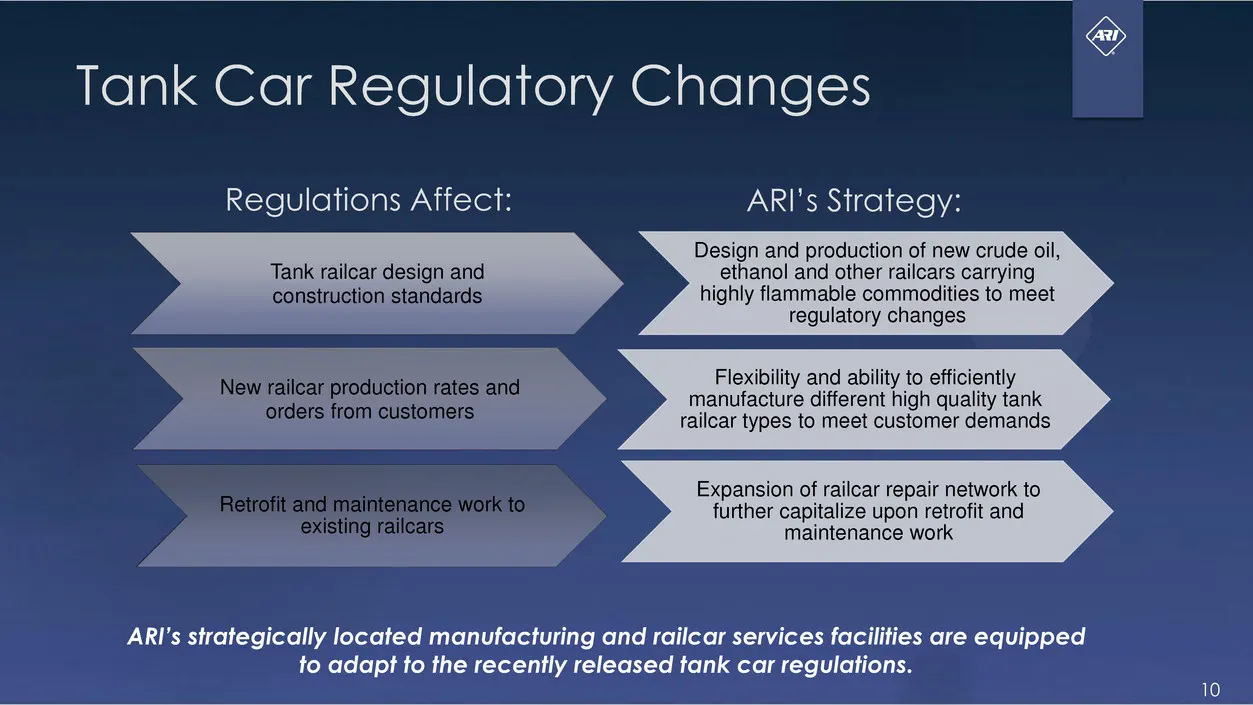
Tank Car Regulatory Changes Regulations Affect: ARI’s Strategy: Design and production of new crude oil, ethanol and other railcars carrying Tank railcar design and highly flammable commodities to meet construction standards regulatory changes Flexibility and ability to efficiently manufacture differ
Slide 11: Tank Car Regulatory Changes — Retrofit Timeline
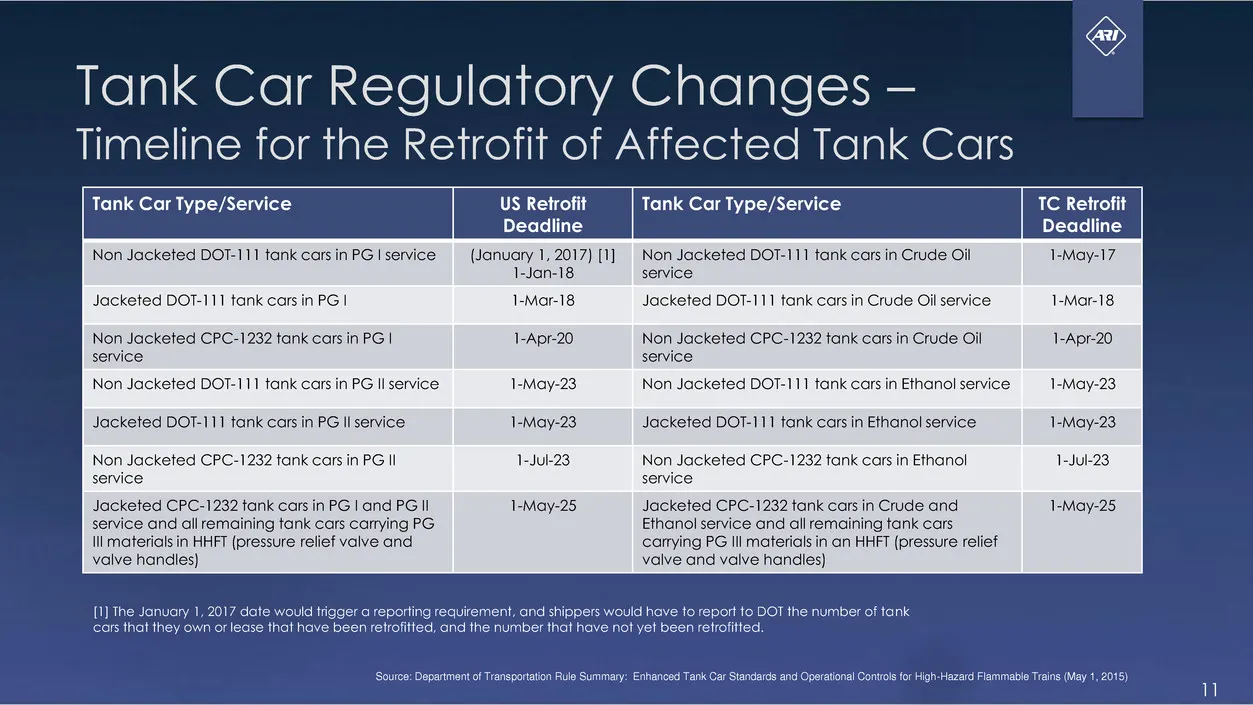
& Tank Car Regulatory Changes — Timeline for the Retrofit of Affected Tank Cars Tank Car Type/Service US Retrofit Tank Car Type/Service TC Retrofit Deadline Deadline Non Jacketed DOT-111 tank cars in PG Iservice | (January 1, 2017) [1] _ Non Jacketed DOT-111 tank cars in Crude Oil 1-May-17 1-Jon-18
Slide 12: Manufacturing Segment
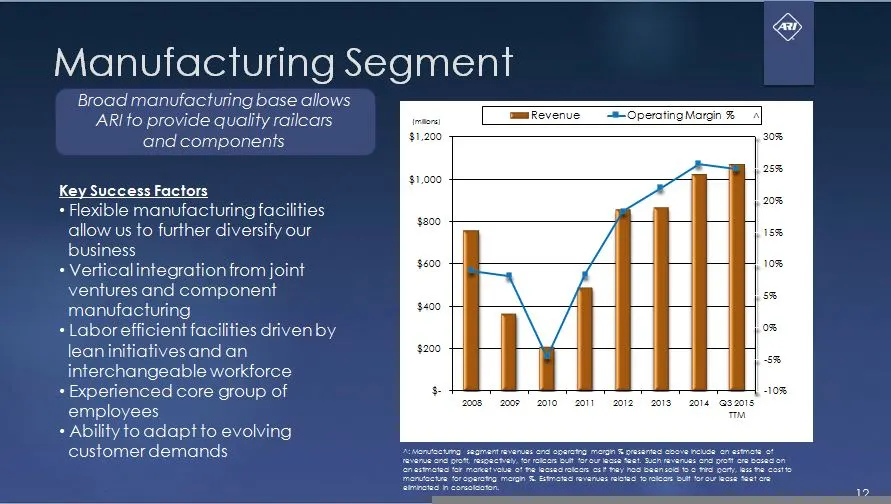
Manufacturing Segment Broad manufacturing base allows ARi to provide quality railcars and components Key Success Factors + Flexible manufacturing facilities allow us to further diversify our business + Verticalintegration from joint ventures and component manvfacturing + Labor efficient facilities d
Slide 13: Flexible Manufacturing Plants
Flexible Manufacturing Plants + Strategic Locations Near Customers and Major Rail Lines + Flexible and Vertically Integrated Facilities + Produce multiple railcar types with minimal change-over time + Paint & lining capabilities * Rolling mill and fabrication plants + Non-union workforce at railcar
Slide 14: ARI Component Manufacturing
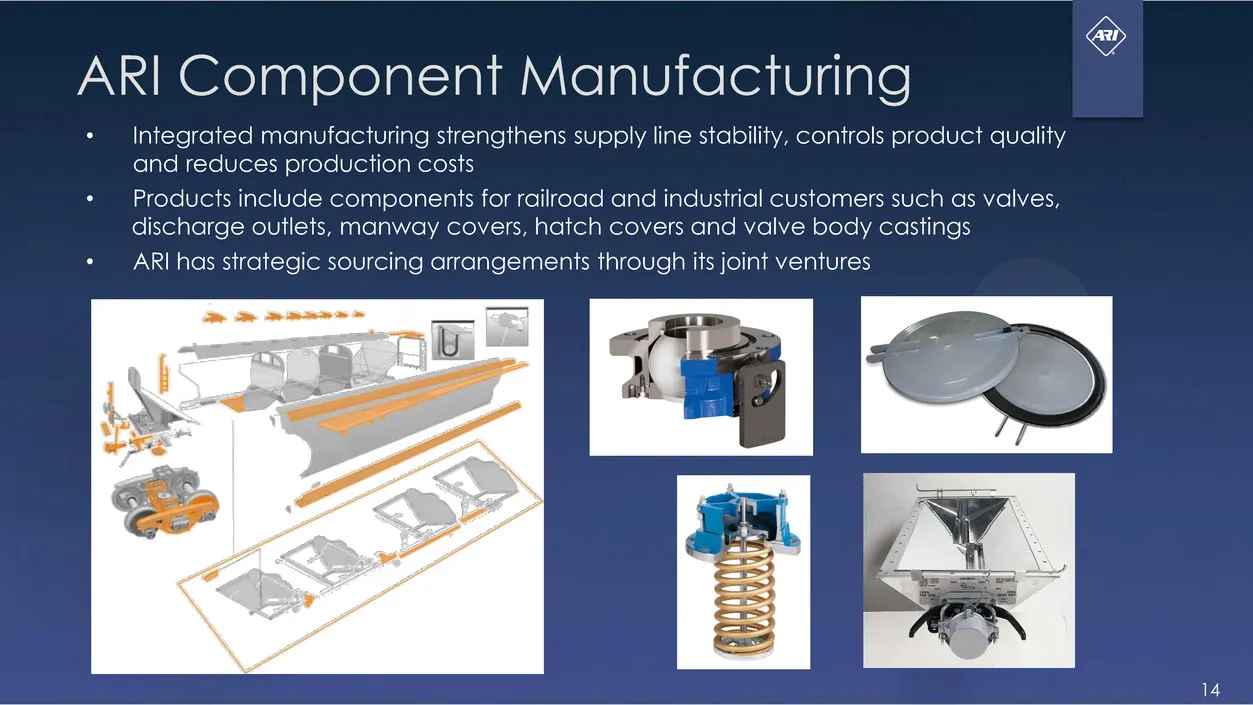
ARI Component Manufacturing Integrated manufacturing strengthens supply line stability, controls product quality and reduces production costs Products include components for railroad and industrial customers such as valves, discharge outlets, manway covers, hatch covers and valve body castings ARI h
Slide 15: Joint Venture — Axis, LLC
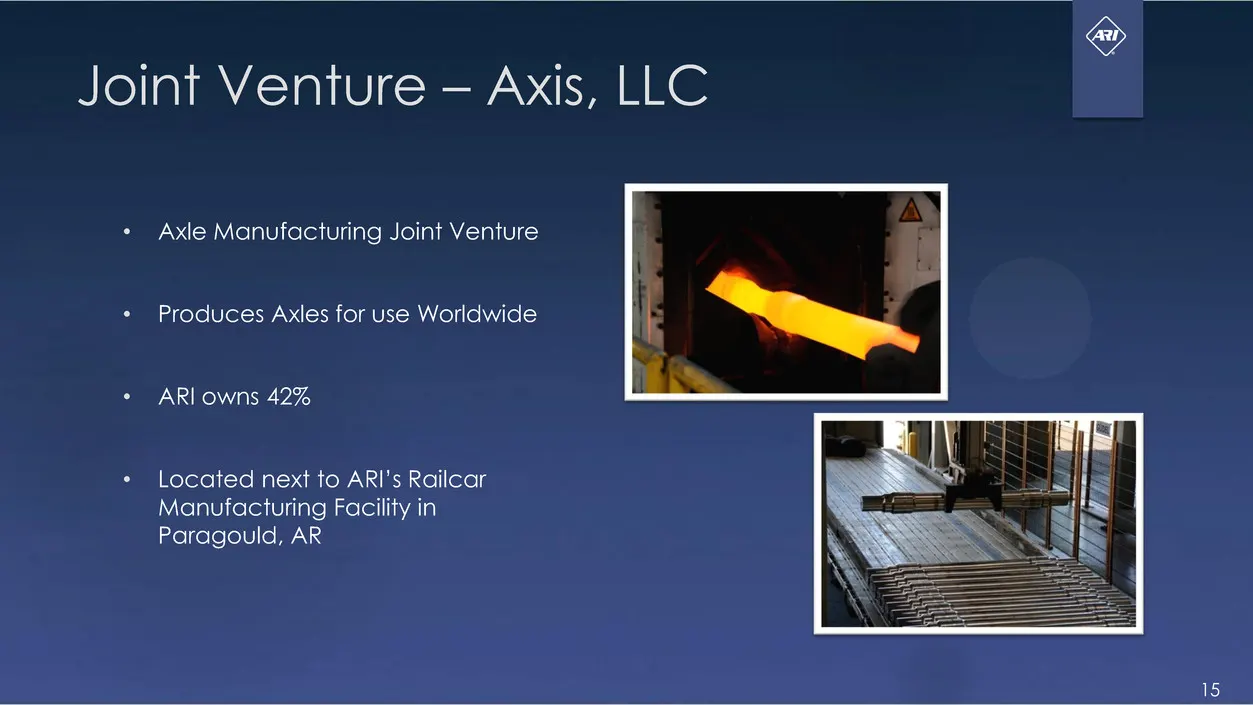
Joint Venture — Axis, LLC Axle Manufacturing Joint Venture Produces Axles for use Worldwide ARI owns 42% Located next to ARI’s Railcar Manufacturing Facility in Paragould, AR
Slide 16: Joint Venture — Ohio Castings, LLC
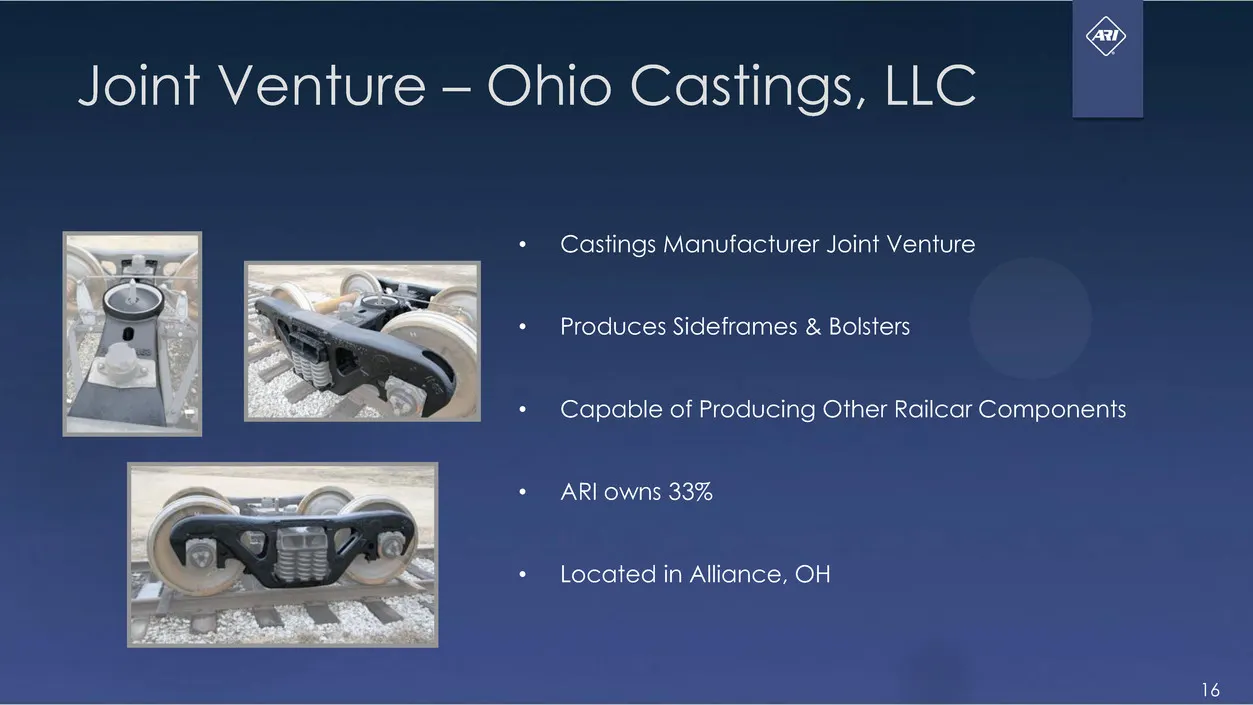
€ Joint Venture — Ohio Castings, LLC Castings Manufacturer Joint Venture + Produces Sideframes & Bolsters * Capable of Producing Other Railcar Components + ARI owns 33% + Located in Alliance, OH
Slide 17: Railcar Leasing Segment
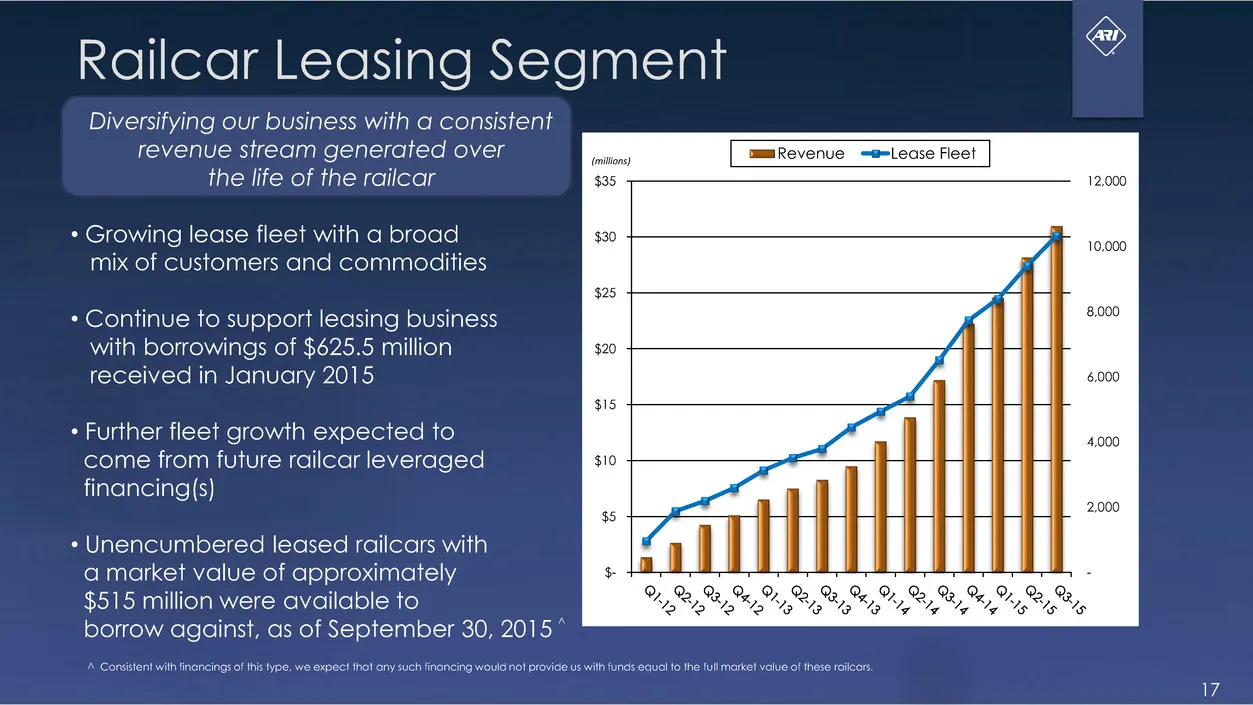
Railcar Leasing Segment Diversifying our business with a consistent revenue stream generated over amaw the life of the railcar $35 * Growing lease fleet with a broad mix of customers and commodities * Continue to support leasing business with borrowings of $625.5 million received in January 2015 + F
Slide 18: Railcar Services Segment
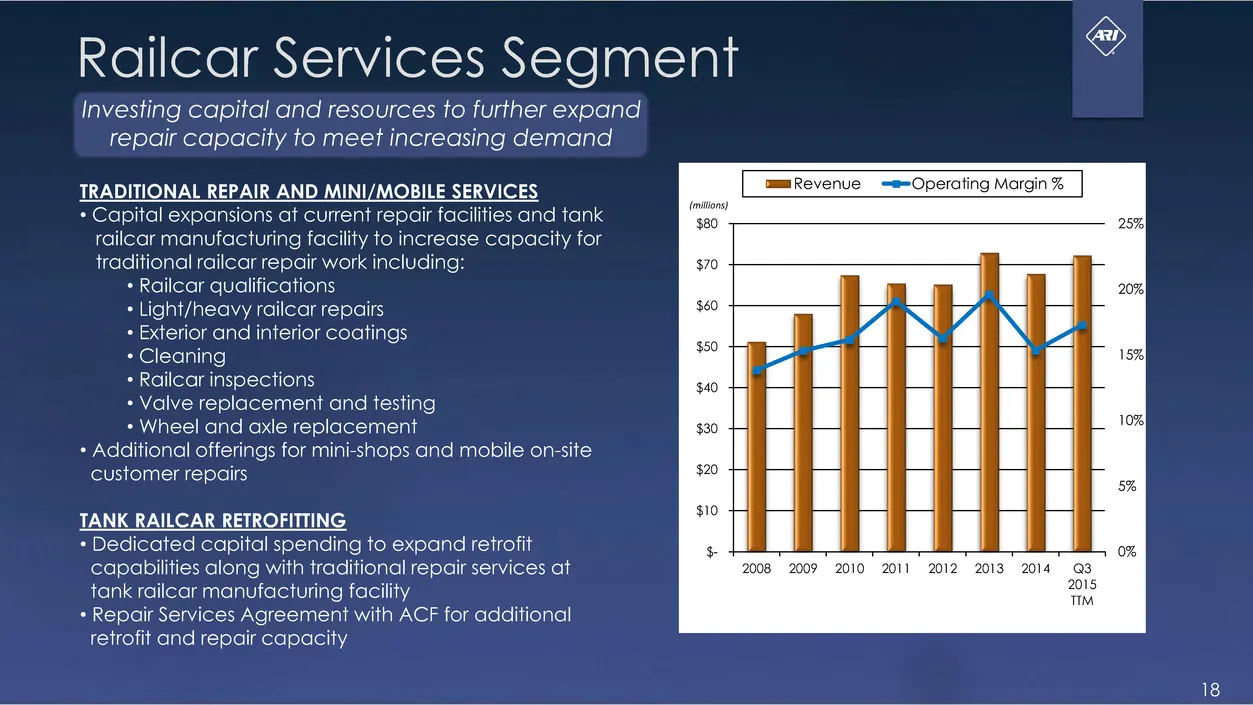
Railcar Services Segment Investing capital and resources to further expand repair capacity to meet increasing demand TRADITIONAL REPAIR AND MINI/MOBILE SERVICES * Capital expansions at current repair facilities and tank railcar manufacturing facility to increase capacity for traditional railcar repa
Slide 19: Supporting the Growth of Demand for Repair Work
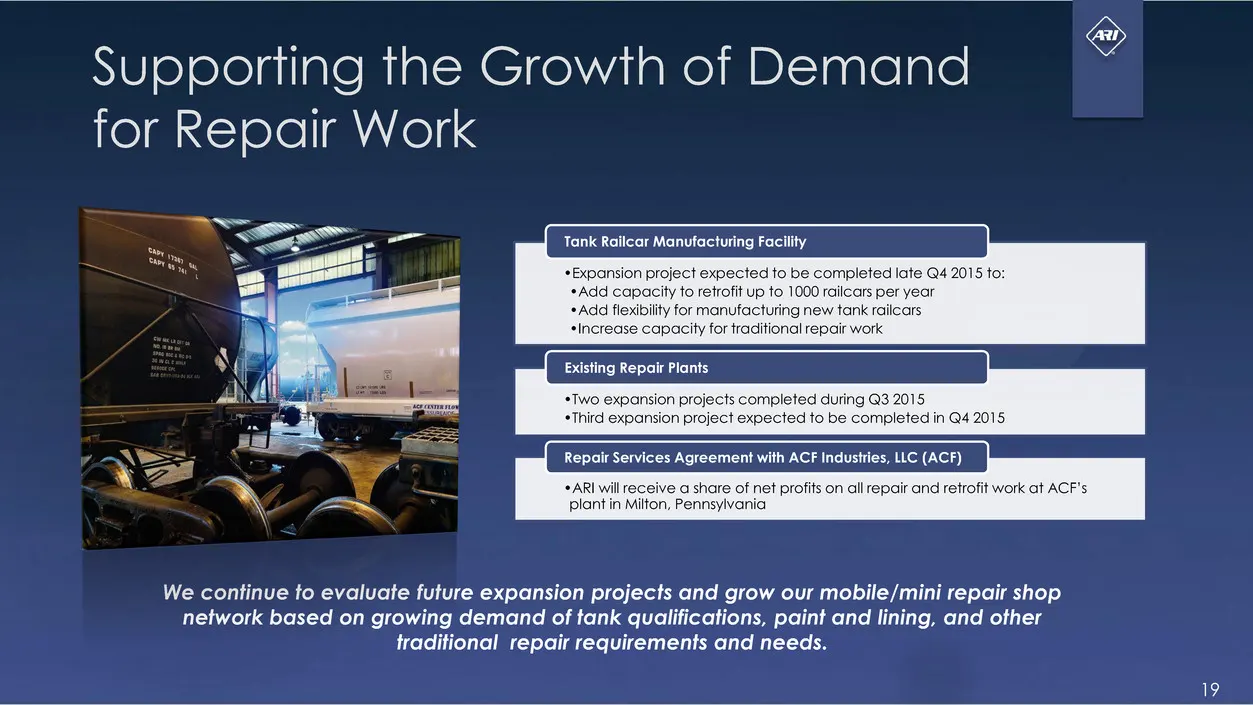
Supporting the Growth of Demand for Repair Work Tank Railcar Manufacturing Facility sansion Breas pleted late S 20154 pC *Add c *Add fle: ject exp “Two uaeinian peo hird Lc (ACF) *ARI will rec of net profits on alll repair and retrofit work jant in alton. ponneyivanie We continue to evaluate future
Slide 20: Growth and Cost Reduction Initiatives
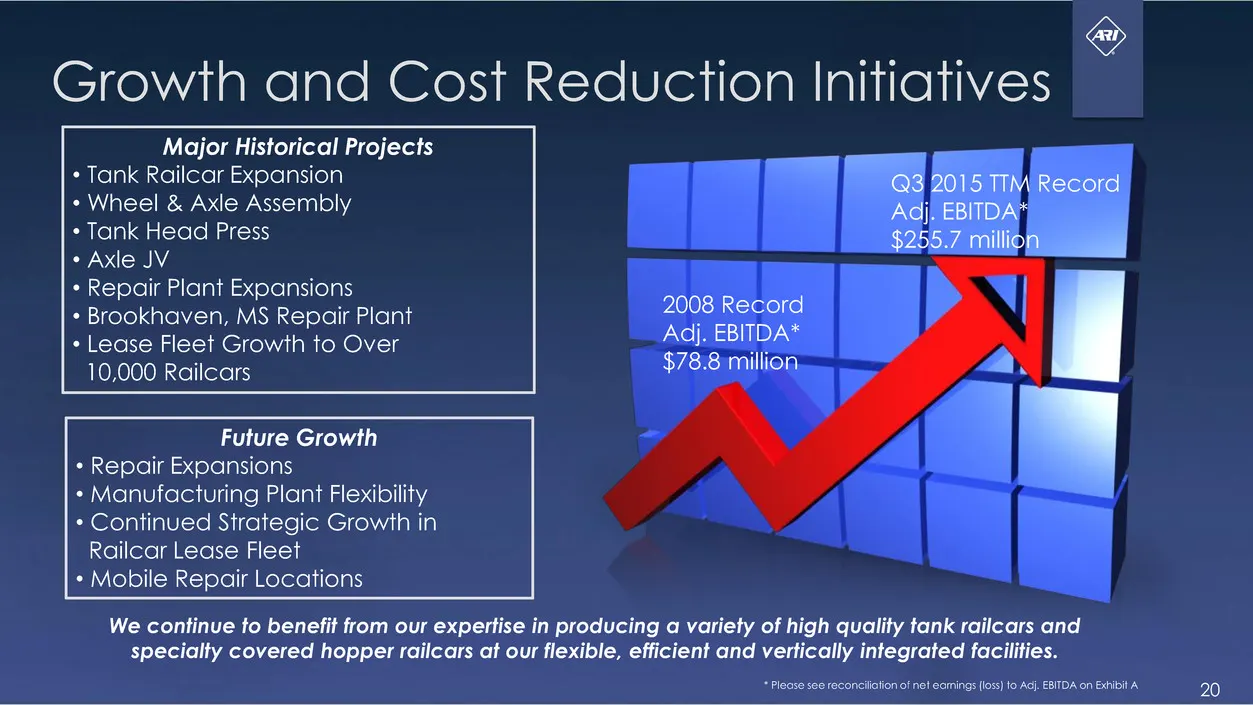
Growth and Cost Reduction Initiatives Major Historical Projects * Tank Railcar Expansion + Wheel & Axle Assembly + Tank Head Press + Axle JV * Repair Plant Expansions + Brookhaven, MS Repair Plant + Lease Fleet Growth to Over 10,000 Railcars Future Growth * Repair Expansions + Manufacturing Plant Fl
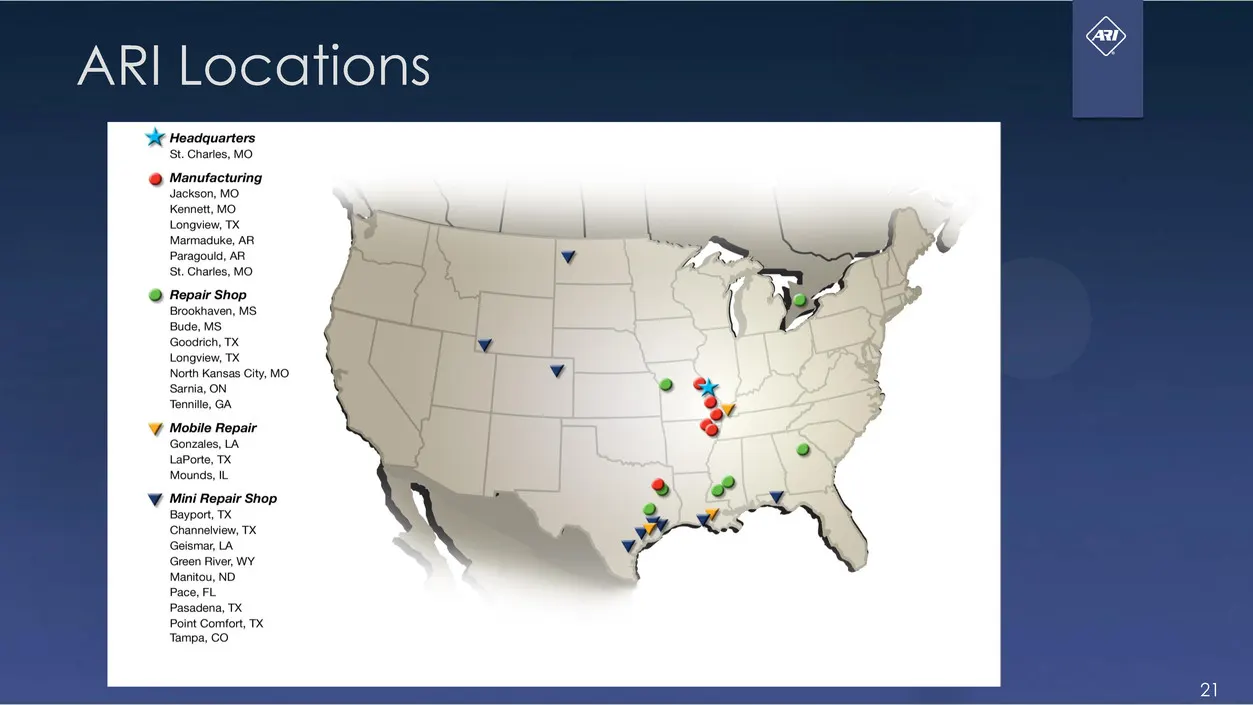
Slide 21: ARI Locations
ARI Locations ie Headquarters St. Charles, MO © Mentecaring Mobite Repair Gonzales, tarete, TX Mounds, IL ie Read hop
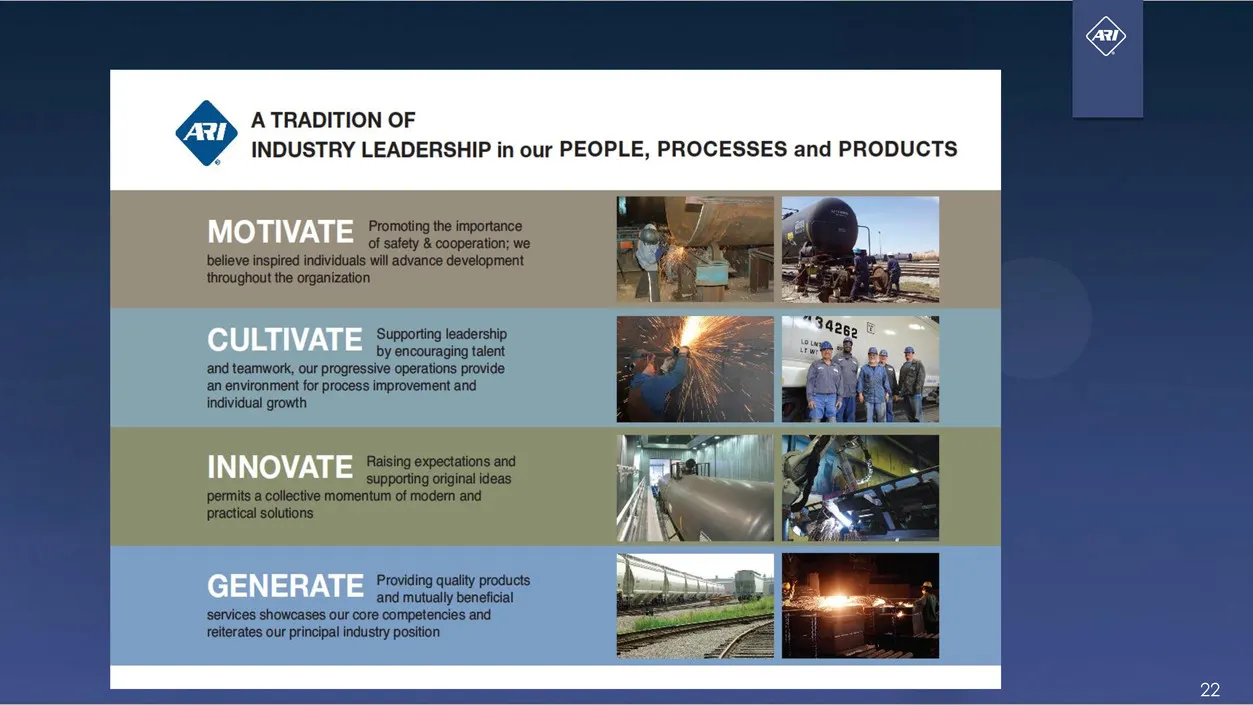
Slide 22: A Tradition of Industry Leadership
A TRADITION OF INDUSTRY LEADERSHIP in our PEOPLE, PROCESSES and PRODUCTS MOTIVATE ‘an environment for process improvement and individual growth INNOVATE Providing quality poate and mutually ben services showcases our core competencies sap reiterates our principal industry position
Slide 23: Objectives and Long-Term Strategies
Objectives and Long-Term Strategies We are focused on meeting the demands of the industry by offering new designs, innovative thinking, and efficient production. Integrated. Manufacturing * Maintain production levels + Adapt to the evolving demands of the industry + Respond to tank railcar regulatio
Slide 24: Objectives and Long-Term Strategies (continued)
Objectives and Long-Term Strategies (continued) g our business We remain. further model 70a railcar leasing andrailcar services. Railcar Leasing * Continue'to. add railcars to our domestic fleet + Backlog (as of September 30, 2015) includes 821 railcars to be manufactured for lease + Target a balanc
Slide 25: Strong Financial Profile
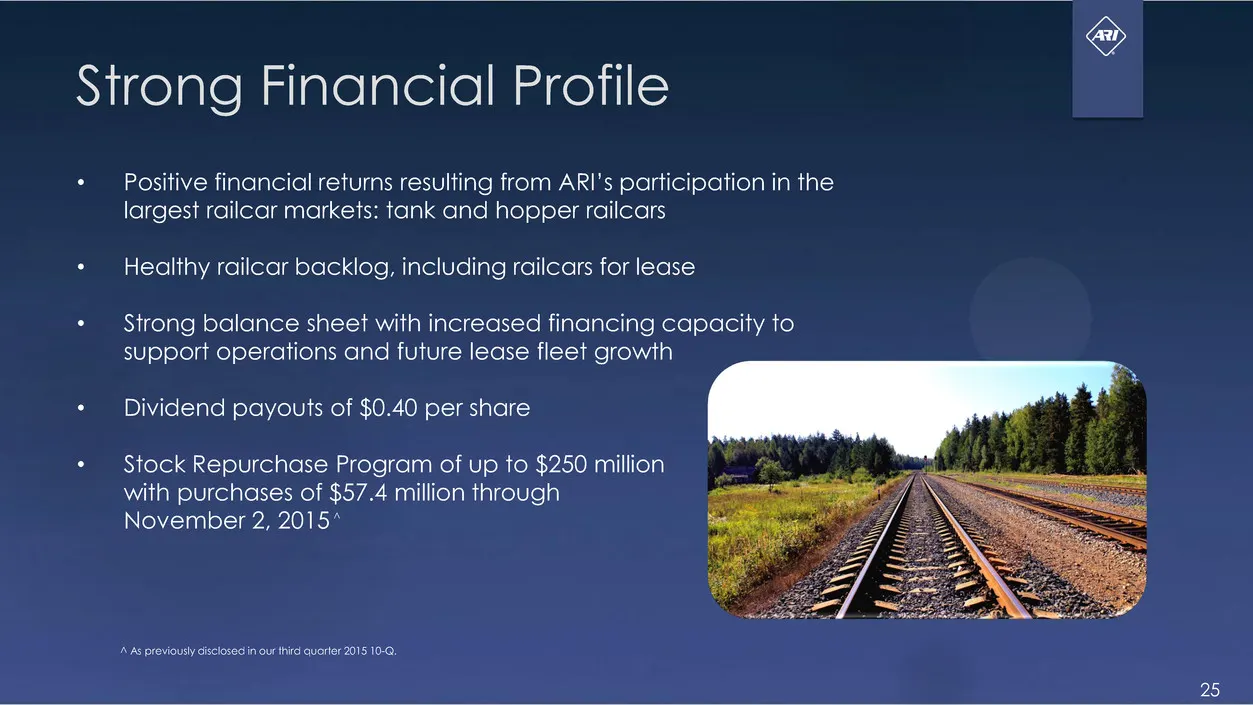
Strong Financial Profile + Positive financial returns resulting from ARI’s participation in the largest railcar markets: tank and hopper railcars + Healthy railcar backlog, including railcars for lease * Strong balance sheet with increased financing capacity to support operations and future lease fl
Slide 26: Our Financial History
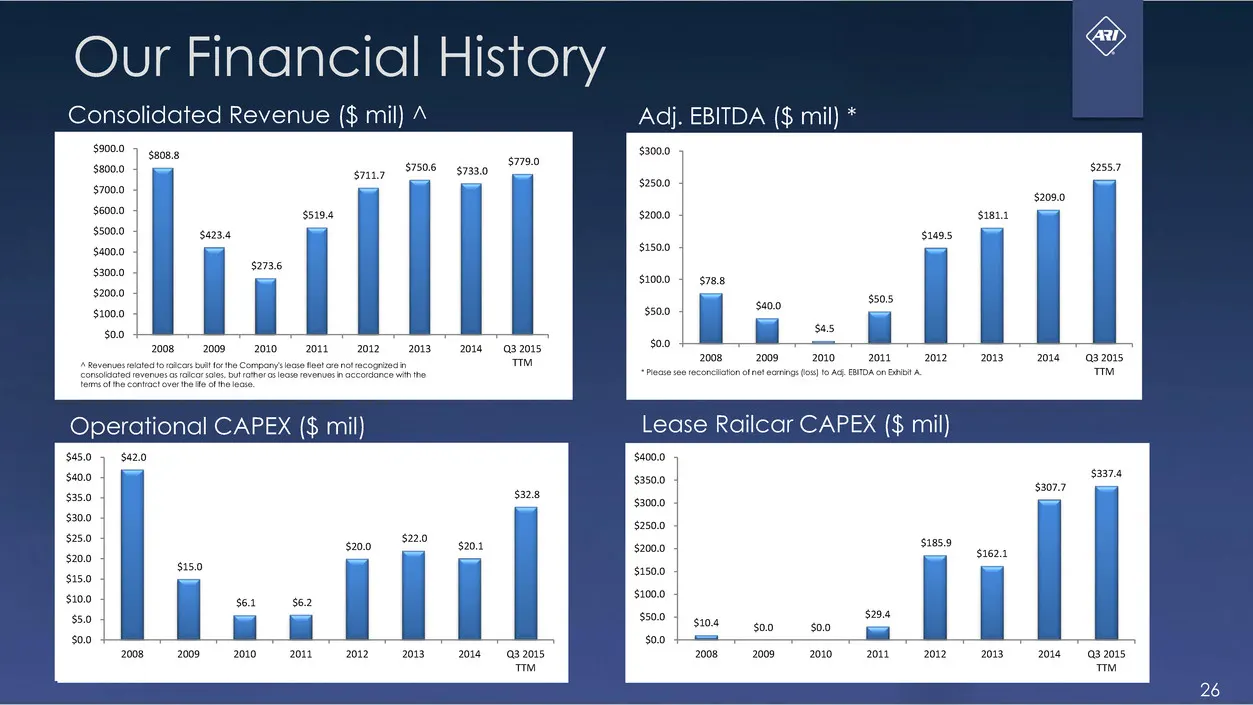
Our Financial History Consolidated Revenue ($ mil) 4 Adj. EBITDA ($ mil) * 3779.0 sniz 57508 $733.0 2009 2010 011-«2012,-S2013,S 20143 2015 TM 2008 = 2009-2010 201.2012, 2013. 2018 <ercted rene ac samba foher oan roenon natcoserce mnie + Raose soe reconciaton ote erring (210A, ERIDA 00 NH A 2011-201
Slide 27: Quarterly Financial Comparison
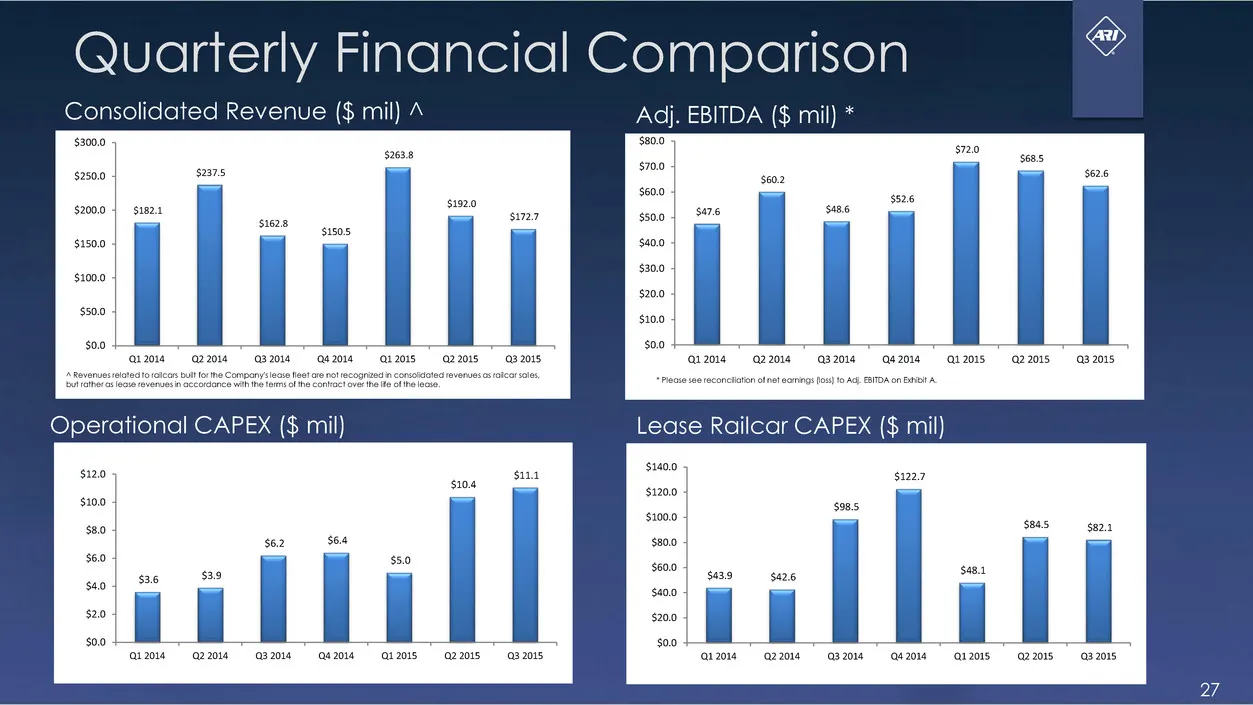
Quarterly Financial Comparison Consolidated Revenue ($ mil) 4 Adj. EBITDA ($ mil) * seo 12014 a2 20132014 as 2014 i215 201532015, 12014 Q22018 3.2014 as 2014 © aI2015.—Q2215 3.2015, *Posesoe econtiaton ote! earings os) 10 Ad, SIDA on Bia A Operational CAPEX ($ mil) i204 2201432014 aa zo14 = ai 01s 2
Slide 28: Exhibit A — EBITDA Reconciliation
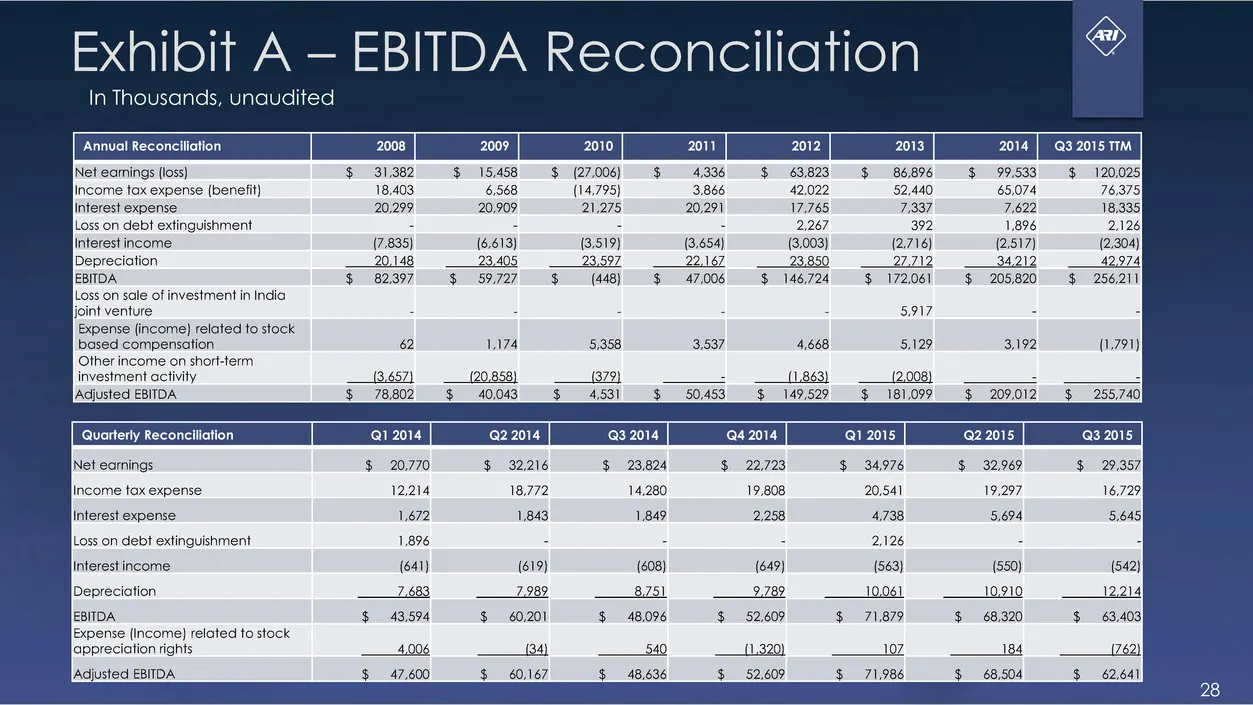
Exhibit A — EBITDA Reconciliation In Thousands, unaudited ‘Annual Reconciliation a ar (loss) $ SS saa (benefit) nica debt SE iar income Depreciation EBITDA $ PS eneae cinema joint ventu Expense incre) ielatedito sock ased 31,382 18,403 20,299 (7.835) 20.14 82,397 OtGerIncorS ST ee term investment ac
Slide 29: Exhibit A — EBITDA Reconciliation
& Exhibit A — EBITDA Reconciliation EBITDA represents net earnings (loss) isle jigs (at aise (Revs) hla area (Cte), (aes a ae Sunmueret and depreciation of property, plant and equipment. The Company believes EBITDA is useful to investors in evaluating ARI’s operating mance fared to that of other com
Slide 30: A Tradition of Industry Leadership
A Tradition of Industry Leadership
Source: SEC EDGAR · 8-K filed Nov 6, 2015
More decks from American Railcar Industries Inc
 Q3 2018 Earnings Presentation19 slides · Oct 30, 2018
 Investor Presentation (August 2018)26 slides · Aug 24, 2018
 Q2 2018 Earnings Presentation19 slides · Aug 1, 2018
 Q1 2018 Earnings Presentation18 slides · May 1, 2018
 Q4 2017 Earnings Presentation19 slides · Feb 23, 2018
 Cowen conference 201824 slides · Feb 6, 2018