Mellon Financial — Citigroup 2007 Financial Services Conference
35 slides from Mellon Financial's conference presentation, Feb 1, 2007
Slide 1: A Global Financial Services Growth Company
A Global Financial Services Growth Company Citigroup 2007 Financial Services Conference Thomas A. Renyi Chairman & CEO, The Bank of New York January 31, 2007 Update on
Slide 2: Disclosure and Cautionary Statement
Disclosure and Cautionary Statement The information presented herein may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements are based upon the Company’s current beliefs and expectations and are subject to significant risks
Slide 3: The Bank of New York Mellon: Strategic, Financial, Operational, Integration
Strategic Financial Operational Integration Global leadership in Securities Servicing and Asset Management Strongly accretive transaction Excellent global growth opportunities Highly complementary businesses with strong leadership positions Focused and experienced management team Disciplined and tho
Slide 4: Compelling Strategic Attributes
Strong Market Positions in High Growth Businesses Business & Geographic Diversification Compelling Strategic Attributes Capitalizing on the growth of global financial markets * As of 12/31/06 - #1 global custodian with over $17 trillion in AUC* - Top 10 asset manager globally and Top 5 in the U.S .
Slide 5: Financially Compelling Low Risk Transaction
Financially Compelling Low Risk Transaction Compelling Financial Rationale Capitalizing on the growth of global financial markets - Immediately accretive on a cash basis to all shareholders and on a GAAP basis in 2008 - Significant excess capital generation allows for meaningful reinvestment in orga
Slide 6: Balanced & Complementary Business Lines
Business Line ($bn) (%) Asset Management & Wealth Management 1.2 Asset Servicing 0.9 Issuer Services 1.0 Treasury Services & Clearing Services 0.9 Other (0.2) (5) Total $3.8 Balanced & Complementary Business Lines Pro Forma Revenue Mix ¹ Pro Forma Pre-Tax Earnings Mix ¹ High Return, Low Capital Inte
Slide 7: Meaningful Revenue Synergy Opportunities
Meaningful Revenue Synergy Opportunities ( not assumed in financial model) Accelerates Revenue Growth and Enhances Operating Leverage Breadth of Mellon’s asset management products and services to The Bank of New York’s securities servicing clients Breadth of The Bank of New York’s global markets pro
Slide 8: Integration—Thorough and Thoughtful
Integration—Thorough and Thoughtful Process A True Merger—combination of best of both companies “Lose no Customers” philosophy Commitment to maintaining our #1 customer service standards/levels Continued emphasis on risk management and compliance Open communication with all employees Dedicated integ
Slide 9: Integration Planning: Dedicated & Disciplined Process
Merger announced and integration planning teams established Organizational design established Ready to Win December/January February/March Multiple integration planning teams across businesses and shared services The Bank of New York Mellon Integration Planning: Dedicated & Disciplined Process Merge
Slide 10: Highly Complementary Businesses
The Bank of New York Strengths Mellon Strengths BNY Mellon Asset Servicing Highly complementary businesses Combining Best of Breed Resulting in Greater Growth and Efficiency Globally Culture of Quality Service & Delivery Culture of Disciplined Cost Management Financial Institution Relationships Pens
Slide 11: Complementary Client Bases
BNY Mellon Asset Servicing Complementary client bases Increased Scale and Market Leadership Leading to Greater Growth and Efficiency Globally Hedge Funds Broker Dealers ETFs / UITs Insurance Companies Central Banks Mutual Funds U.S. Public Funds Endowments & Foundations Corporate Pensions Combined M
Slide 12: The Bank of New York Mellon: Delivering Superior Shareholder Value
The Bank of New York Mellon Delivering superior shareholder value through accelerated growth A Global Financial Services Growth Company Strategic Financial Operational Integration Global leadership in Securities Servicing and Asset Management Strongly accretive transaction Excellent global growth op
Slide 13: The Bank of New York Mellon Corporation
The BANK of NEW YORK MELLON Corporation
Slide 14: The Bank of New York – Gerald L. Hassell
The Bank of New York Citigroup 2007 Financial Services Conference Gerald L. Hassell, President January 31, 2007
Slide 15: Disclosure and Cautionary Statement
Disclosure and Cautionary Statement The information presented herein may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements are based upon the Company’s current beliefs and expectations and are subject to significant risks
Slide 16: 2006: A Watershed Year – Strategic Initiatives
A Global Financial Services Growth Company 2006: A Watershed Year Strategic Initiatives Successfully completed: Retail / Corporate Trust asset swap transaction BNY ConvergEx transaction Announced merger with Mellon Financial, creating the global leader in securities servicing and asset management
Slide 17: Generate attractive long-term returns for shareholders
Generate attractive long-term returns for shareholders Model focused on securities servicing and asset management Emphasis on higher-growth, higher-margin businesses where we have scale, skill and competitive advantages Improved corporate risk profile through reduced exposure to credit portfolio Pos
Slide 18: 2006: A Watershed Year – Financial Performance
A Global Financial Services Growth Company 2006: A Watershed Year Financial Performance Strong financial results demonstrating the success of our business model Businesses performed well across the board Providing excellent momentum into 2007 Superior shareholder returns
Slide 19: 2006 Total Return to Shareholders
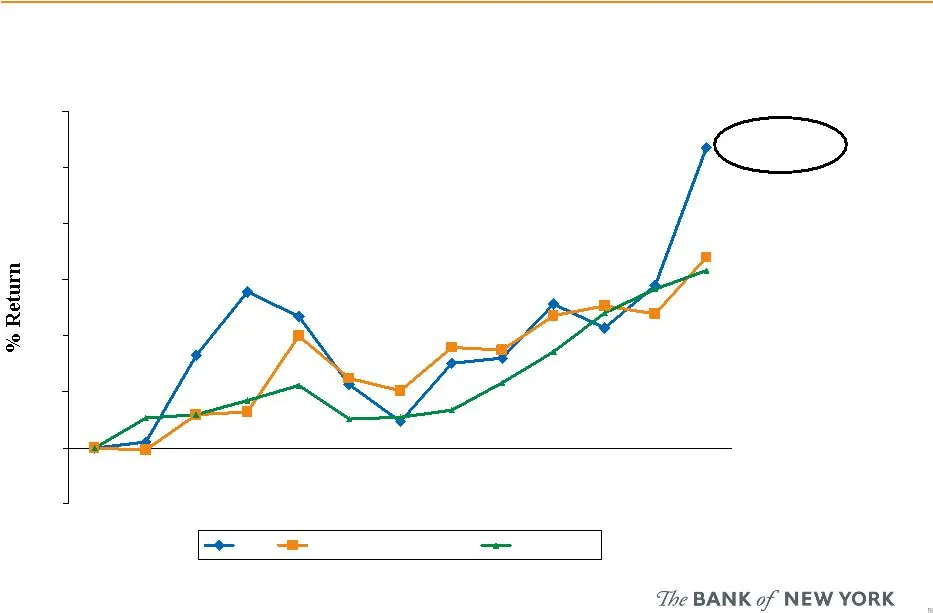
2006 Total Return to Shareholders -5 Dec-05 Mar-06 Jun-06 Sep-06 Dec-06 BK KBW Bank Index S&P 500 + 17% BKX + 27% BK + 16% S&P 500
Slide 20: Annual EPS
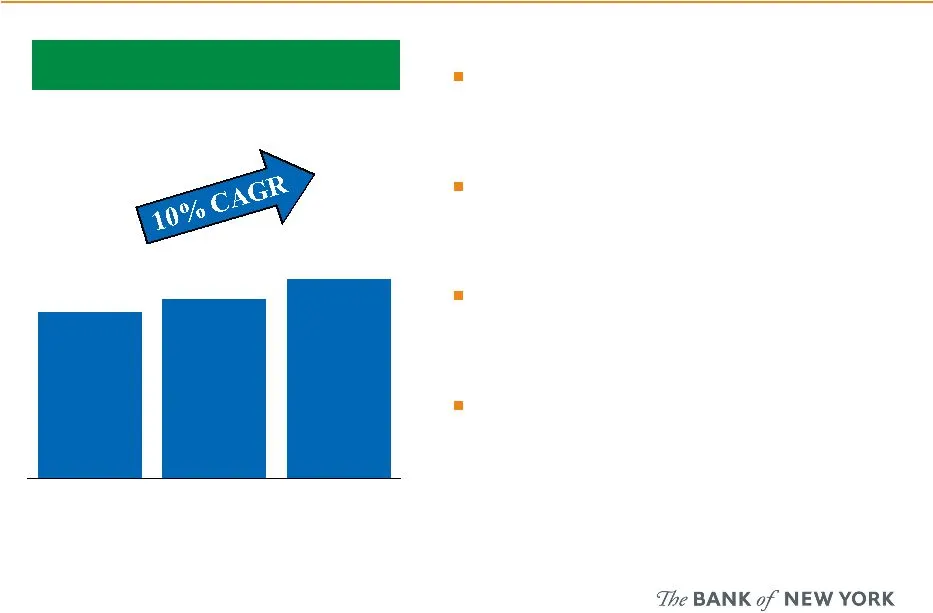
Annual EPS* Delivering Strong Performance $1.88 $2.03 $2.26 Annual EPS* * Adjusted Operating Basis (see reconciliation tables in Appendix) Strong fee growth across all businesses Customer activity generating deposits / net interest income Improved asset quality and lower credit costs International n
Slide 21: Growing Base of Assets to Service and Manage
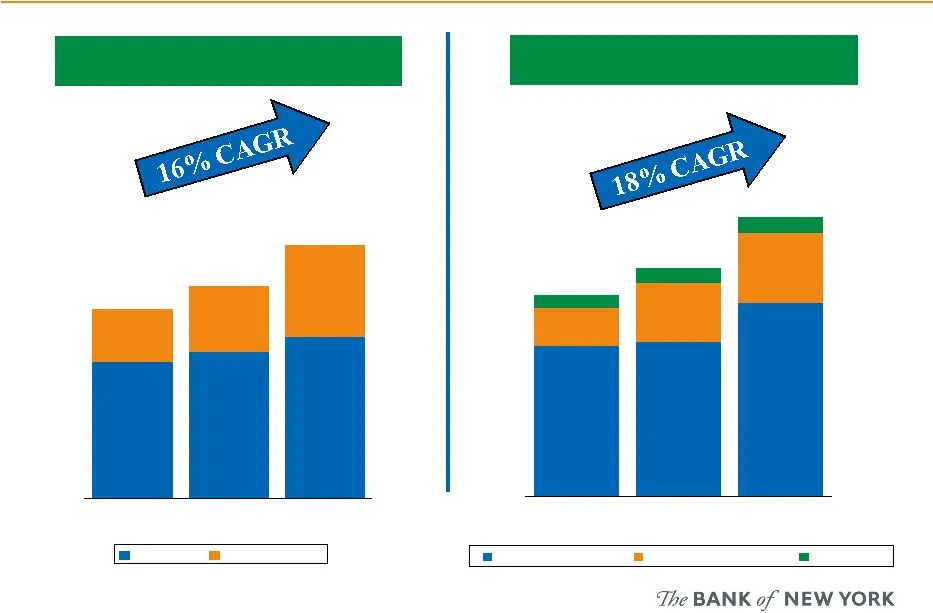
$7.0 $7.5 $8.3 $2.7 $3.4 $4.7 Assets Under Custody $102 $105 $131 $26 $40 $48 $9 $10 $11 Assets Under Management Growing Base of Assets to Service and Manage 12/31/04 12/31/05 12/31/06 Domestic Cross-border Assets Under Custody (in trillions) 12/31/04 12/31/05 12/31/06 Asset Mgmt Sector ST Investmen
Slide 22: Solid 4Q Performance Across All Business Lines
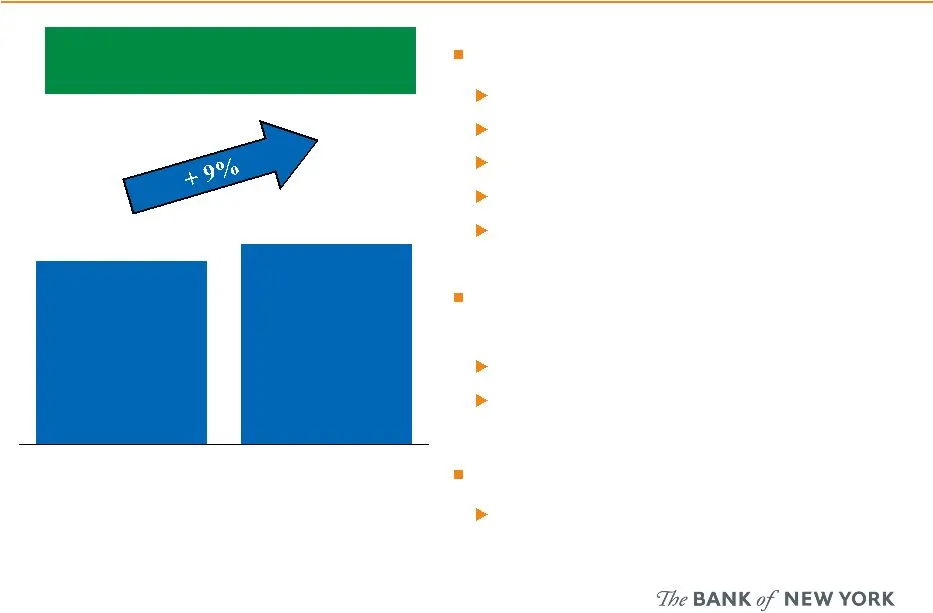
EPS 4Q06 vs. 4Q05* Solid 4Q Performance Across All Business Lines Strong fee growth Pvt. Banking / Asset Mgmt + 42% Issuer Services + 24%** Broker-dealer Services + 16% Investor Services + 10% Execution & Clearing + 8%*** Improved net interest income / net interest margin NII + 31% NIM + 31 bps Refl
Slide 23: Global Trends Create Opportunities to Drive Growth
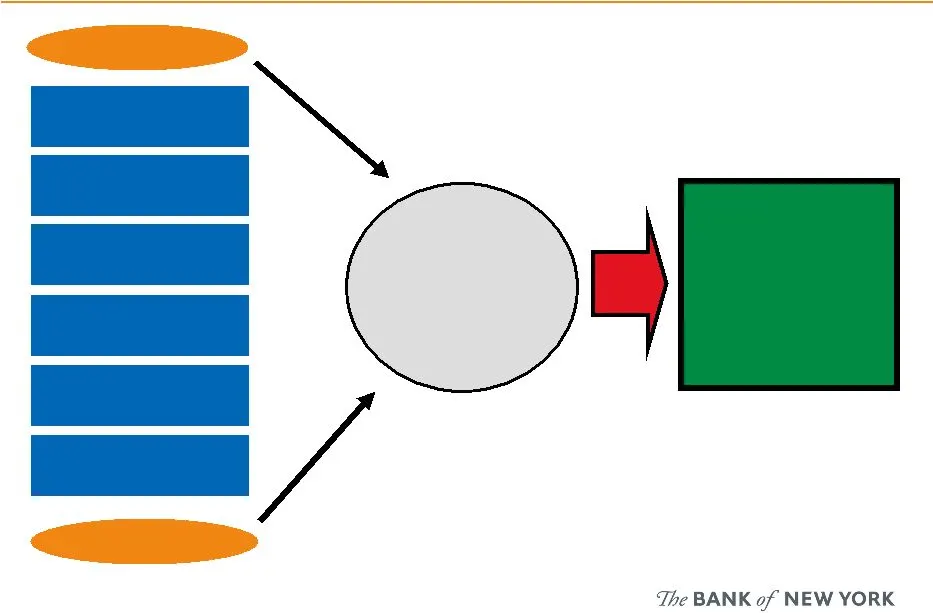
Pressure on Retirement Provision Globalization of Investment Industry Changing Regulatory Environment Financial Market Consolidation Asset Management Profit Challenge Search for Enhanced Performance Value Creation Asset Owners Asset Managers Global Trends Create Opportunities to Drive Growth Asset O
Slide 24: Solutions to Meet Broad Customer Needs
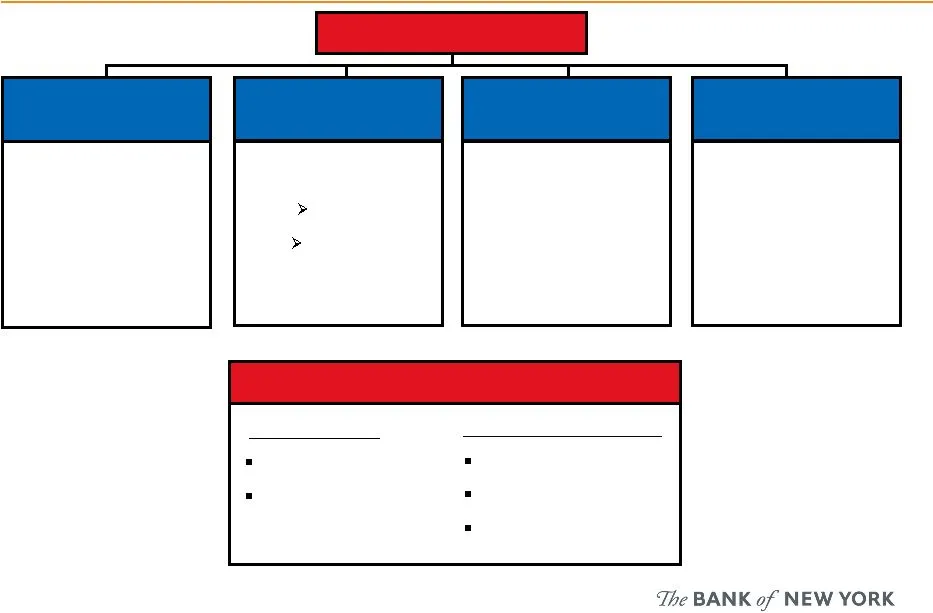
Investor & Broker- Dealer Treasury Services Execution & Clearing Services Issuer Services Institutional Services Private Bank & Asset Management Solutions to Meet Broad Customer Needs • Global Custody • Global Fund Services • Securities Lending • Securities Clearance • Collateral Management • Pershi
Slide 25: Major Growth Opportunities
Collateral Management Hedge Fund Services Depositary Receipts European Investor Services Exchange Traded Funds (ETFs) Registered Investment Advisors (RIAs) Major Growth Opportunities Growth Opportunities
Slide 26: Major Growth Opportunities
Collateral Management Hedge Fund Services Depositary Receipts European Investor Services Exchange Traded Funds (ETFs) Registered Investment Advisors (RIAs) Major Growth Opportunities Growth Opportunities
Slide 27: Major Growth Opportunities
Collateral Management Hedge Fund Services Depositary Receipts European Investor Services Exchange Traded Funds (ETFs) Registered Investment Advisors (RIAs) Major Growth Opportunities Growth Opportunities
Slide 28: Major Growth Opportunities
Collateral Management Hedge Fund Services Depositary Receipts European Investor Services Exchange Traded Funds (ETFs) Registered Investment Advisors (RIAs) Major Growth Opportunities Growth Opportunities * Source: Investment News , 1/15/07
Slide 29: Momentum in Global Corporate Trust
Momentum in Global Corporate Trust Successfully integrating new Corporate Trust business into an already powerful base Expanded presence in global, structured products and CDOs Continued strength evident in fourth quarter results: Existing corporate trust revenue increased 18% Annualized revenue run
Slide 30: Summary – The "New" Bank of New York
A Global Financial Services Growth Company Summary – The “ New ” Bank of New York Sharper focus Enhanced growth and profitability dynamics Improved risk profile Highly confident in ability to deliver superior performance
Slide 31: The Bank of New York
The BANK of NEW YORK
Slide 32: Appendix
Appendix
Slide 33: Reconciliation Tables
$ in Millions 2004 Reported 2004 Normalized Reconciliation Tables Slides 7, 9 Three Months Ended December 31, 2006 Twelve Months Ended December 31, 2006 (In dollars) Continuing Operations Discontinued Operations Adjusted (1) Continuing Operations Discontinued Operations Adjusted (1) As Reported 0.56
Slide 34: Reconciliation Tables
$ in Millions 2004 Reported Non GAAP Adjustments 2004 Normalized Non GAAP 4,074 (48) 4,122 Total 1,760 (38) 1,798 All Other 2,314 (10) 2,324 Salaries & Benefits (70) Banking Related/Other - Global Payment Services - FX & Other Trading - PCS & Asset Management 2,858 - 2,858 Total Fee Revenue - Broker
Slide 35: Reconciliation Tables
2004 Reported 2004 Normalized Reconciliation Tables Slide 9 Percent Inc / (Dec) (in millions) Quarter 4Q06 vs. 4Q06 vs. 4Q06 3Q06 4Q05 3Q06 4Q05 Execution & Clearing Fees Continuing Operations (12)% (19)% BNY ConvergEx (66) (82) Pro Forma 12% 8% Issuer Services Continuing Operations 76% 99% Acquired
Source: SEC EDGAR · 425 filed Feb 1, 2007
More decks from Mellon Financial Corp
 Bank of New York — Merger or Acquisition (December 2006)34 slides · Dec 19, 2006
 Mellon Financial — Merger or Acquisition (December 2006)34 slides · Dec 19, 2006
 Mellon Financial — Merger or Acquisition (December 2006)34 slides · Dec 4, 2006
 Q4 2005 Earnings Presentation18 slides · Jan 24, 2006
 Q3 2005 Earnings Presentation20 slides · Oct 24, 2005
 Q2 2005 Earnings Presentation19 slides · Jul 22, 2005