Geneva Acquisition — SPAC Merger (January 2009)
41 slides from Geneva Acquisition's SPAC merger presentation, Jan 13, 2009
Slide 1: India Steel & Metals Corp.
* ndia Steel & Metals Corp.
Slide 2: Table of Contents
Table of Contents 1. Introduction 2. Overview of Indian Steel Industry 3. The ProForma Company — India Steel & Metals Corp. 4. Strategic Growth Plan and Forecast 5. Transaction Overview and Merger with Geneva Appendix
Slide 3: Safe Harbor Statement
Safe Harbor Statement Certain statements in this presentation constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, as amended. When used in this press release, words such as "will," "believe," "expect," "anticipate," "encouraged" and simil
Slide 4: Information about Solicitation
Information about Solicitation + The attached presentation was filed with the Securities and Exchange Commission as part of the Form 8-K filed by Geneva Acquisition Corporation ("Geneva") on January 12, 2009. Geneva is holding presentations for its stockholders regarding its purchase of Global Hi-Te
Slide 5: Non-GAAP Financial Measures
Non-GAAP Financial Measures This presentation contains disclosure of EBITDA for certain periods, which may be deemed to be a non-GAAP financial measure within the meaning of Regulation G promulgated by the Securities and Exchange Commission. Management believes that EBITDA, or earnings before intere
Slide 6: Net Income & EBITDA Reconciliation
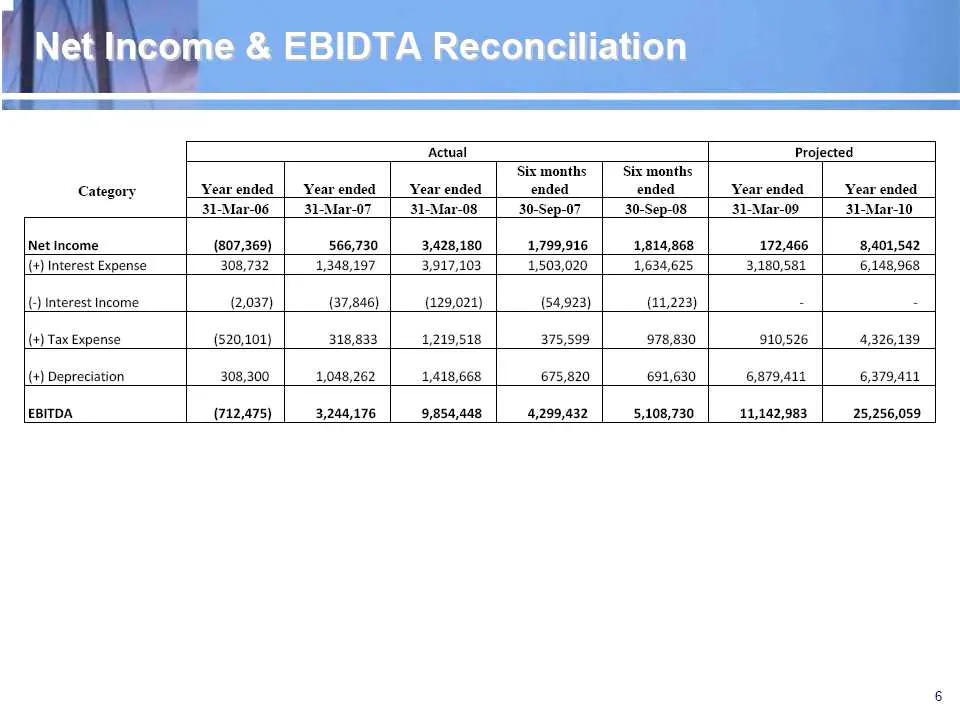
Net Income & EBIDTA Reconciliation Actual Projected Sixmonths | Six months Category Year ended | Yearended_| Year ended ended ended Year ended _| Year ended 31-Mar-06 | 31-Mar-07_| 31-Mar-08 _| 30-Sep-07 30-Sep-08 31-Mar-09 31-Mar-10 Net income (807,369) 566,730 3,428,180 1,799,916 1,814,868 172,466
Slide 7: Introduction
Slide 8: Unique and Exciting Opportunity to Unlock Value
Unique and Exciting Opportunity to Unlock Value = The product portfolio of India Steel & Metals Corp. serves the large and growing Indian infrastructure sector + Structural steel products are used for roads, bridges, commercial buildings, airports, ete. + Significant demand is driven by government f
Slide 9: Overview of India Steel & Metals Corp.
Overview of India Steel & Metals Corp. = Manufacturer of steel products strategically located in Gujarat (northwest India) + 40 miles to 2 major ports * 30 miles to rail access + Regional customer base = Key Products and Customers + Structural steel, billets and sponge iron + Servicing the growing I
Slide 10: Strong Projected Growth
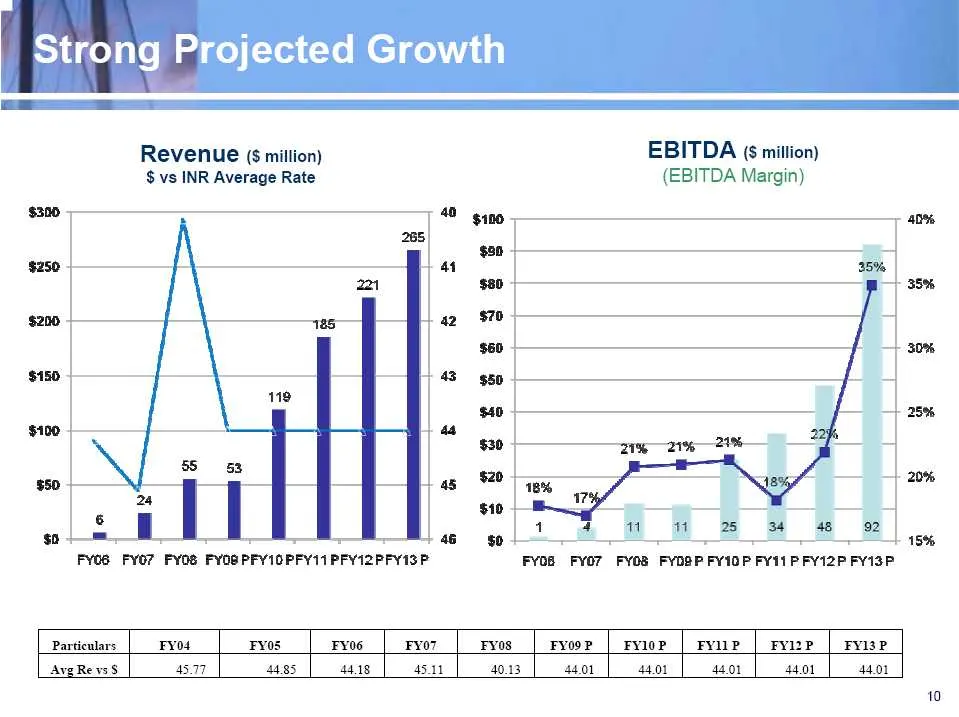
Strong Projected Growth ‘$300 Revenue (5 million) $ vs INR Average Rate EBITDA (5 million) (EBITDA Margin) $100 $50 Cl $250 35% $80 $200 $70 a $60 4 $150. $50 | $40 4 $100 | $20 a $50 boom $10 -| i * i Hh eB 92 so a = | FyYog FYO7 FYO8 FYD8P FYIOP FY11PFY12P FY13P Particulars | FYO4 Fy0s yes | ryor
Slide 11: Indian Steel Industry
Slide 12: Sustainable Driving Forces
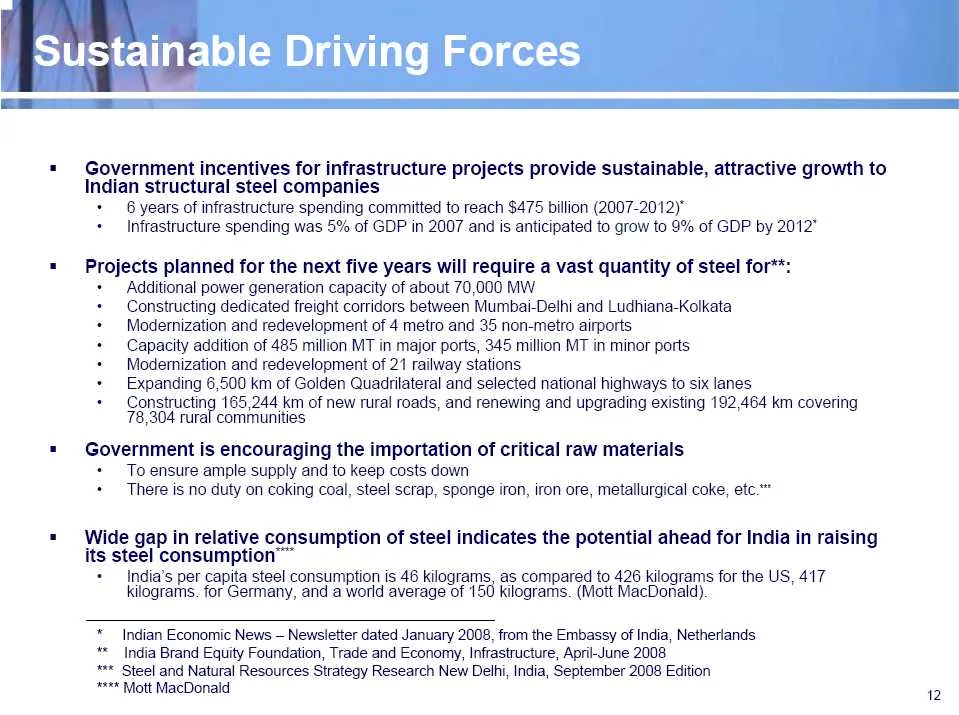
Sustainable Driving Forces « Government incentives for infrastructure projects provide sustainable, attractive growth to Indian structural steel companies + 6 years of infrastructure spending committed to reach $475 billion (2007-2012)" + Infrastructure spending was 5% of GDP in 2007 and is anticipa
Slide 13: Structural Steel Supply and Demand
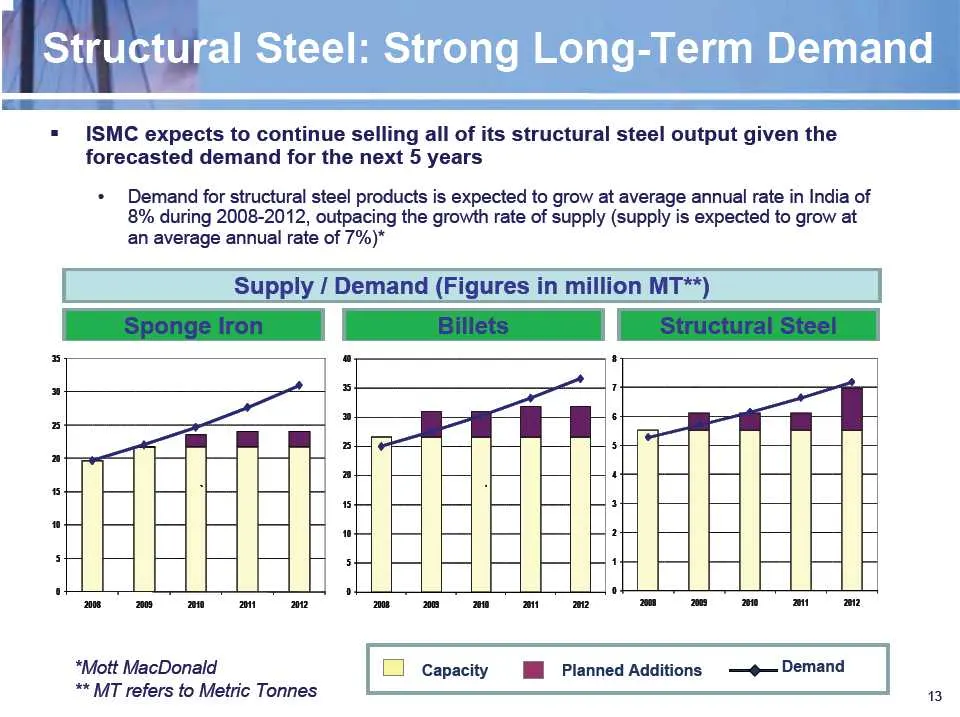
f Struc = ISMC expects to continue selling all of its structural steel output given the forecasted demand for the next 5 years * Demand for structural steel products is expected to grow at average annual rate in India of 8% during 2008-2012, outpacing the growth rate of supply (supply is expected to
Slide 14: Our Company
Slide 15: Structural Steel
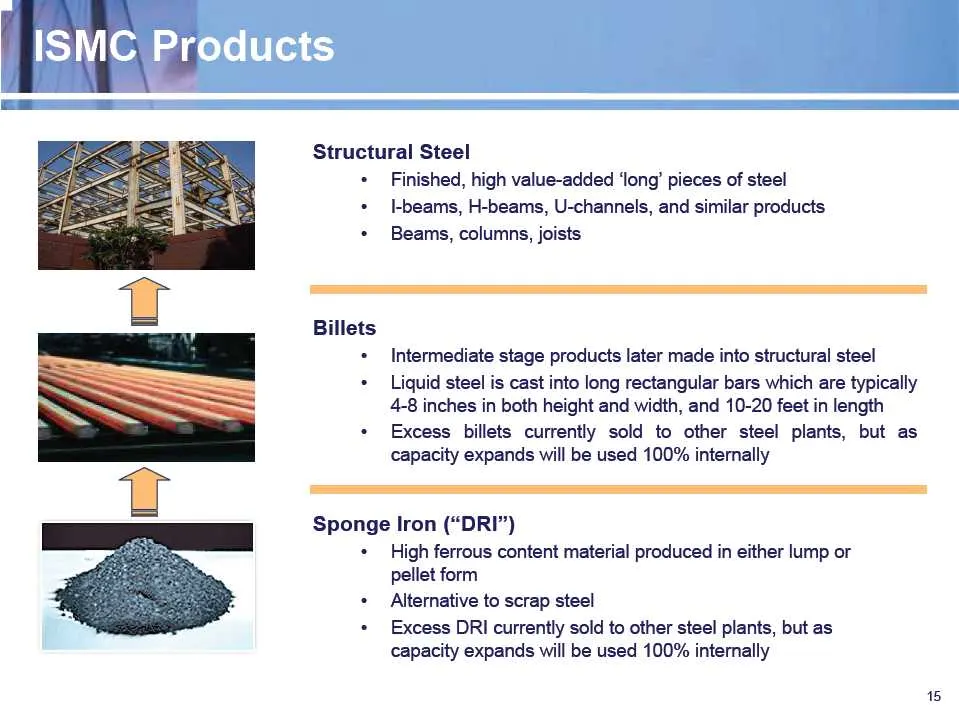
Structural Steel * Finished, high value-added ‘long’ pieces of steel * -beams, H-beams, U-channels, and similar products * Beams, columns, joists * Intermediate stage products later made into structural steel * Liquid steel is cast into long rectangular bars which are typically 4-8 inches in both he
Slide 16: Primarily serving infrastructure projects
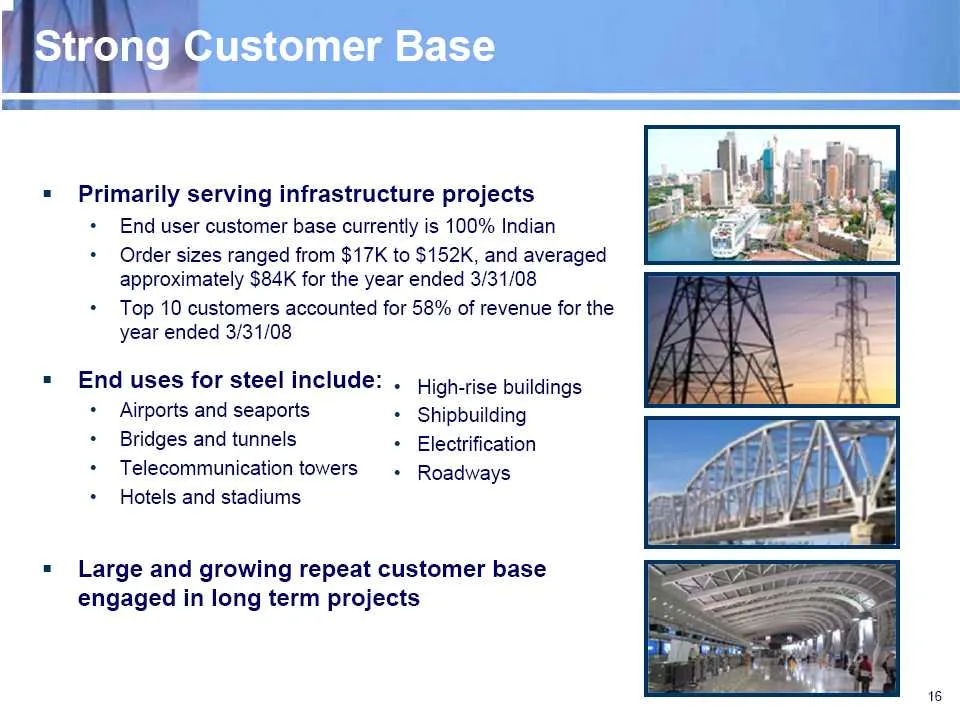
Primarily serving infrastructure projects + End user customer base currently is 100% Indian * Order sizes ranged from $17K to $152K, and averaged approximately $84K for the year ended 3/31/08 * Top 10 customers accounted for 58% of revenue for the year ended 3/31/08 End uses for steel include: . Hig
Slide 17: Competitive Advantages
Competitive Advantages = Current Advantages + An integrated steel plant * Close proximity to railways and sea ports * Flexibility to accommodate individual customer needs + Ready, available and inexpensive local labor pool * New, efficient and expandable state-of-the-art manufacturing facility + Fav
Slide 18: Advantageous Strategic Location
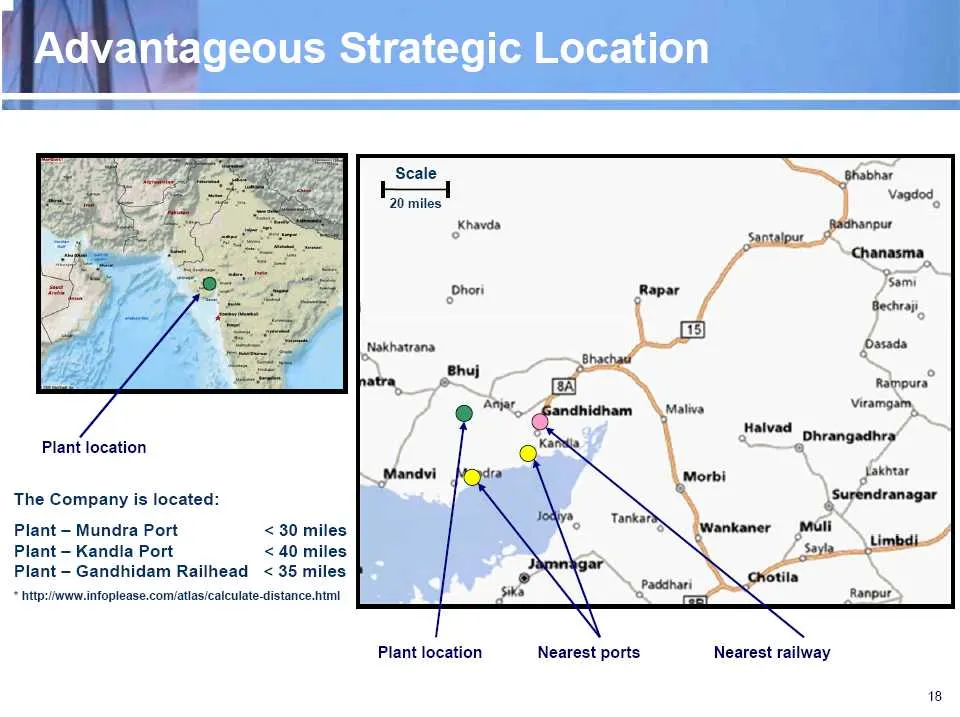
Advantageous Strategic Location Plant location The Company is located: Plant — Mundra Port < 30 miles Plant — Kandia Port < 40 miles Plant - Gandhidam Railhead < 35 miles * http:/iwww.infoplease.com/atlas/catculate-distance.html Plant location Nearest ports Nearest railway 18
Slide 19: Operating management
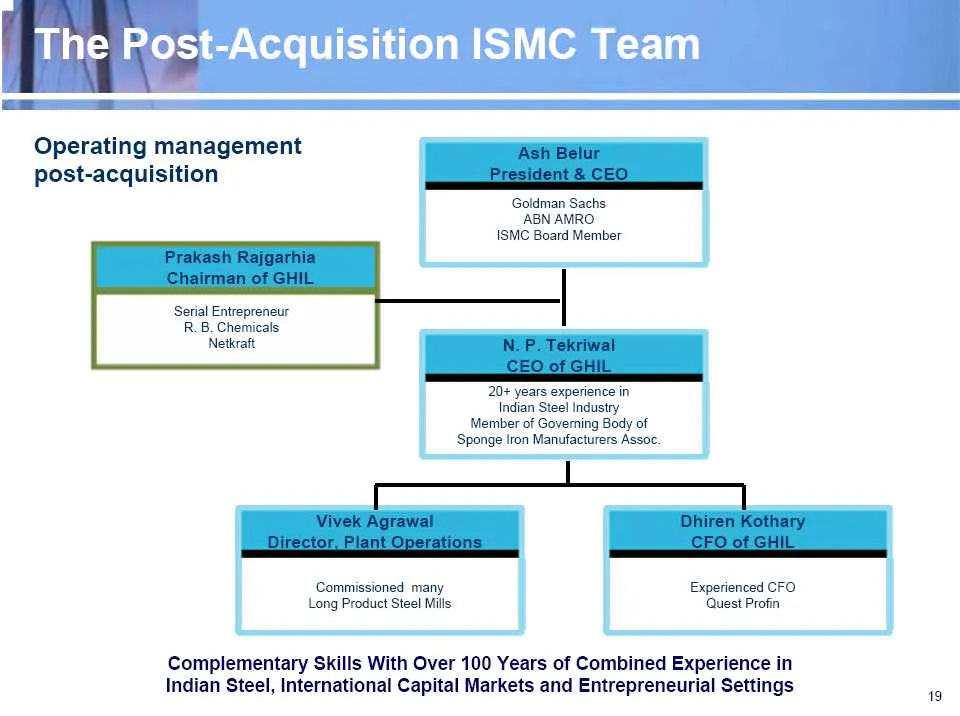
Operating management Ash Belur post-acquisition President & CEO Goldman Sachs Prakash Rajgarhi Chairman of GHIL ABN AMRO ISMC Board Member Serial Entrepreneur R.B. Chemicals Netkraft N. P. Tekriwal CEO of GHIL 20+ years experience in Indian Steel Industry Member of Governing Body of Sponge Iron Manu
Slide 20: Board of Directors and Advisors
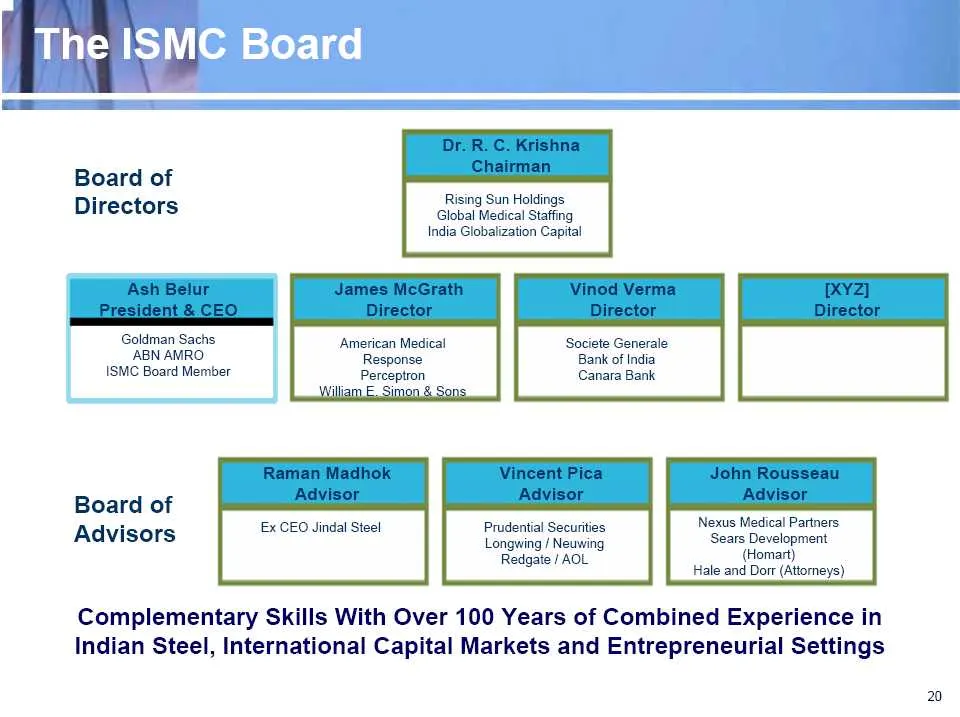
Krishna Board of A Rising Sun Holdings Directors Global Medical Staffing India Globalization Capital Ash Belur Vinod Verma [xyz] president. & CEO Director Director Golgnareaachs American Medical Societe Generale ABN AMRO Response Bank of India ISMC Board Member Perceptron Canara Bank aioe Advisor Ad
Slide 21: Strategic Growth Plan
Slide 22: Increase Capacity Utilization
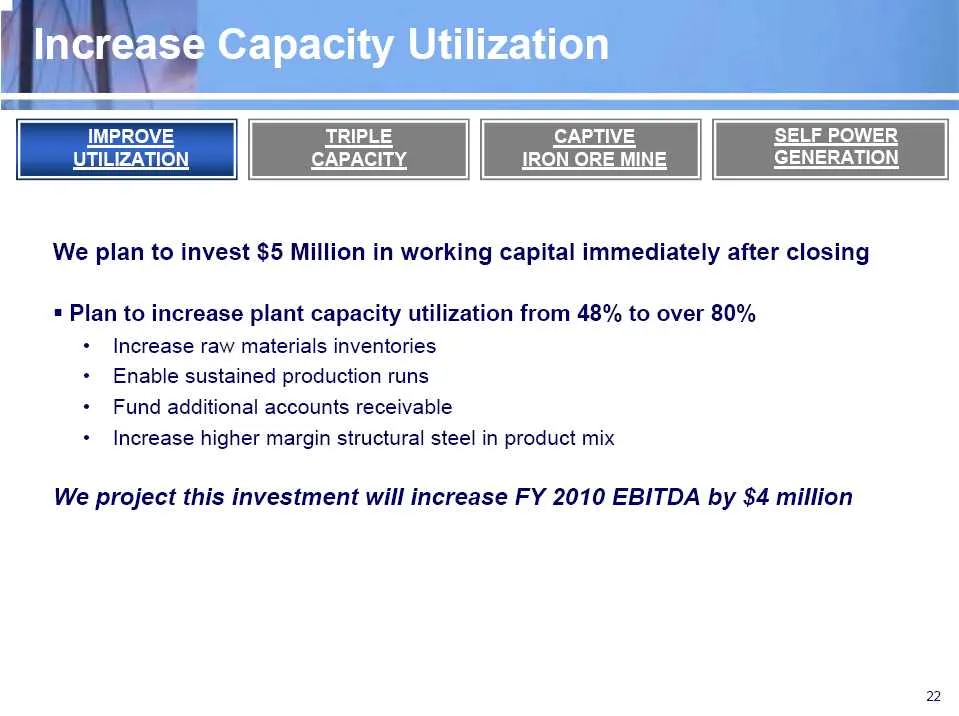
Increase Capacity Utilization We plan to invest $5 Million in working capital immediately after closing = Plan to increase plant capacity utilization from 48% to over 80% * Increase raw materials inventories + Enable sustained production runs + Fund additional accounts receivable + Increase higher m
Slide 23: Capacity Expansion Program
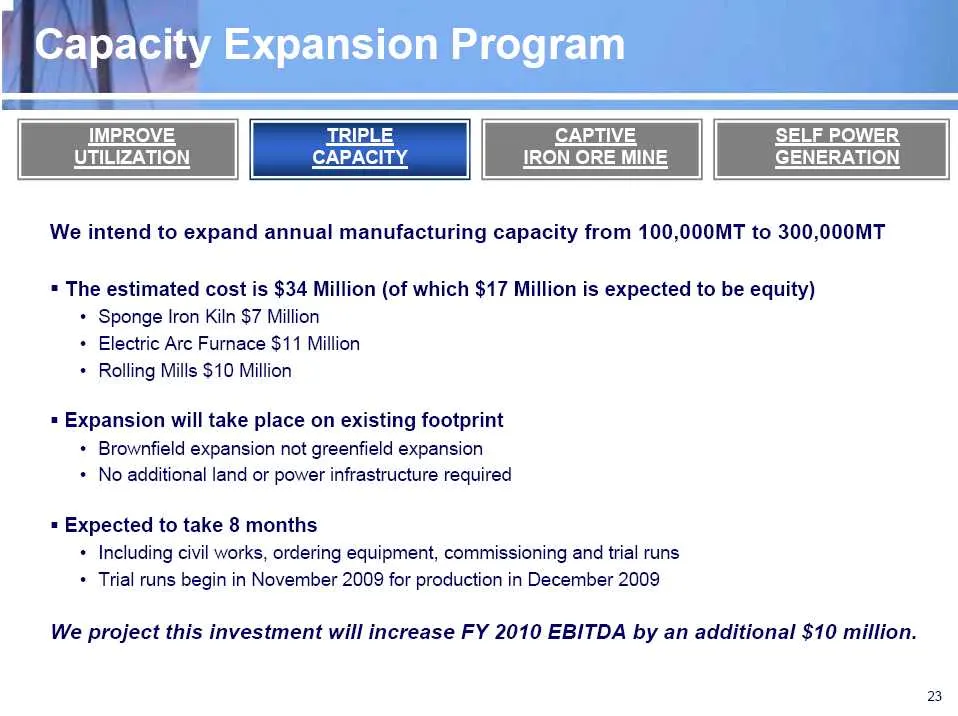
Capacity Expansion Program IMPROVE TRIPLE CAPTIVE Cc ¥ SELF POWER We intend to expand annual manufacturing capacity from 100,000MT to 300,000MT = The estimated cost is $34 Million (of which $17 Million is expected to be equity) * Sponge Iron Kiln $7 Million * Electric Arc Furnace $11 Million * Rolli
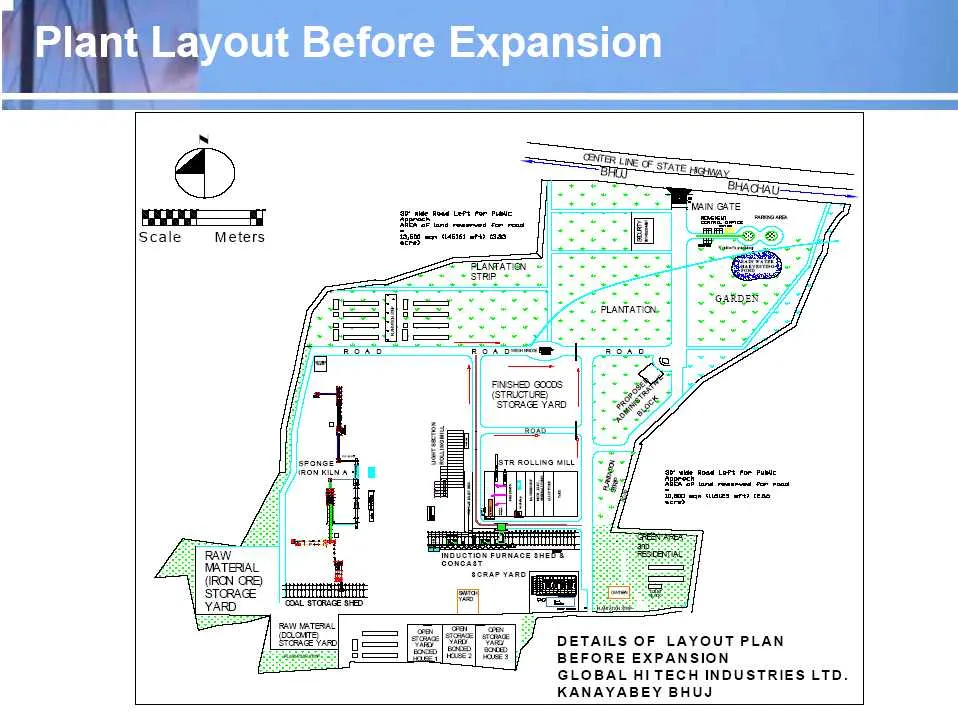
Slide 24: Plant Layout Before Expansion
Plant Layout Before Expansion Scale Meters sh m7 fitttit | See DETAILS OF LAYOUT PLAN Ler ee. BEFORE EXPANSION GLOBAL HI TECH INDUSTRIES LTD. KANAYABEY BHUJ i
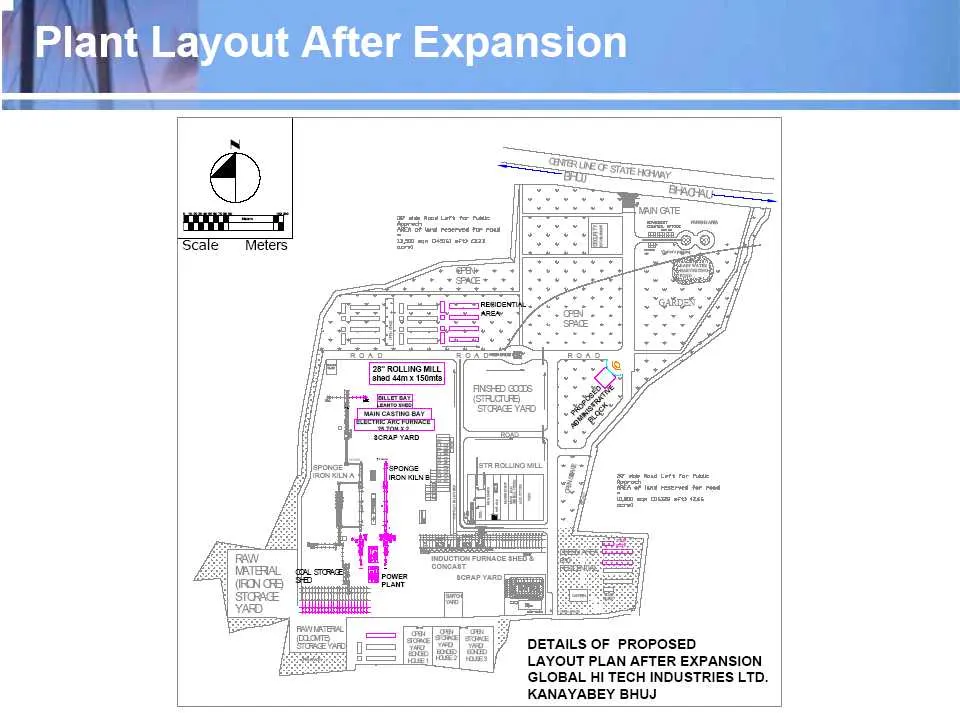
Slide 25: Plant Layout After Expansion
Plant Layout After Expansion Scale Meters DETAILS OF PROPOSED LAYOUT PLAN AFTER EXPANSION GLOBAL HI TECH INDUSTRIES LTD. KANAYABEY BHUJ
Slide 26: Captive Iron Ore Mine
Septive IMPROVE TRIPLE SELF POWER = The Company has received a Prospecting License for an iron ore mine in Chhatarpur District in the state of Madhya Pradesh, India (~600km from Gujarat) + 650 acres in size. Average Fe-content estimated at 62% + Final mining license is expected in March 2010* = = Re
Slide 27: Planned Self Generation Electrical Power Plant
Planned Self Generation Electrical Power Plant IMPROVE TRIPLE IN Cc CAPTIVE SELF POWER = 30 MW of electrical power generation planned + Two 7.5MW Waste Heat Recovery Boilers + One 15 MW Fluidized Bed Combustion unit = Waste heat recovery facility: = Improves the energy efficiency of plant = Qualifie
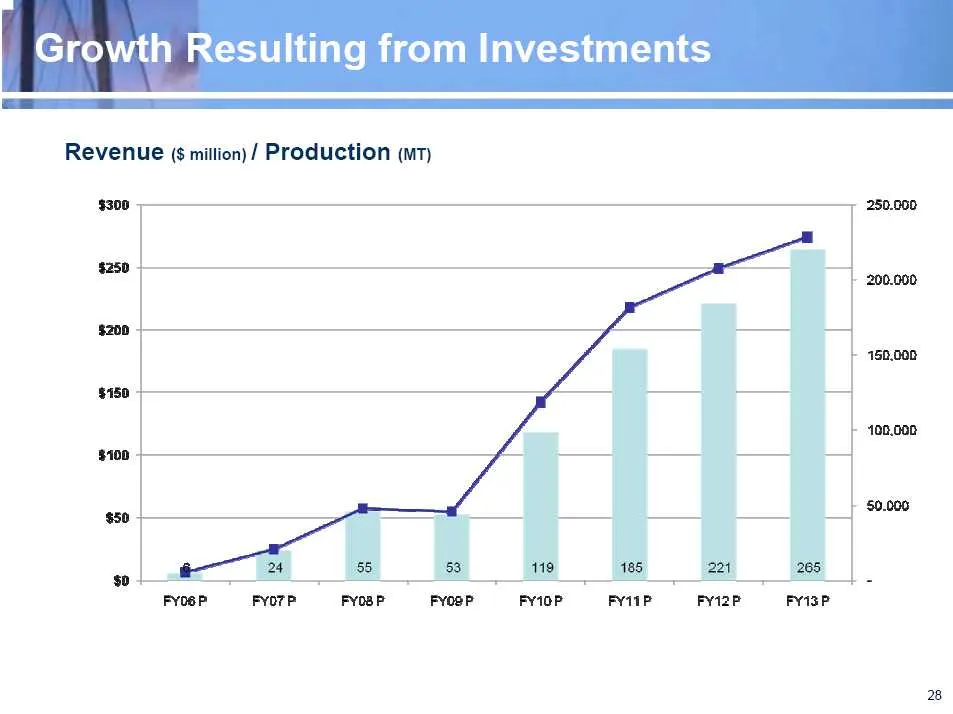
Slide 28: Growth Resulting from Investments
Growth Resulting from Investments Revenue (§ million) / Production (mt) 3300 250.000 - 200.000 150,000 100.000 28
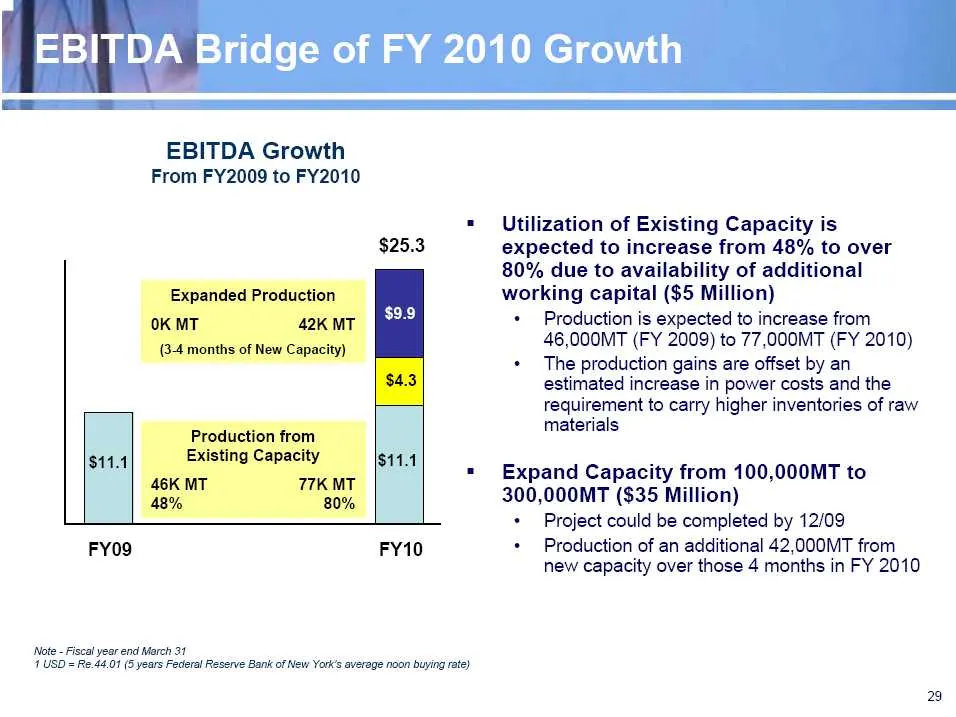
Slide 29: EBITDA Bridge of FY 2010 Growth
EBITDA Bridge of FY 2010 Growth EBITDA Growth From FY2009 to FY2010 = Utilization of Existing Capacity is $25.3 expected to increase from 48% to over 80% due to availability of additional =xpanded Pre working capital ($5 Million) + Production is expected to increase from 46,000MT (FY 2009) to 77,000
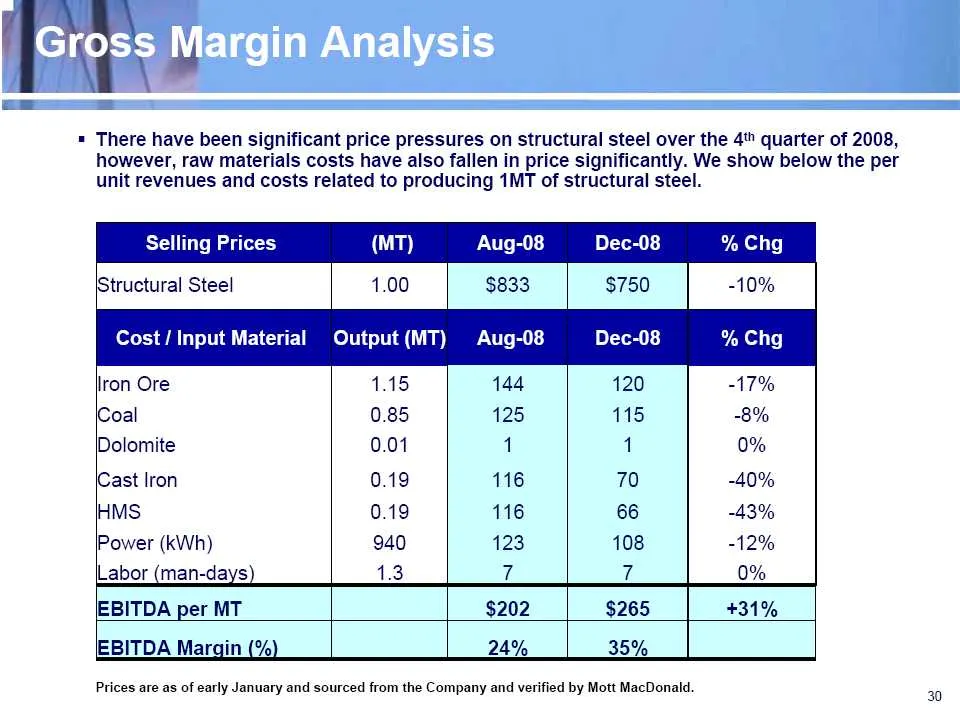
Slide 30: Structural steel price pressures and per unit economics
\ = There have been significant price pressures on structural steel over the 4" quarter of 2008, however, raw materials costs have also fallen in price significantly. We show below the per unit revenues and costs related to producing 1MT of structural steel. Selling Prices (MT) Aug-08 Dec-08 Cost/ I
Slide 31: Merger with Geneva
Slide 32: Attractive Post-Transaction Valuation
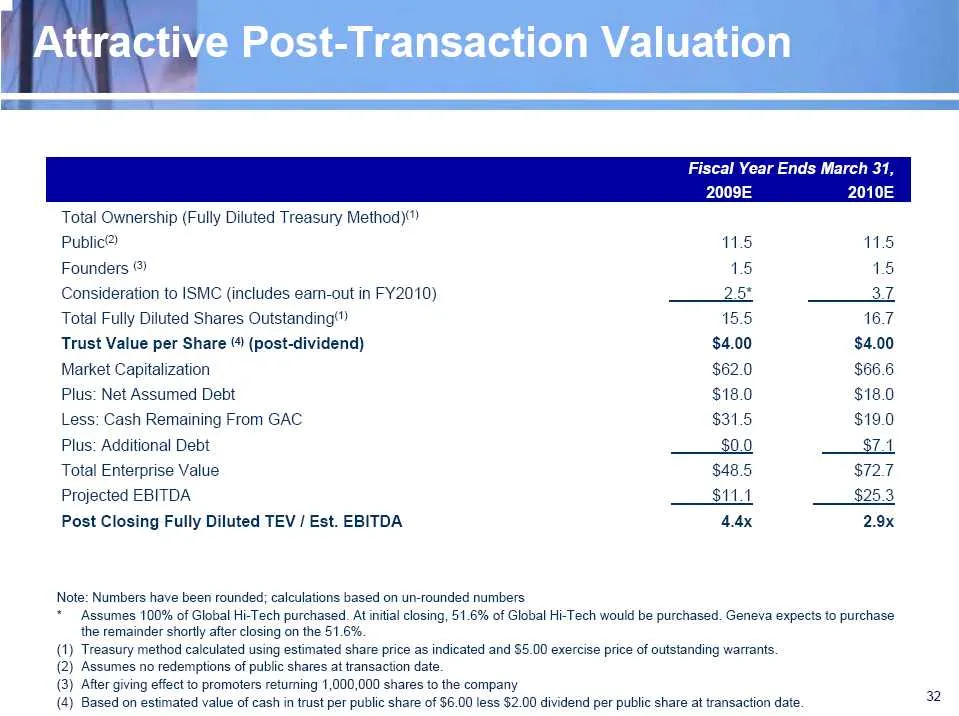
Attractive Post-Transaction Valuation iscal Year Ends March 31, 2009E 2010E Total Ownership (Fully Diluted Treasury Method)" Public? 15 U5 Founders ® 15 15 Consideration to ISMC (includes eamn-out in FY2010) 25% 37 Total Fully Diluted Shares Outstanding”) 155 16.7 Trust Value per Share ‘ (post-divid
Slide 33: Transaction Consideration
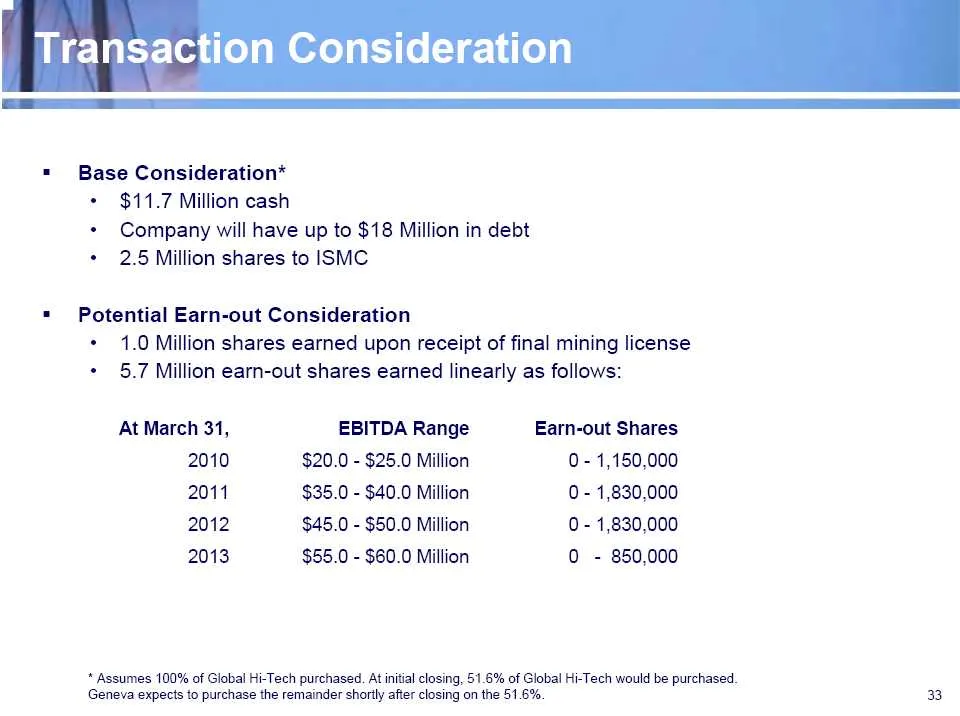
Transaction Consideration = Base Consideration* * $11.7 Million cash * Company will have up to $18 Million in debt * 2.5 Million shares to ISMC. «Potential Earn-out Consideration + 1.0 Million shares earned upon receipt of final mining license * 5.7 Million earn-out shares earned linearly as follows
Slide 34: Public Shareholder Consideration
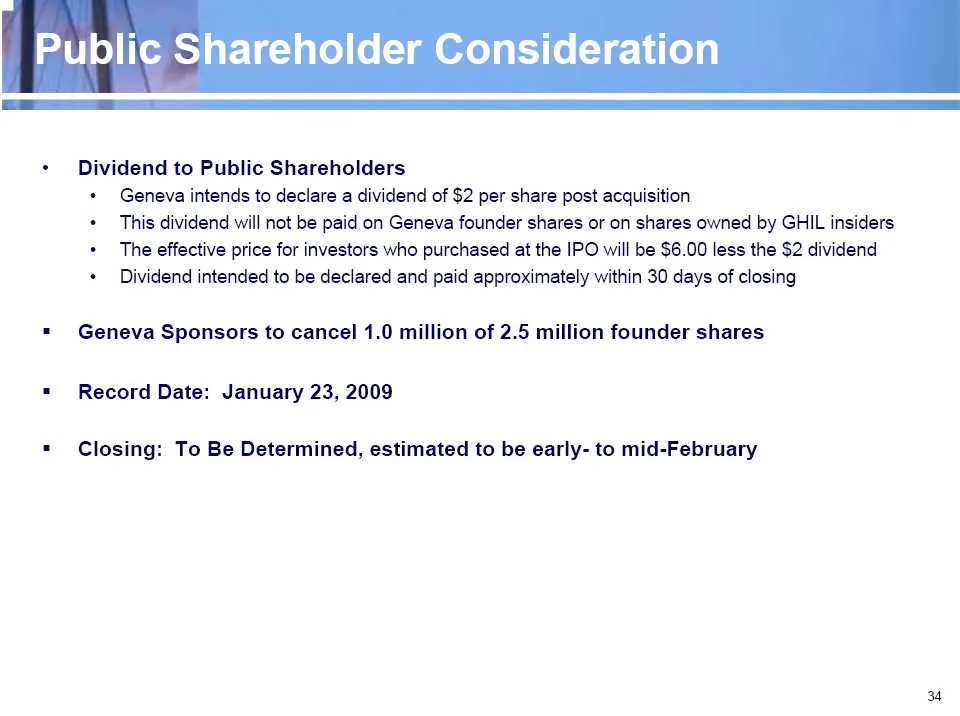
Public Shareholder Consideration + Dividend to Public Shareholders * Geneva intends to declare a dividend of $2 per share post acquisition * This dividend will not be paid on Geneva founder shares or on shares owned by GHIL insiders * The effective price for investors who purchased at the IPO will b
Slide 35: Summary and Conclusion
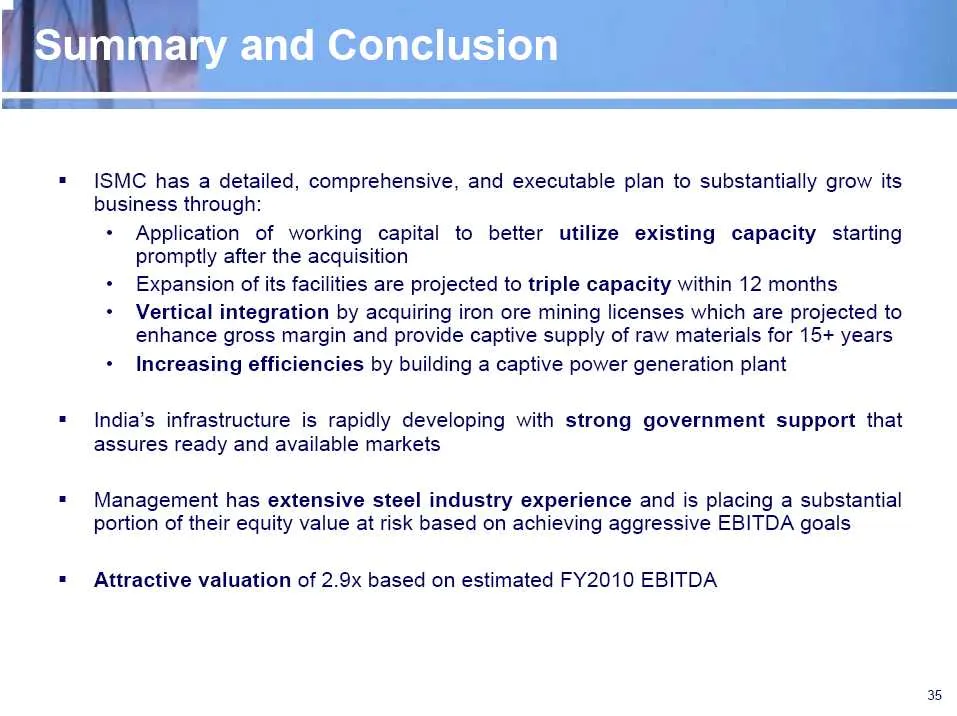
Summary and Conclusion = _ISMC has a detailed, comprehensive, and executable plan to substantially grow its business through: + Application of working capital to better utilize existing capacity starting promptly after the acquisition + Expansion of its facilities are projected to triple capacity wi
Slide 36: Appendix A Comparables
Slide 37: TEV / FY2010E EBITDA
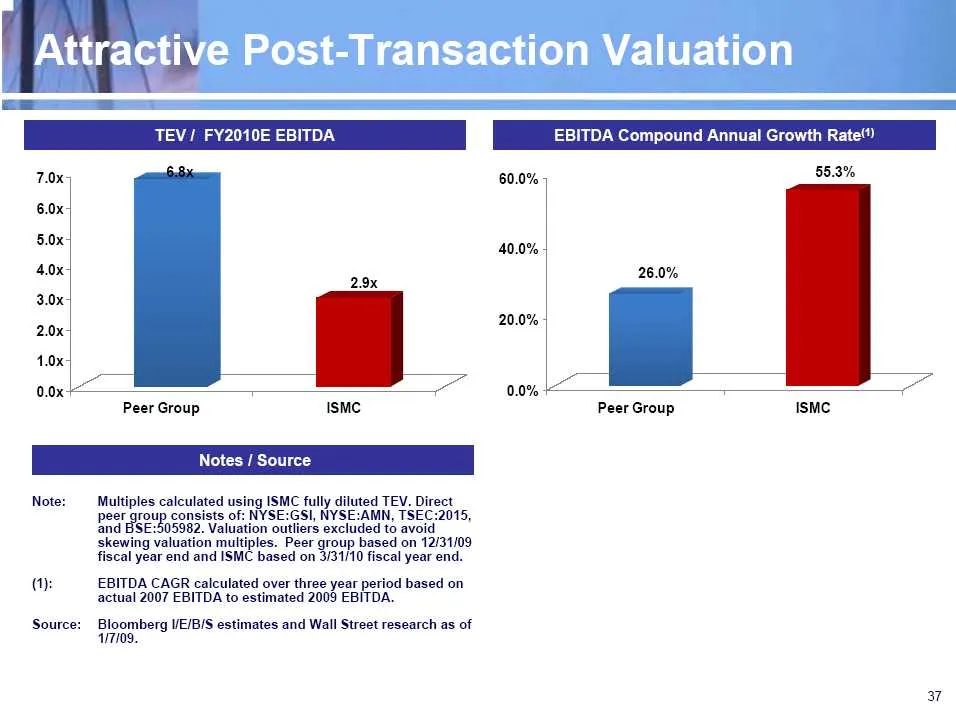
TEV/ FY2010E EBITDA —S EBITDA Compound Annual Growth Rate“) 7.0x 60.0% 55.3% 60x BOK 40.0% 40x. , 29x 26.0% 3.0x 20.0% 2.0x 10x 0.0x + 0.0% + “a Peer Group Ismc Peer Group IsMc Notes / Source Note: Multiples calculated using ISMC fully diluted TEV. Direct peer group consists of: NYSE:GSI, NYSE:AMN,
Slide 38: Comparable Public Companies
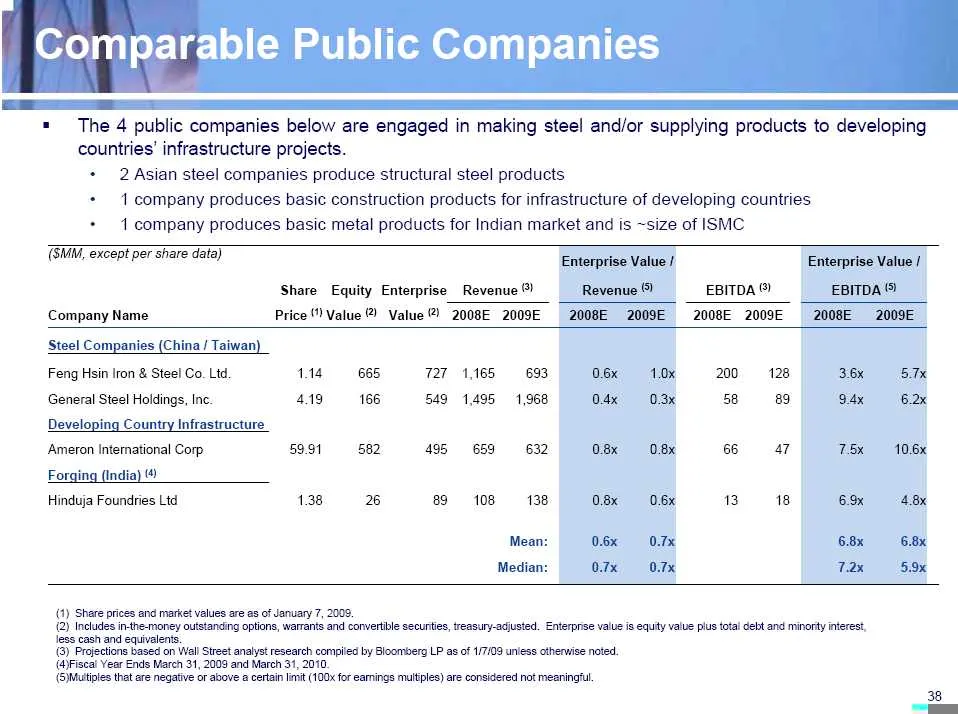
Comparable Public Companies The 4 public companies below are engaged in making steel and/or supplying products to developing countries’ infrastructure projects. + 2 Asian steel companies produce structural steel products + 1 company produces basic construction products for infrastructure of developi
Slide 39: Contacts
Slide 40: Contacts
Contacts = Post Transaction Management + RC Krishna 347-524-8425 [email protected] + Ash Belur 44-20-8201-9316 [email protected] = Geneva Acquisition Corporation + Jim McGrath 617-361-6530 [email protected] + Vin Pica 212-863-9434 [email protected] + John Rousseau 617-
Slide 41: India Steel & Metals Corp.
ud ndia Steel & Metals Corp.
Source: SEC EDGAR · 8-K filed Jan 13, 2009