Golden Falcon Acquisition Corp
Golden Falcon Acquisition — SPAC Merger (December 2022)
53 slides from Golden Falcon Acquisition's SPAC merger presentation, Dec 7, 2022
Slide 1: December 2022 Investor Presentation
December 2022 Investor Presentation Exhibit 99.2
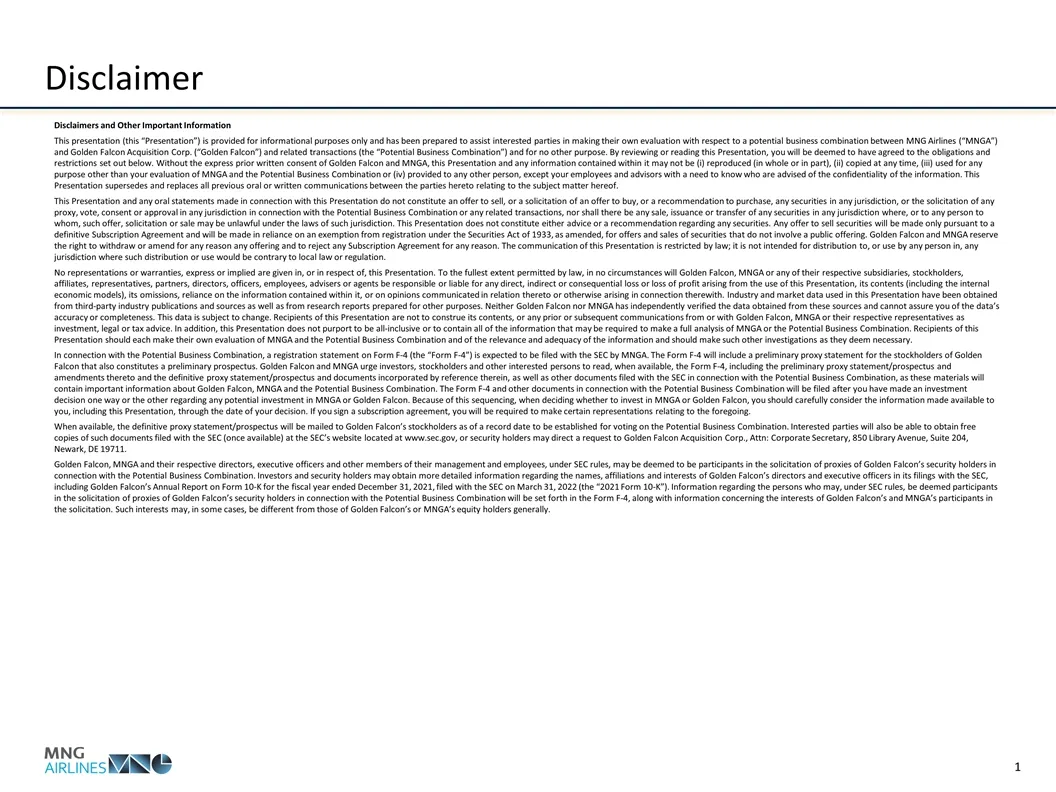
Slide 2: Disclaimers and Other Important Information
Disclaimer Disclaimers and Other Important Information This presentation (this “Presentation”) is provided for informational purposes only and has been prepared to assist interested parties in making their own evaluation with respect to a potential business combination between MNG Airlines (“MNGA”)
Slide 3: Forward-Looking Statements
Disclaimer Forward-Looking Statements Certain statements included in this Presentation are not historical facts but are forward-looking statements for purposes of the safe harbor provisions under the United States Private Securities Litigation Reform Act of 1995. Forward-looking statements generally
Slide 4: Golden Falcon and MNGA Leadership Team
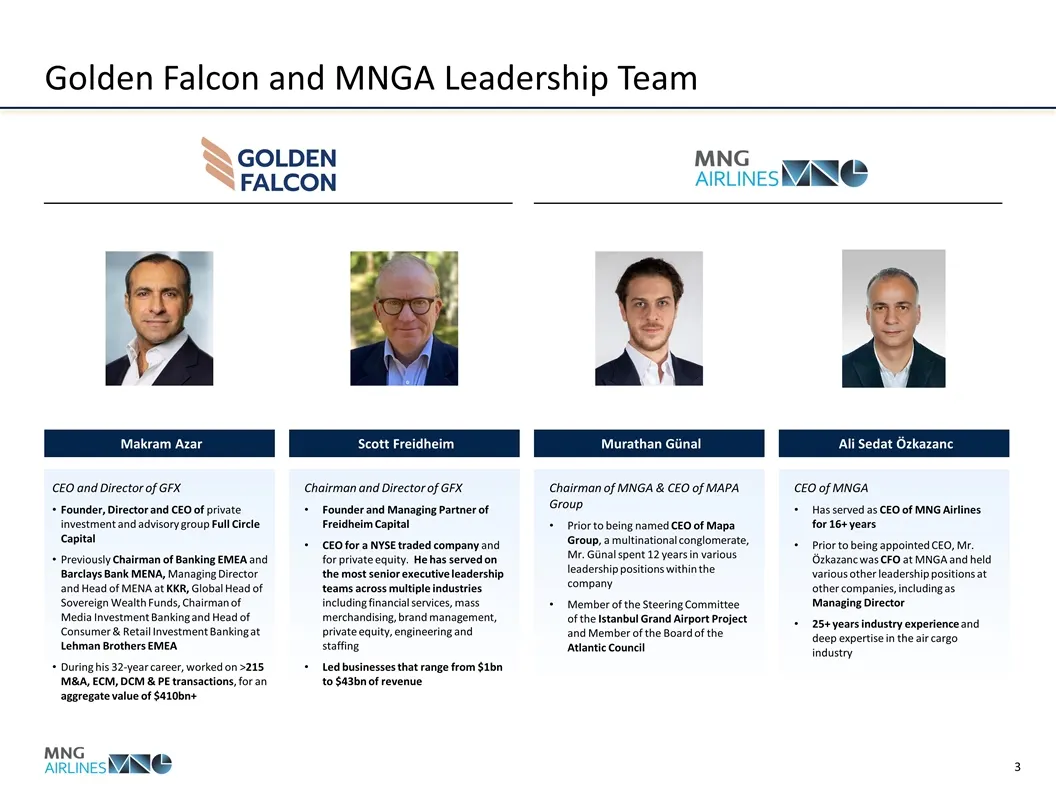
Golden Falcon and MNGA Leadership Team CEO and Director of GFX Founder, Director and CEO of private investment and advisory group Full Circle Capital Previously Chairman of Banking EMEA and Barclays Bank MENA, Managing Director and Head of MENA at KKR, Global Head of Sovereign Wealth Funds, Chairman
Slide 5: Golden Falcon Has Reviewed More than 500 Targets, and MNGA Aligns Well
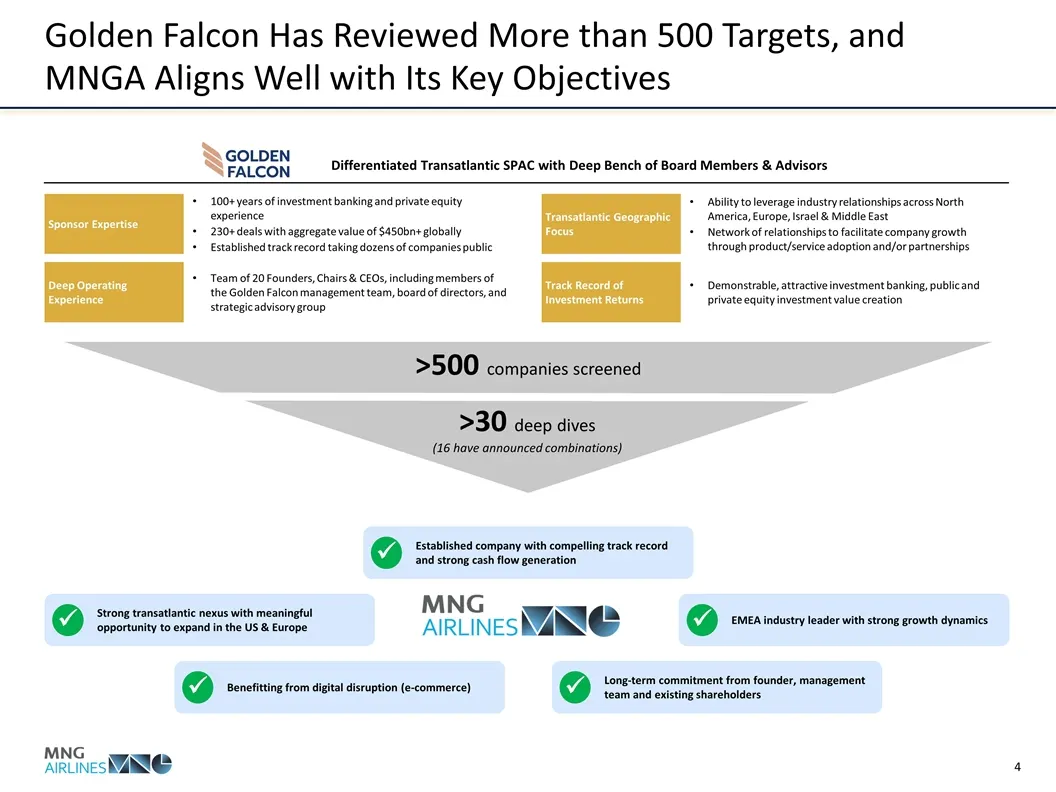
Transatlantic Geographic Focus Ability to leverage industry relationships across North America, Europe, Israel & Middle East Network of relationships to facilitate company growth through product/service adoption and/or partnerships Track Record of Investment Returns Demonstrable, attractive investme
Slide 6: MNGA is in the Top 1% of US-Listed Opportunities
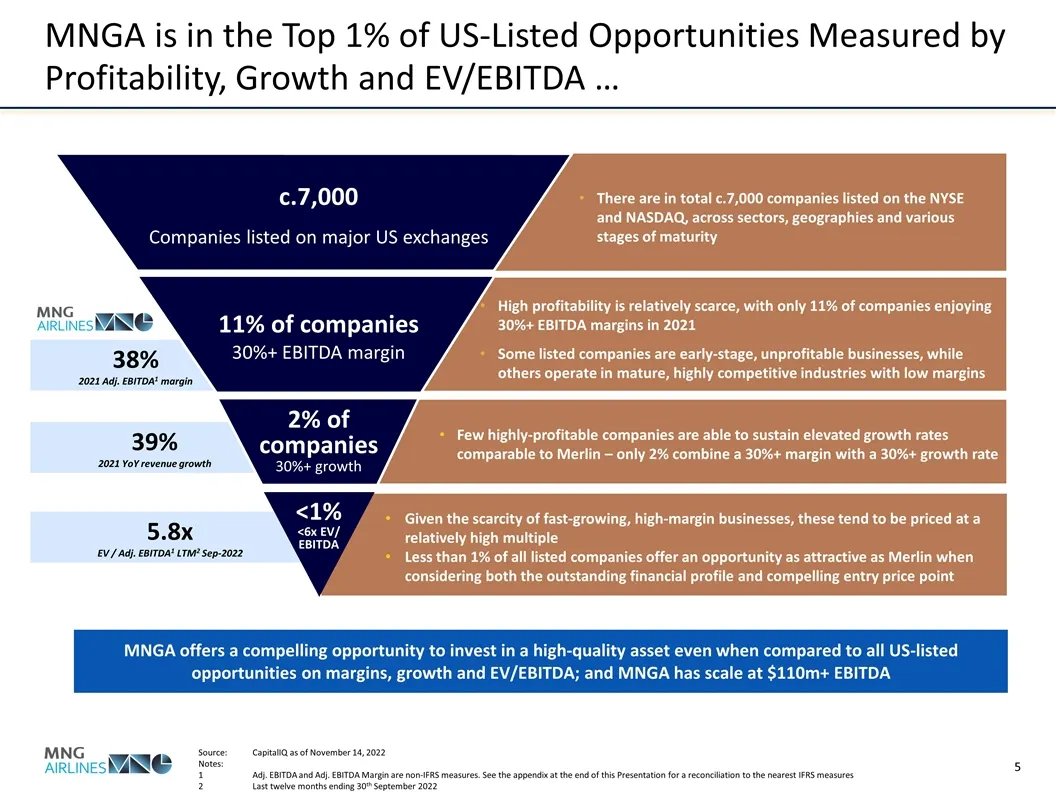
5.8x EV / Adj. EBITDA1 LTM2 Sep-2022 38% 2021 Adj. EBITDA1 margin 39% 2021 YoY revenue growth Given the scarcity of fast-growing, high-margin businesses, these tend to be priced at a relatively high multiple Less than 1% of all listed companies offer an opportunity as attractive as Merlin when consi
Slide 7: A Differentiated High-Quality Asset in the DeSPAC Opportunities Universe
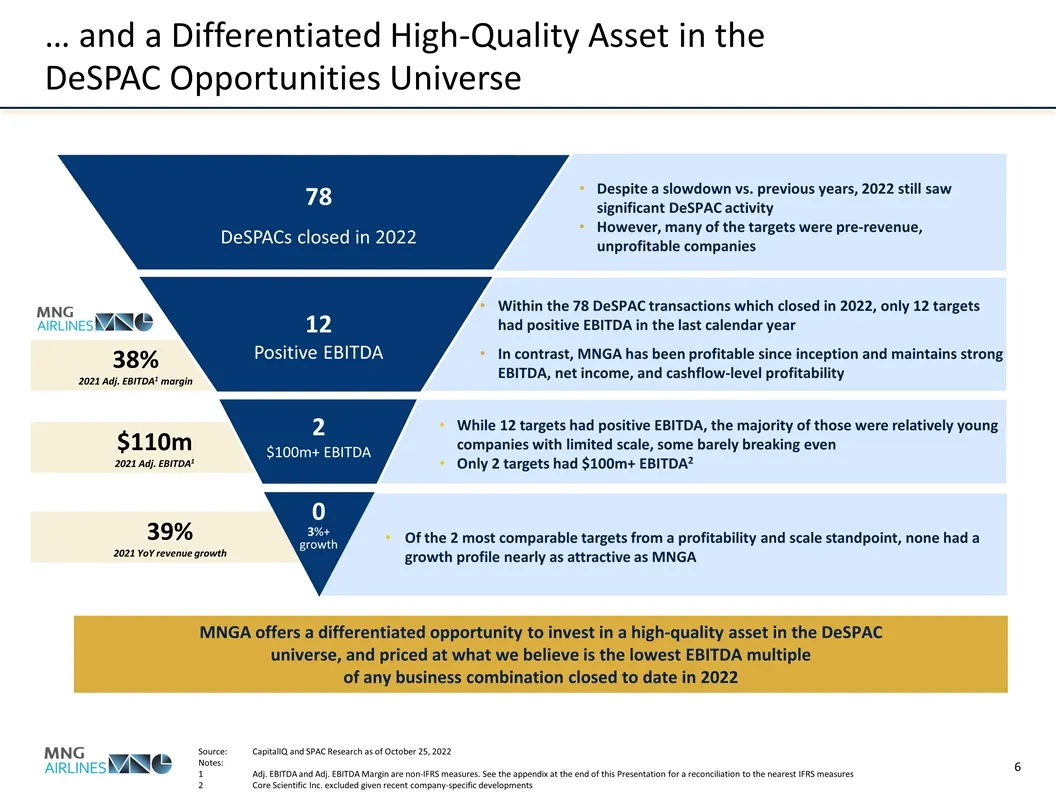
39% 2021 YoY revenue growth 38% 2021 Adj. EBITDA1 margin $110m 2021 Adj. EBITDA1 Of the 2 most comparable targets from a profitability and scale standpoint, none had a growth profile nearly as attractive as MNGA … and a Differentiated High-Quality Asset in the DeSPAC Opportunities Universe While 12
Slide 8: Proposed Transaction Summary
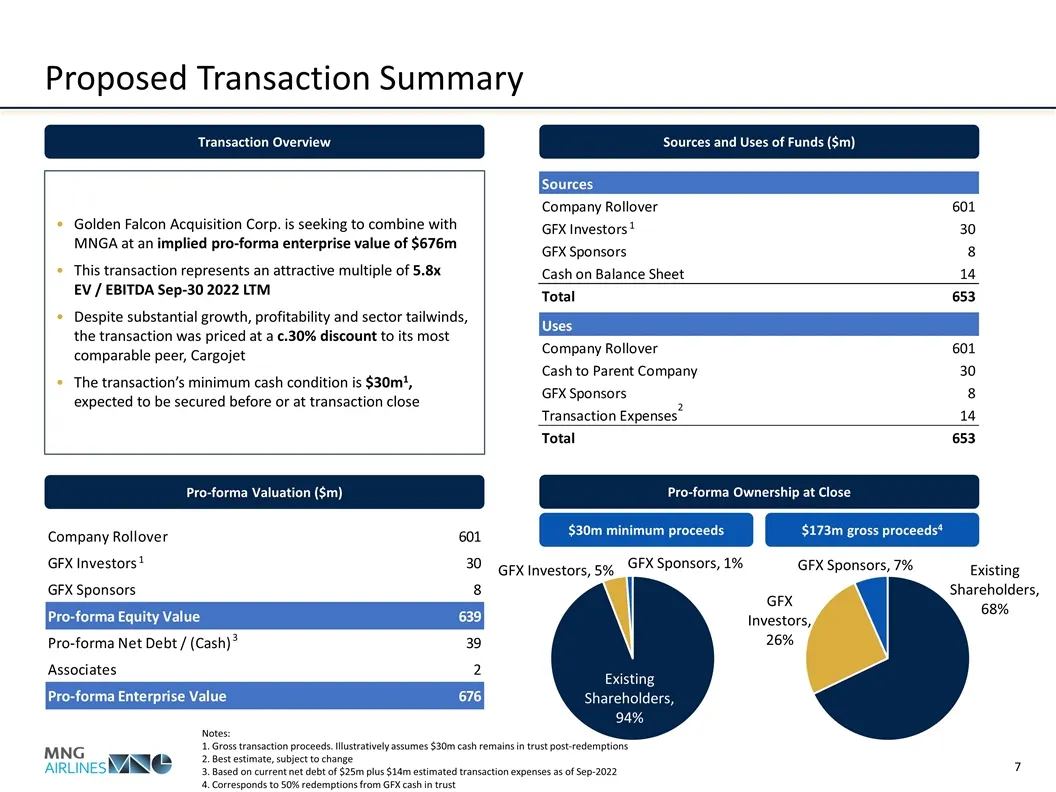
Proposed Transaction Summary Sources and Uses of Funds ($m) Transaction Overview Golden Falcon Acquisition Corp. is seeking to combine with MNGA at an implied pro-forma enterprise value of $676m This transaction represents an attractive multiple of 5.8x EV / EBITDA Sep-30 2022 LTM Despite substantia
Slide 9: MNG Airlines is a Global Logistics Provider & e-Commerce Enabler
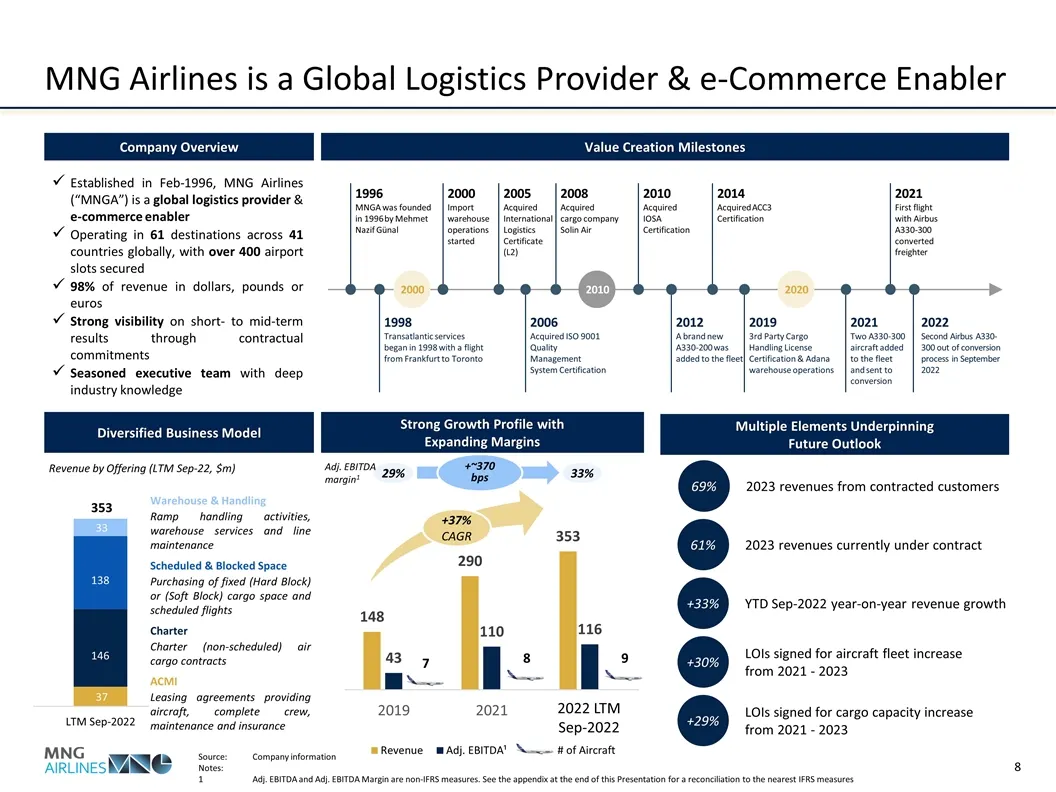
MNG Airlines is a Global Logistics Provider & e-Commerce Enabler Established in Feb-1996, MNG Airlines (“MNGA”) is a global logistics provider & e-commerce enabler Operating in 61 destinations across 41 countries globally, with over 400 airport slots secured 98% of revenue in dollars, pounds or euro
Slide 10: Istanbul is Strategically Located at the Center of Global Commercial Routes
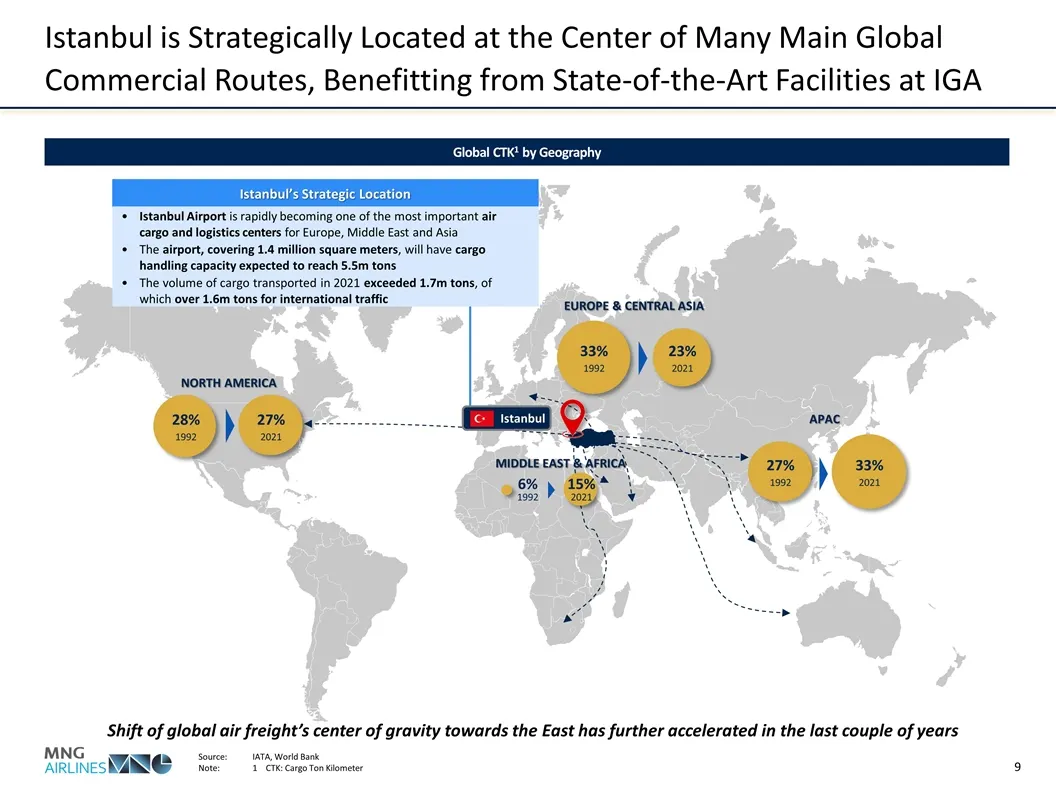
Istanbul is Strategically Located at the Center of Many Main Global Commercial Routes, Benefitting from State-of-the-Art Facilities at IGA Source:IATA, World Bank Note:1 CTK: Cargo Ton Kilometer Global CTK1 by Geography APAC 33% 2021 27% 1992 MIDDLE EAST & AFRICA 15% 2021 6% 1992 EUROPE & CENTRAL AS
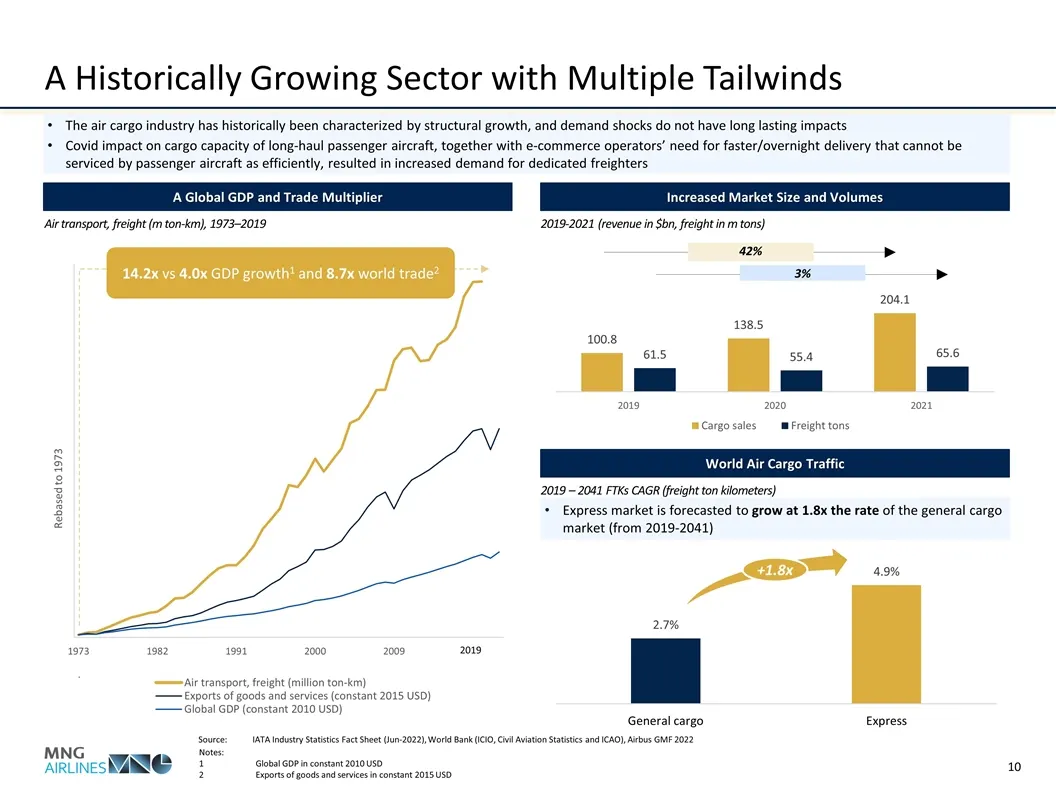
Slide 11: A Historically Growing Sector with Multiple Tailwinds
A Historically Growing Sector with Multiple Tailwinds The air cargo industry has historically been characterized by structural growth, and demand shocks do not have long lasting impacts Covid impact on cargo capacity of long-haul passenger aircraft, together with e-commerce operators’ need for faste
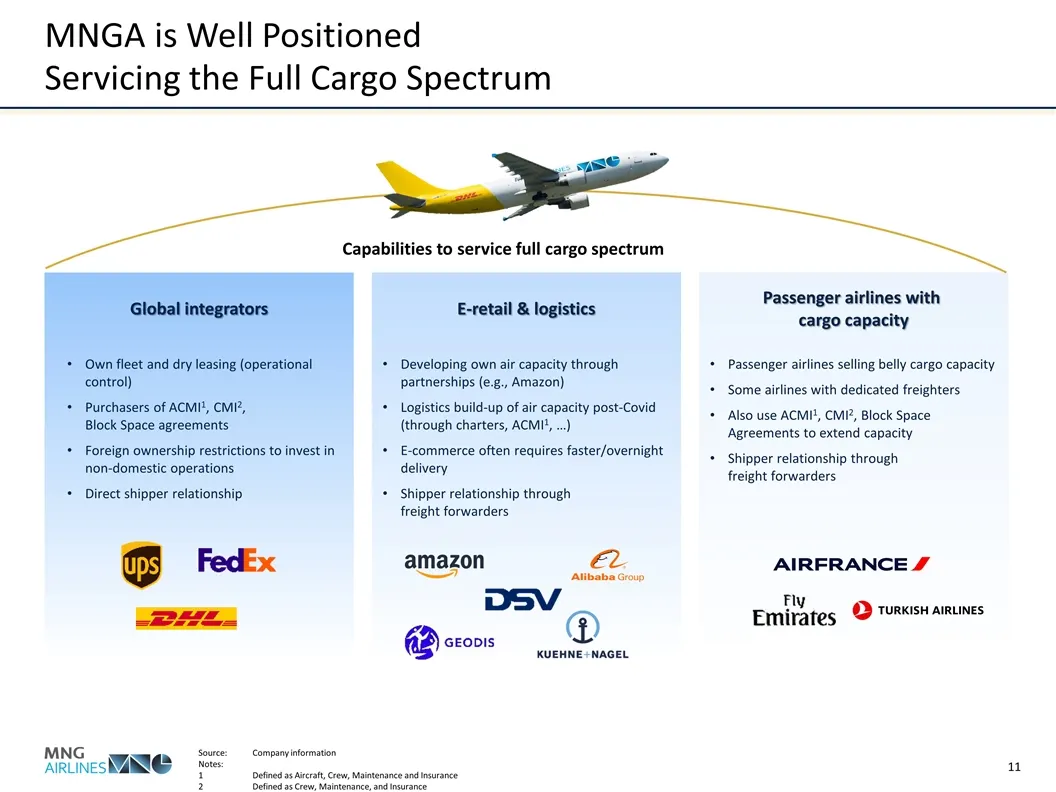
Slide 12: MNGA is Well Positioned Servicing the Full Cargo Spectrum
MNGA is Well Positioned Servicing the Full Cargo Spectrum Source:Company information Notes: Defined as Aircraft, Crew, Maintenance and Insurance Defined as Crew, Maintenance, and Insurance Global integrators Own fleet and dry leasing (operational control) Purchasers of ACMI1, CMI2, Block Space agree
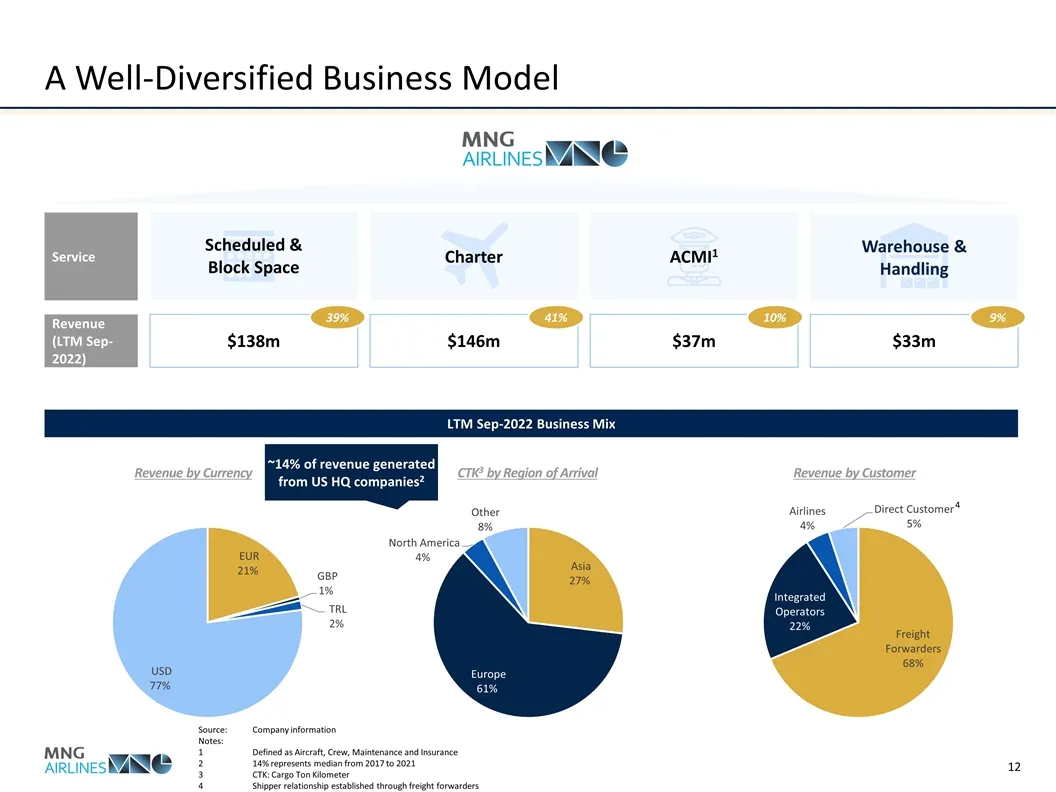
Slide 13: A Well-Diversified Business Model
A Well-Diversified Business Model Service $138m Revenue (LTM Sep-2022) Scheduled & Block Space Warehouse & Handling $146m $37m $33m LTM Sep-2022 Business Mix Source:Company information Notes: Defined as Aircraft, Crew, Maintenance and Insurance 14% represents median from 2017 to 2021 CTK: Cargo Ton
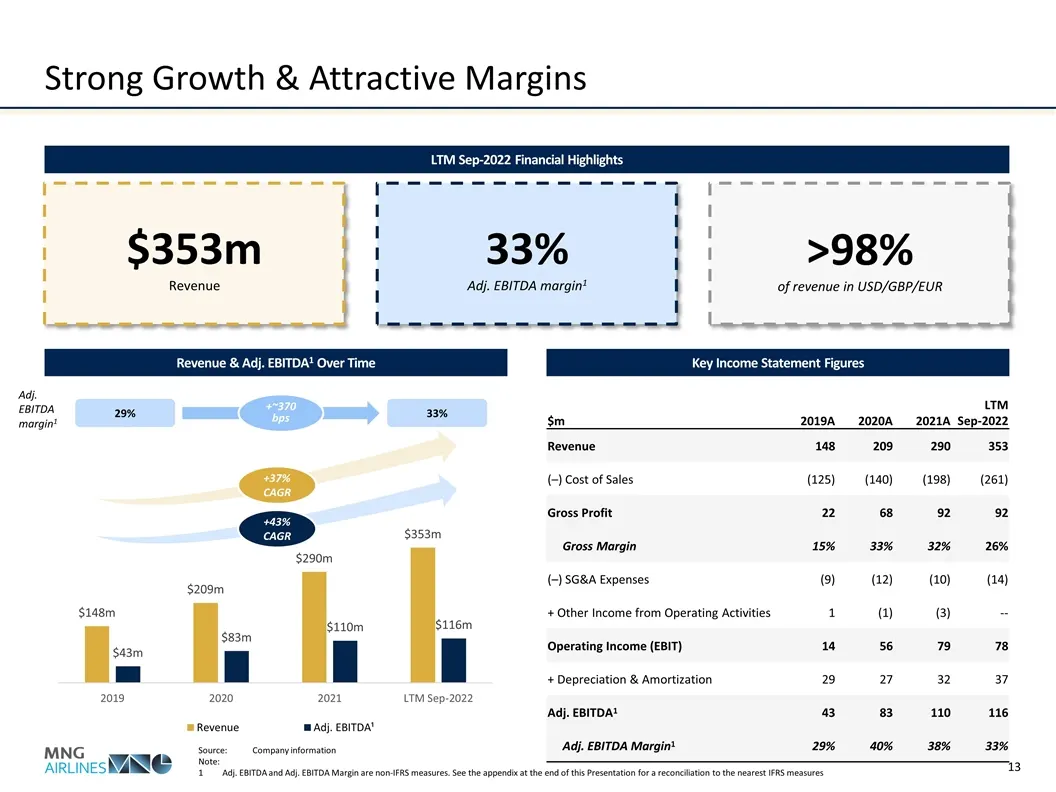
Slide 14: Strong Growth & Attractive Margins
Strong Growth & Attractive Margins 33% Adj. EBITDA margin1 >98% of revenue in USD/GBP/EUR +43% CAGR Adj. EBITDA margin1 29% 33% +~370 bps Revenue & Adj. EBITDA1 Over Time LTM Sep-2022 Financial Highlights +37% CAGR $353m Revenue Source:Company information Note: Adj. EBITDA and Adj. EBITDA Margin are
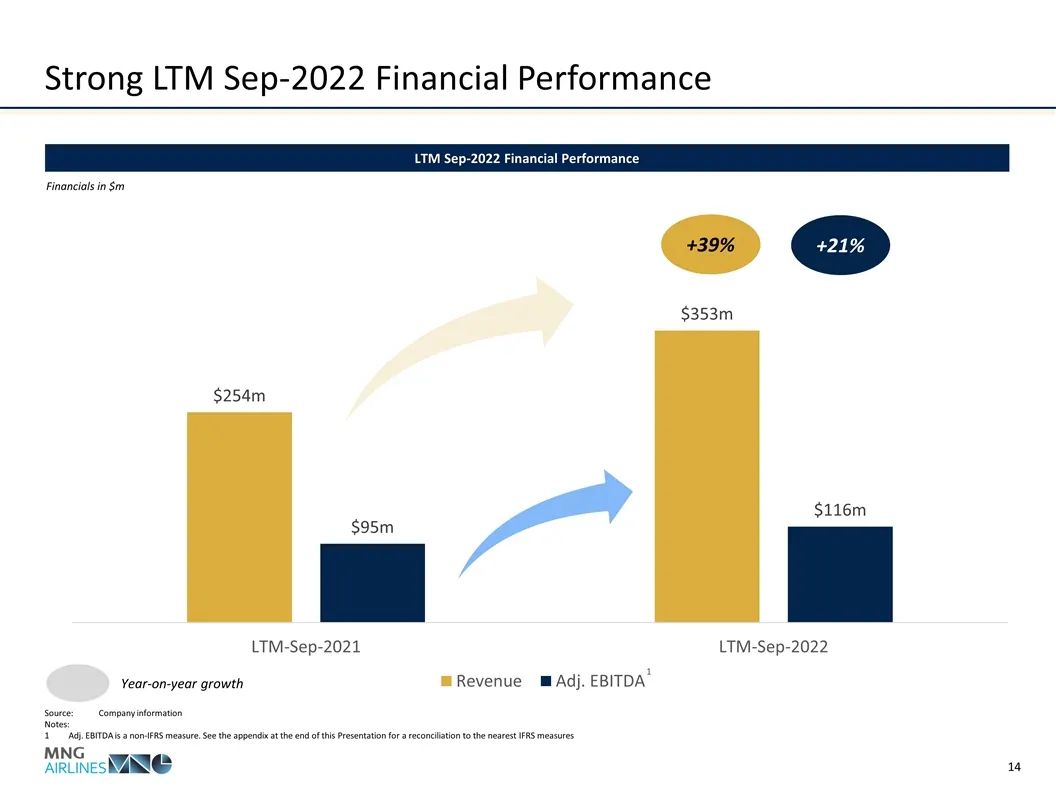
Slide 15: Strong LTM Sep-2022 Financial Performance
Strong LTM Sep-2022 Financial Performance LTM Sep-2022 Financial Performance +39% Financials in $m 1 +21% Year-on-year growth Source:Company information Notes: Adj. EBITDA is a non-IFRS measure. See the appendix at the end of this Presentation for a reconciliation to the nearest IFRS measures
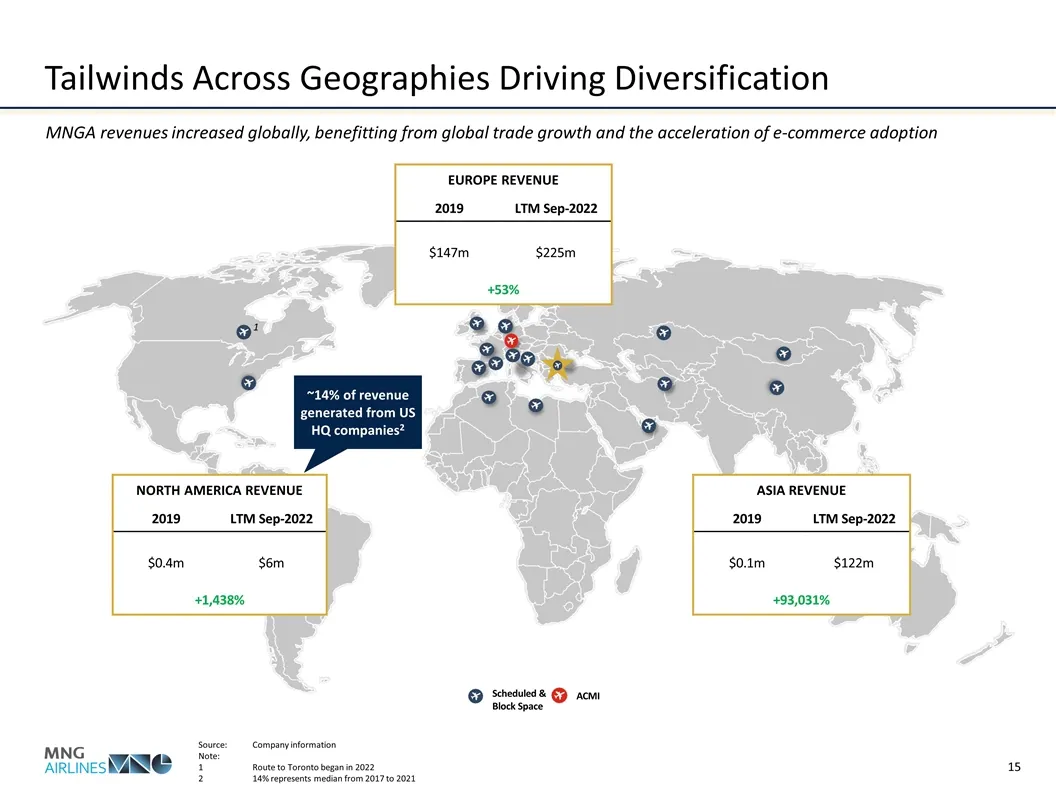
Slide 16: Tailwinds Across Geographies Driving Diversification
Tailwinds Across Geographies Driving Diversification MNGA revenues increased globally, benefitting from global trade growth and the acceleration of e-commerce adoption Source:Company information Note: Route to Toronto began in 2022 14% represents median from 2017 to 2021 ACMI Scheduled & Block Space
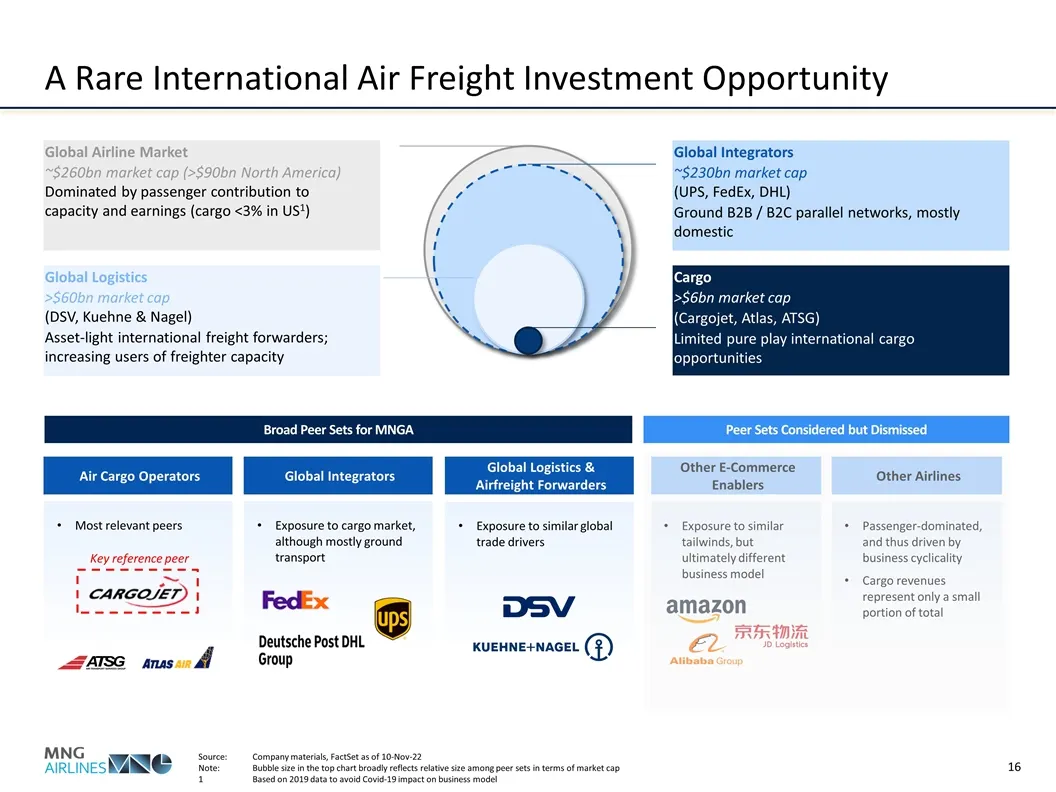
Slide 17: A Rare International Air Freight Investment Opportunity
A Rare International Air Freight Investment Opportunity Source:Company materials, FactSet as of 10-Nov-22 Note: Bubble size in the top chart broadly reflects relative size among peer sets in terms of market cap 1Based on 2019 data to avoid Covid-19 impact on business model Global Integrators ~$230bn
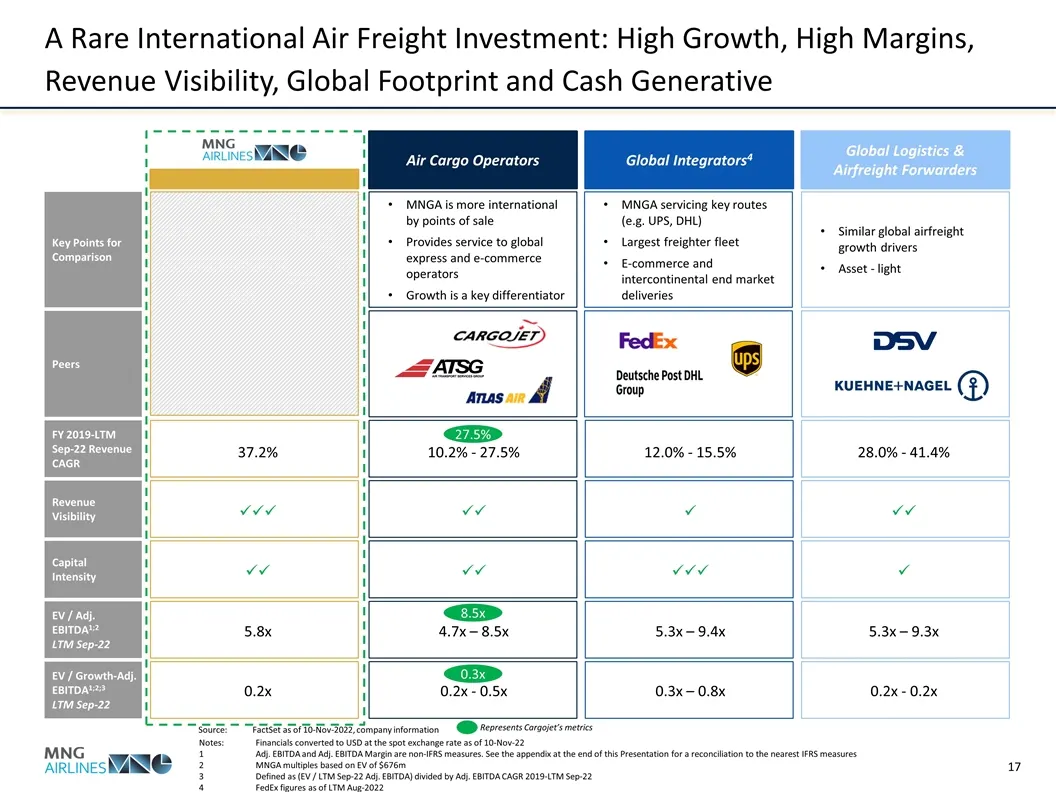
Slide 18: A Rare International Air Freight Investment: High Growth, High Margins
37.2% 10.2% - 27.5% 12.0% - 15.5% 28.0% - 41.4% üüü üü ü üü üü üü üüü ü 5.8x 4.7x – 8.5x 5.3x – 9.4x 5.3x – 9.3x 0.2x 0.2x - 0.5x 0.3x – 0.8x 0.2x - 0.2x A Rare International Air Freight Investment: High Growth, High Margins, Revenue Visibility, Global Footprint and Cash Generative Source:FactSet as
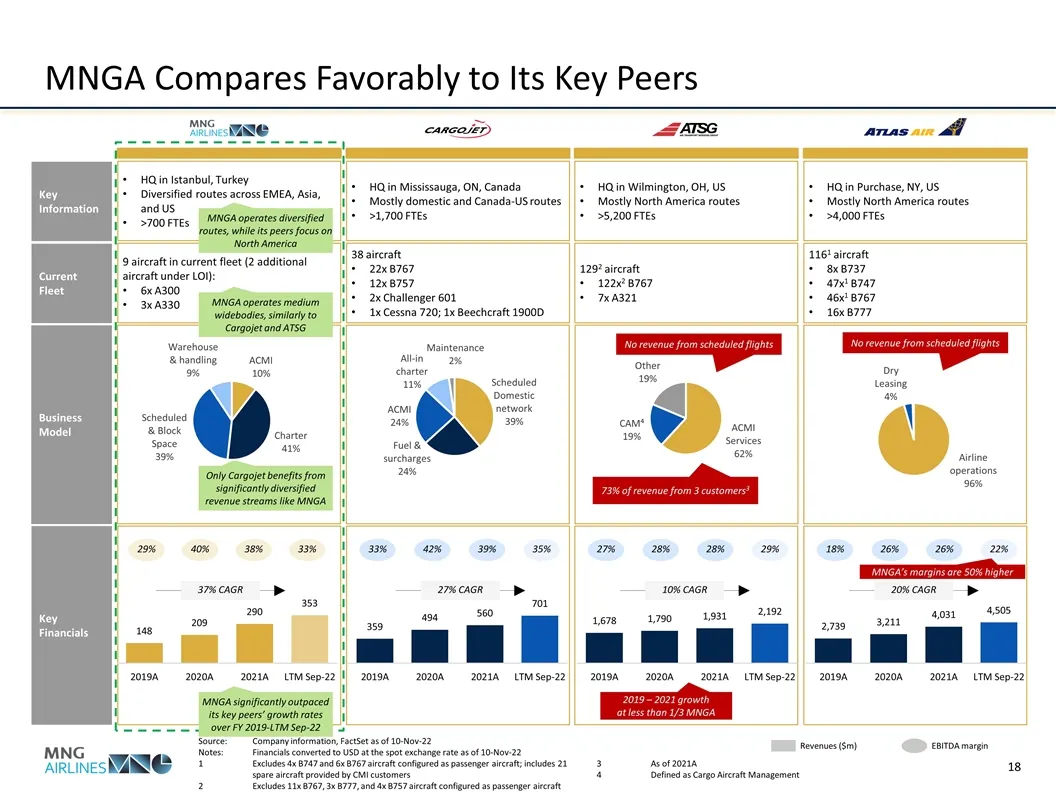
Slide 19: MNGA Compares Favorably to Its Key Peers
MNGA Compares Favorably to Its Key Peers Key Information HQ in Istanbul, Turkey Diversified routes across EMEA, Asia, and US >700 FTEs HQ in Mississauga, ON, Canada Mostly domestic and Canada-US routes >1,700 FTEs HQ in Purchase, NY, US Mostly North America routes >4,000 FTEs HQ in Wilmington, OH, U
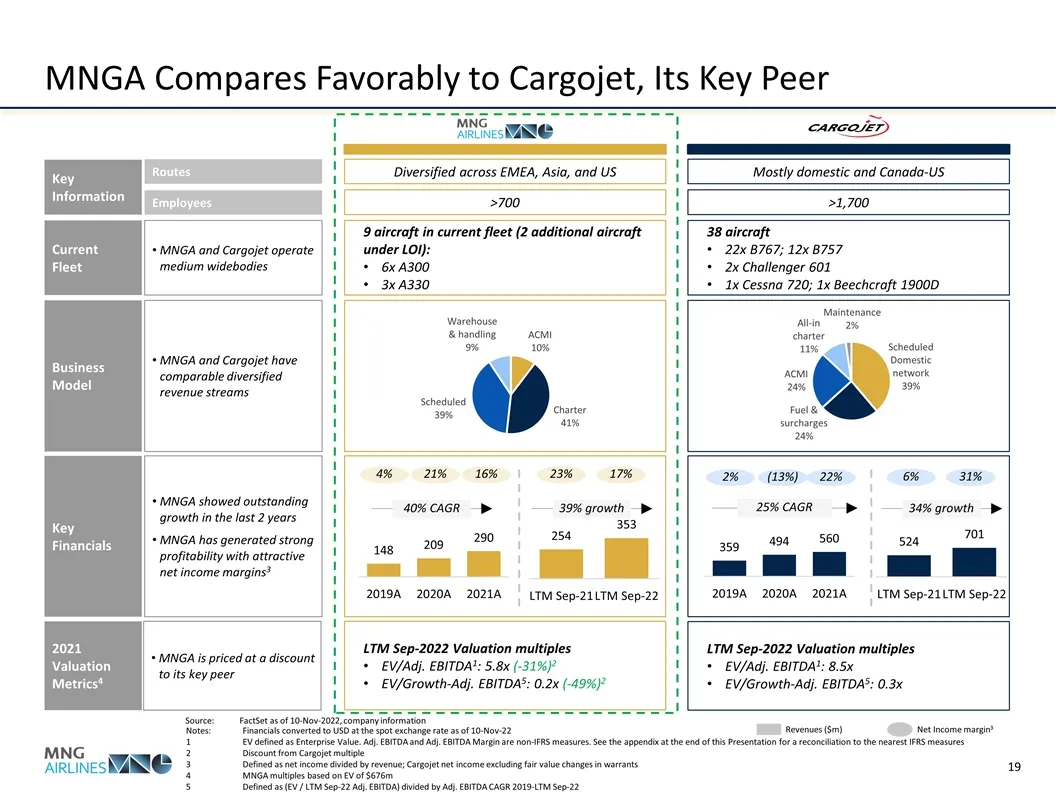
Slide 20: MNGA Compares Favorably to Cargojet, Its Key Peer
25% CAGR 2% (13%) 22% MNGA Compares Favorably to Cargojet, Its Key Peer Source:FactSet as of 10-Nov-2022, company information Revenues ($m) Net Income margin3 Key Information Routes Employees Key Financials MNGA showed outstanding growth in the last 2 years MNGA has generated strong profitability wi
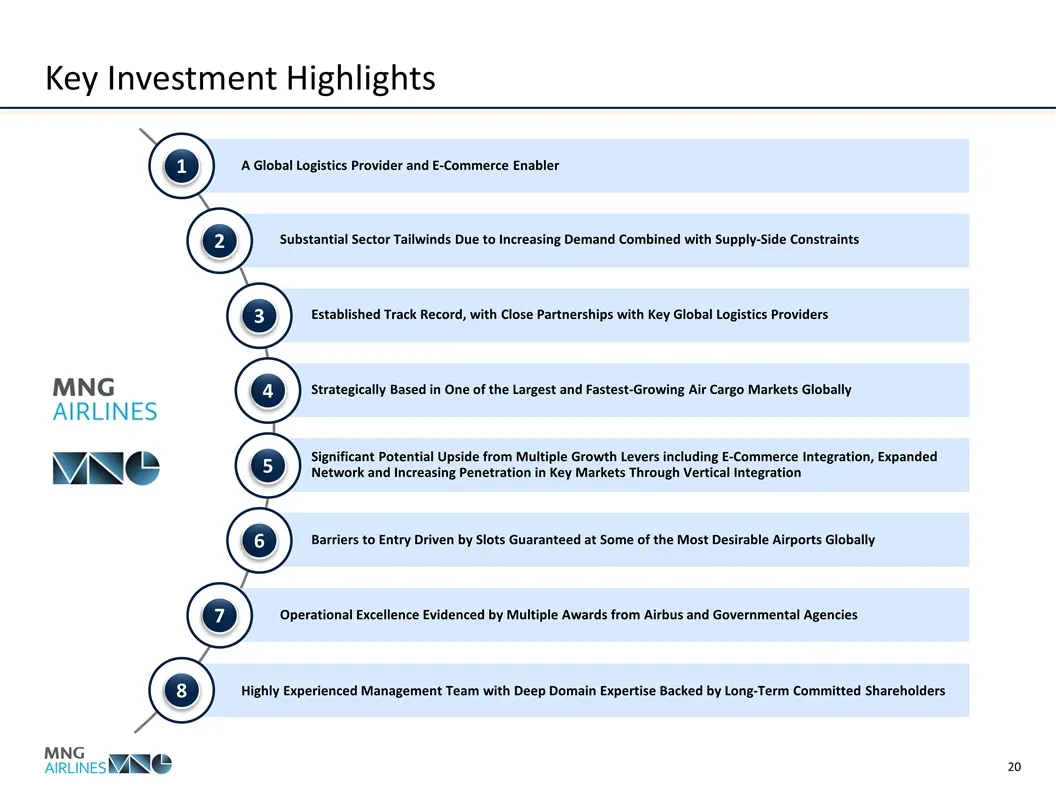
Slide 21: Key Investment Highlights
Substantial Sector Tailwinds Due to Increasing Demand Combined with Supply-Side Constraints Established Track Record, with Close Partnerships with Key Global Logistics Providers Strategically Based in One of the Largest and Fastest-Growing Air Cargo Markets Globally Significant Potential Upside from
Slide 22: Supporting Key Investment Highlights Materials - Appendix A
Supporting Key Investment Highlights Materials Appendix A
Slide 23: A Global Logistics Provider and E-Commerce Enabler
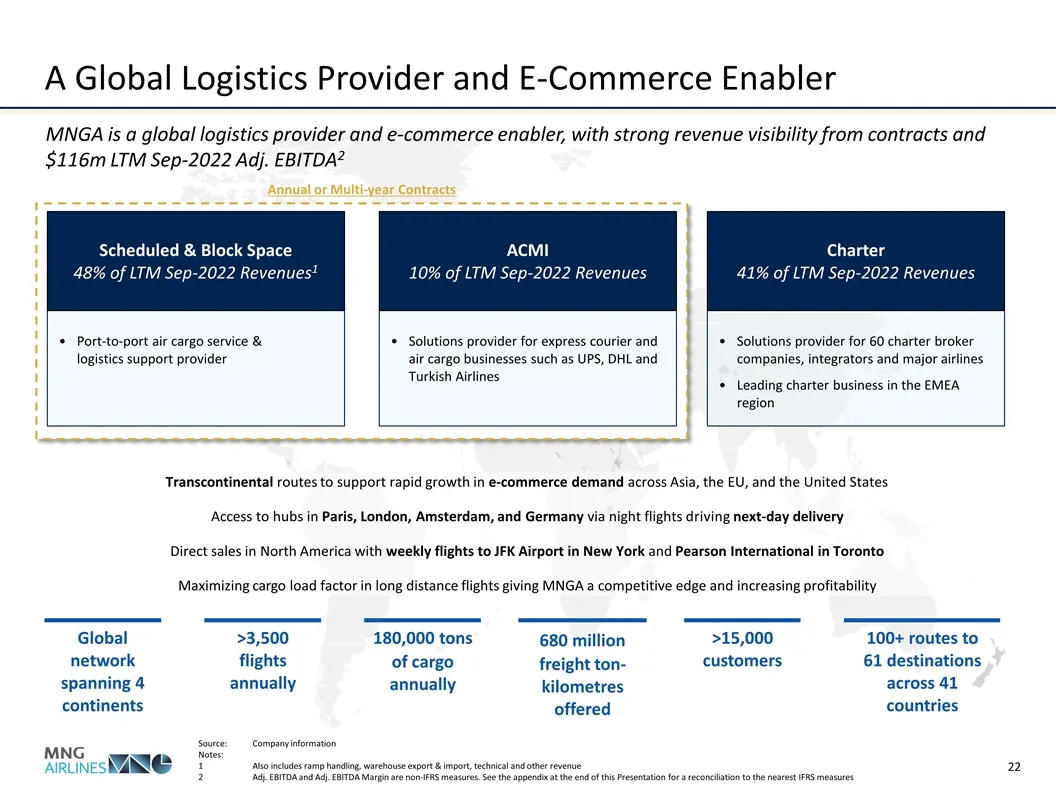
A Global Logistics Provider and E-Commerce Enabler Solutions provider for 60 charter broker companies, integrators and major airlines Leading charter business in the EMEA region Charter 41% of LTM Sep-2022 Revenues 100+ routes to 61 destinations across 41 countries 680 million freight ton-kilometres
Slide 24: A Global Logistics Provider and E-Commerce Enabler: Route Network
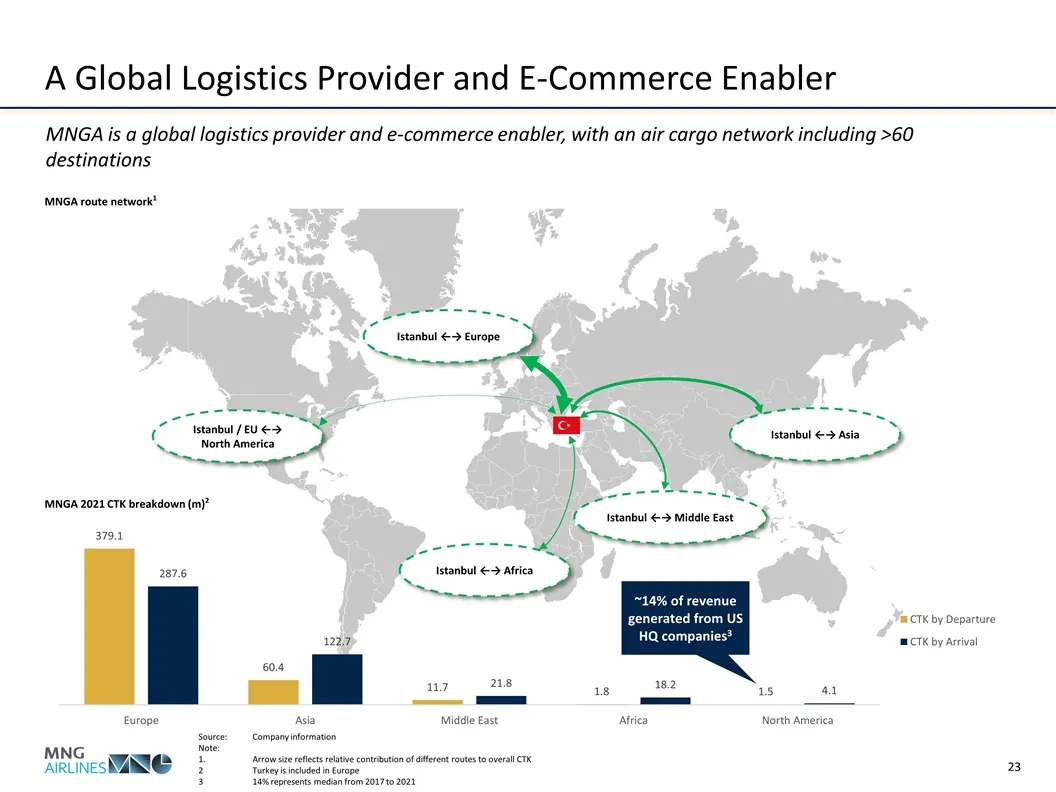
A Global Logistics Provider and E-Commerce Enabler MNGA is a global logistics provider and e-commerce enabler, with an air cargo network including >60 destinations Istanbul / EU ←→ North America Istanbul ←→ Europe Istanbul ←→ Africa Istanbul ←→ Asia Source:Company information Note: 1. Arrow size ref
Slide 25: Substantial Long-Lasting Tailwinds Due to Increasing Demand and Supply Constraints
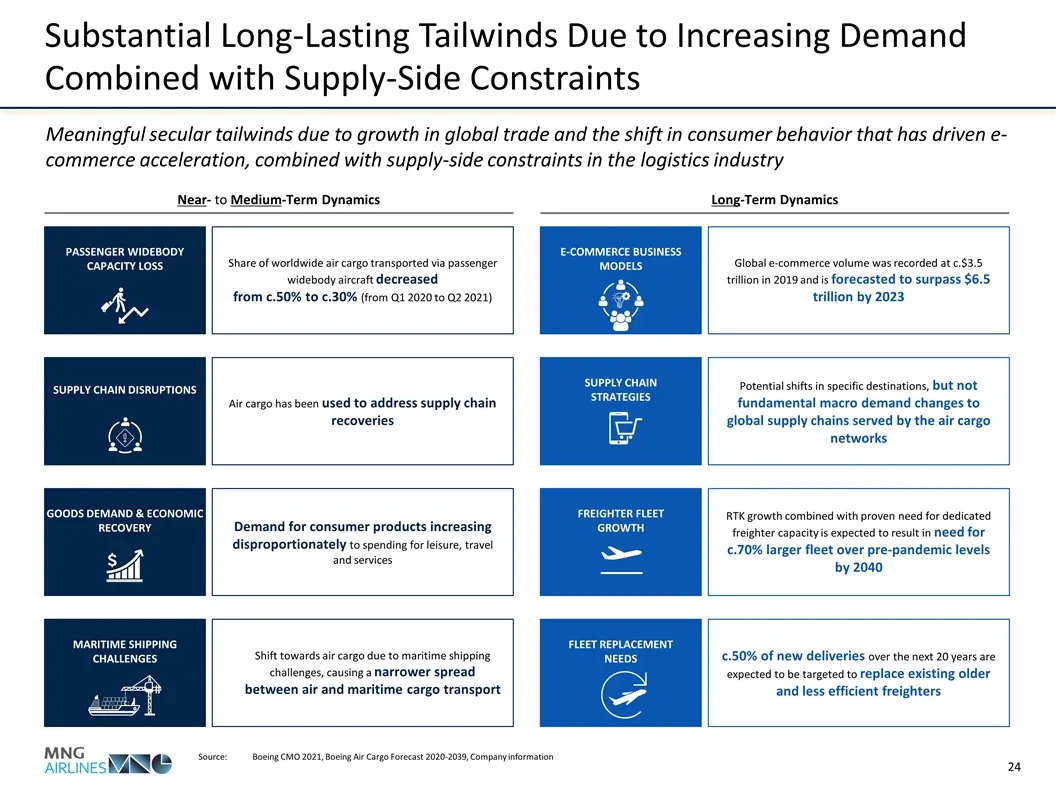
Substantial Long-Lasting Tailwinds Due to Increasing Demand Combined with Supply-Side Constraints Meaningful secular tailwinds due to growth in global trade and the shift in consumer behavior that has driven e-commerce acceleration, combined with supply-side constraints in the logistics industry PAS
Slide 26: Strategically Based in One of the Largest Air Cargo Markets
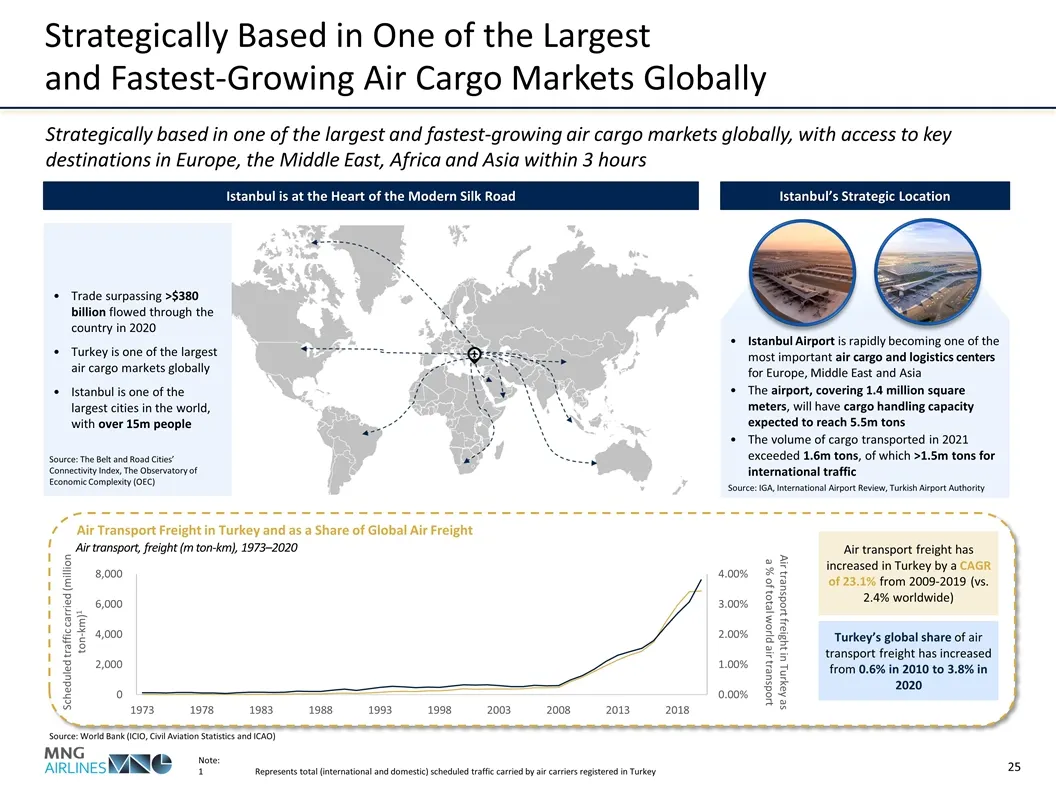
Strategically Based in One of the Largest and Fastest-Growing Air Cargo Markets Globally Strategically based in one of the largest and fastest-growing air cargo markets globally, with access to key destinations in Europe, the Middle East, Africa and Asia within 3 hours Note: 1Represents total (inter
Slide 27: Significant Upside from Multiple Growth Levers including E-Commerce Integration
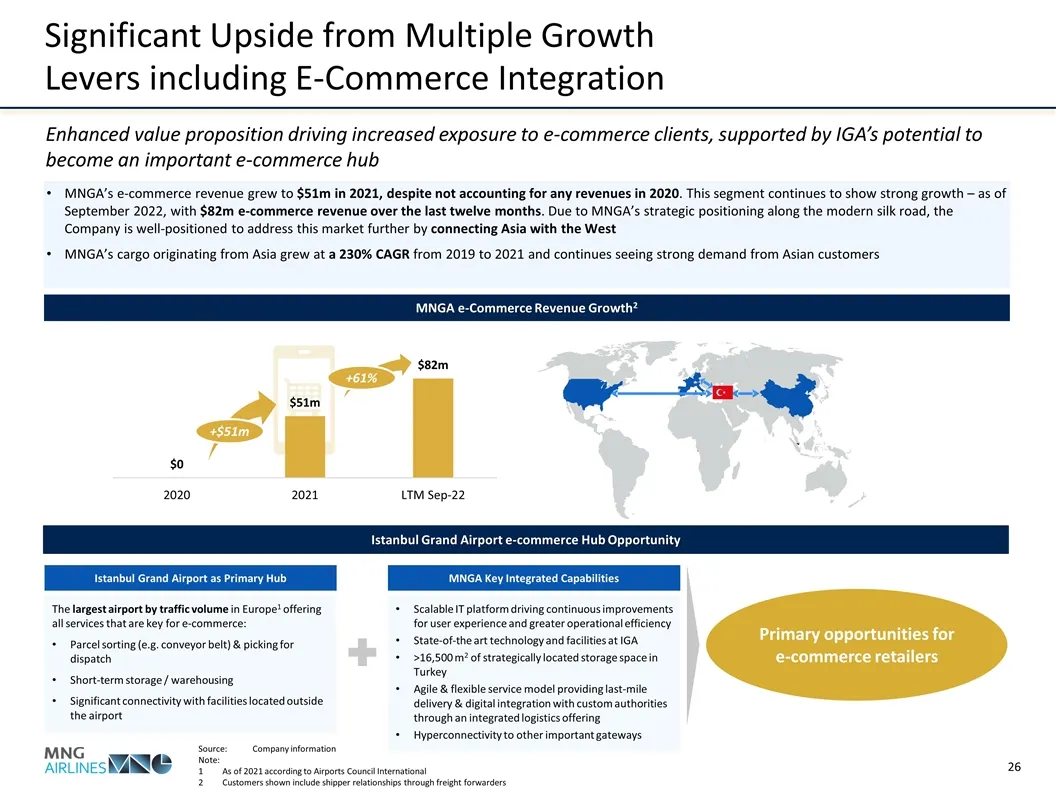
Leading Turkish e-commerce platform Global logistics leader +$51m Significant Upside from Multiple Growth Levers including E-Commerce Integration MNGA’s e-commerce revenue grew to $51m in 2021, despite not accounting for any revenues in 2020. This segment continues to show strong growth – as of Sept
Slide 28: Upside from Growth Levers Including Geographic Expansion & Vertical Integration
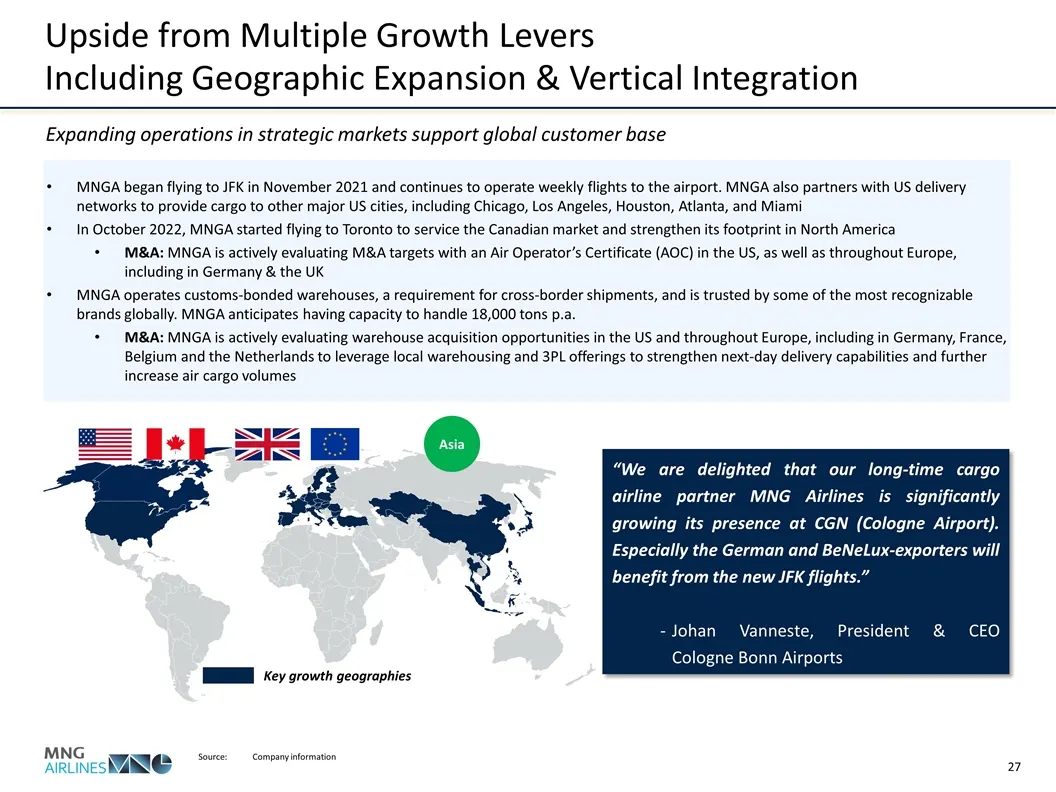
Upside from Multiple Growth Levers Including Geographic Expansion & Vertical Integration MNGA began flying to JFK in November 2021 and continues to operate weekly flights to the airport. MNGA also partners with US delivery networks to provide cargo to other major US cities, including Chicago, Los An
Slide 29: Barriers to Entry Driven by Rights to Slots at Desirable Airports
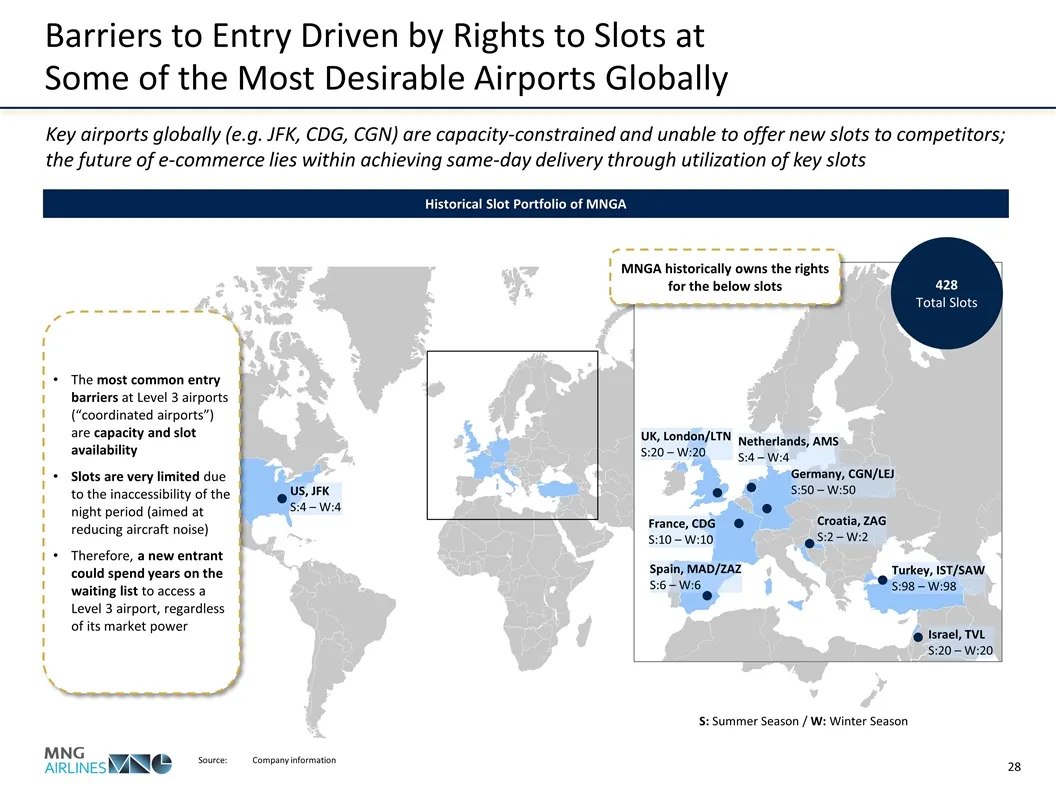
Barriers to Entry Driven by Rights to Slots at Some of the Most Desirable Airports Globally Key airports globally (e.g. JFK, CDG, CGN) are capacity-constrained and unable to offer new slots to competitors; the future of e-commerce lies within achieving same-day delivery through utilization of key sl
Slide 30: Operational Excellence Evidenced by Multiple Awards
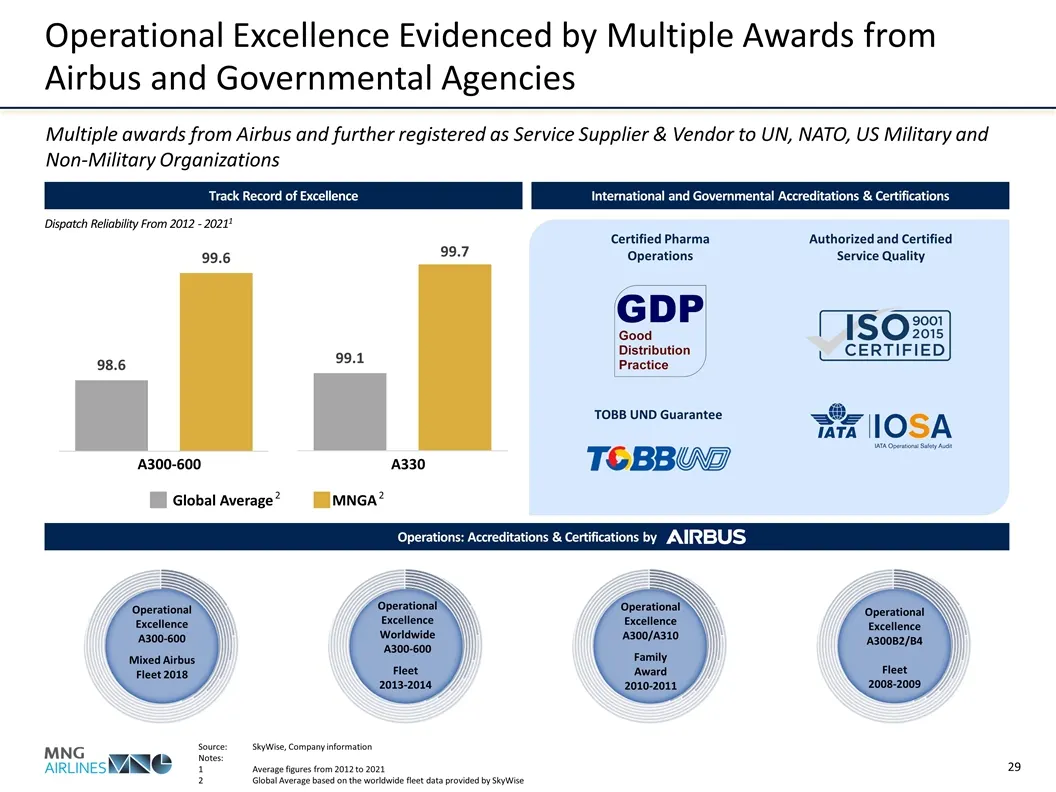
Operational Excellence Evidenced by Multiple Awards from Airbus and Governmental Agencies Multiple awards from Airbus and further registered as Service Supplier & Vendor to UN, NATO, US Military and Non-Military Organizations Operational Excellence A300-600 Mixed Airbus Fleet 2018 Operational Excell
Slide 31: Highly Experienced Management Team with Deep Domain Expertise
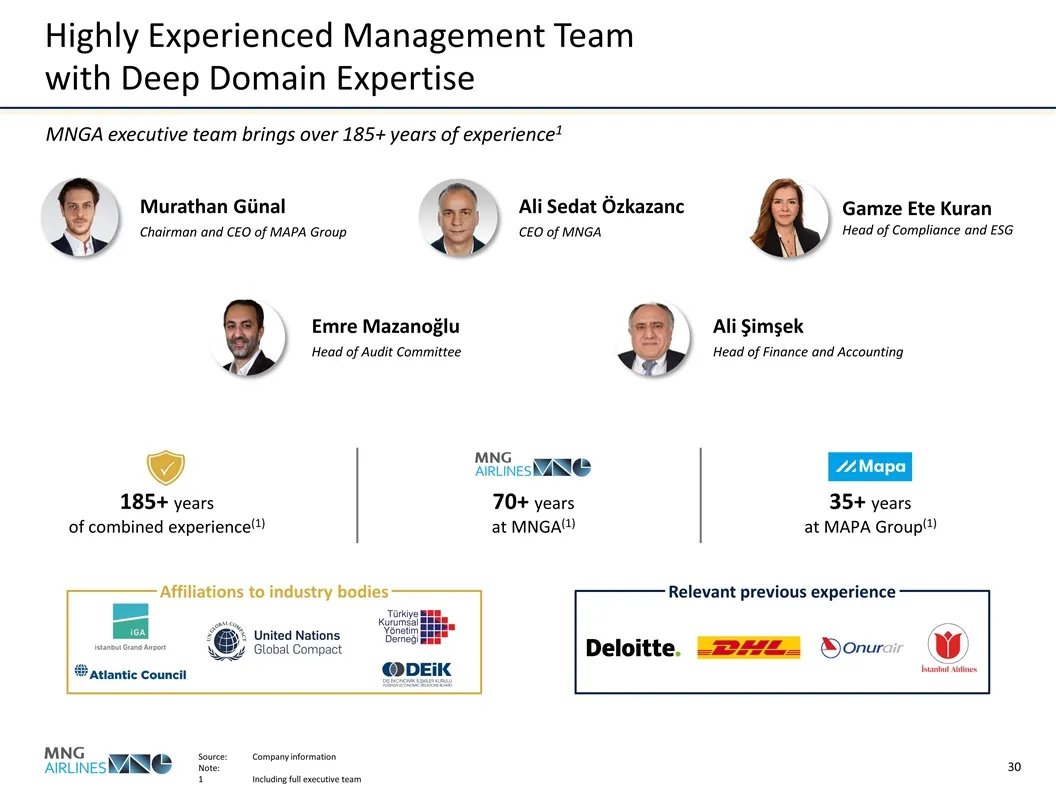
Highly Experienced Management Team with Deep Domain Expertise MNGA executive team brings over 185+ years of experience1 Source:Company information Note: 1Including full executive team Murathan Günal Chairman and CEO of MAPA Group Ali Sedat Özkazanc CEO of MNGA Emre Mazanoğlu Head of Audit Committee
Slide 32: Additional Valuation Materials - Appendix B
Additional Valuation Materials Appendix B
Slide 33: Leading Metrics in the Industry – Growth, Profitability and Pricing Power
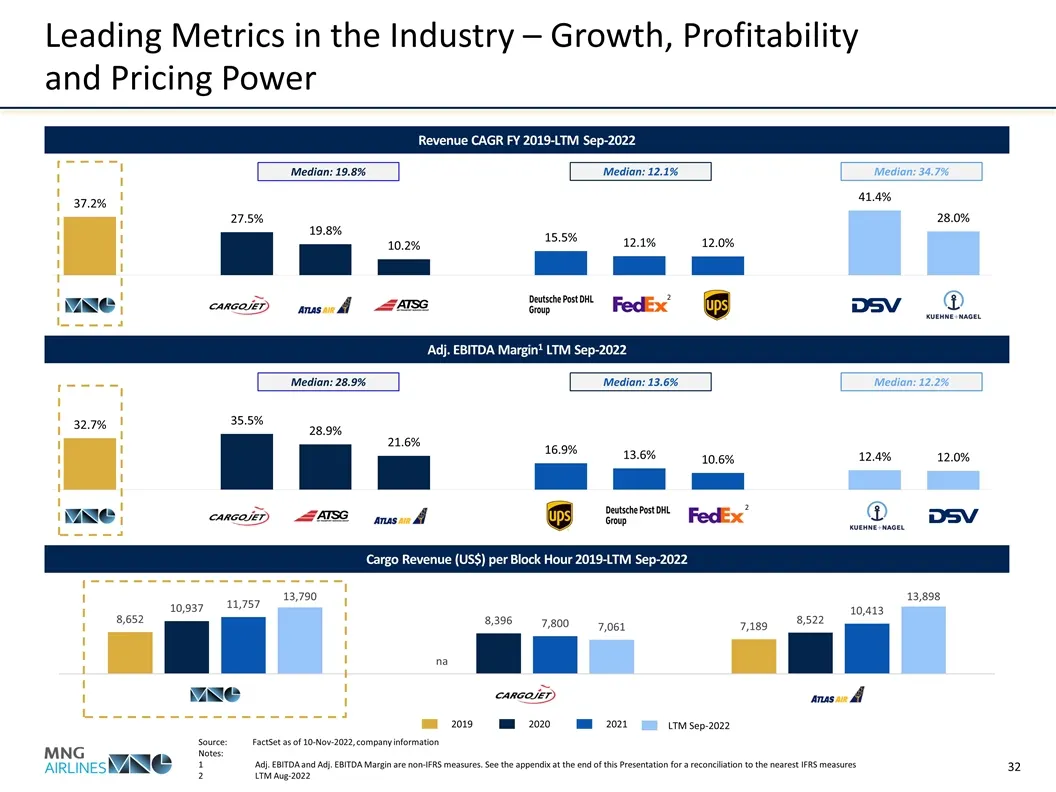
Leading Metrics in the Industry – Growth, Profitability and Pricing Power Median: 28.9% Median: 12.2% Source:FactSet as of 10-Nov-2022, company information Notes: 1Adj. EBITDA and Adj. EBITDA Margin are non-IFRS measures. See the appendix at the end of this Presentation for a reconciliation to the n
Slide 34: Entry Price Point at Substantial Discount to Cargojet
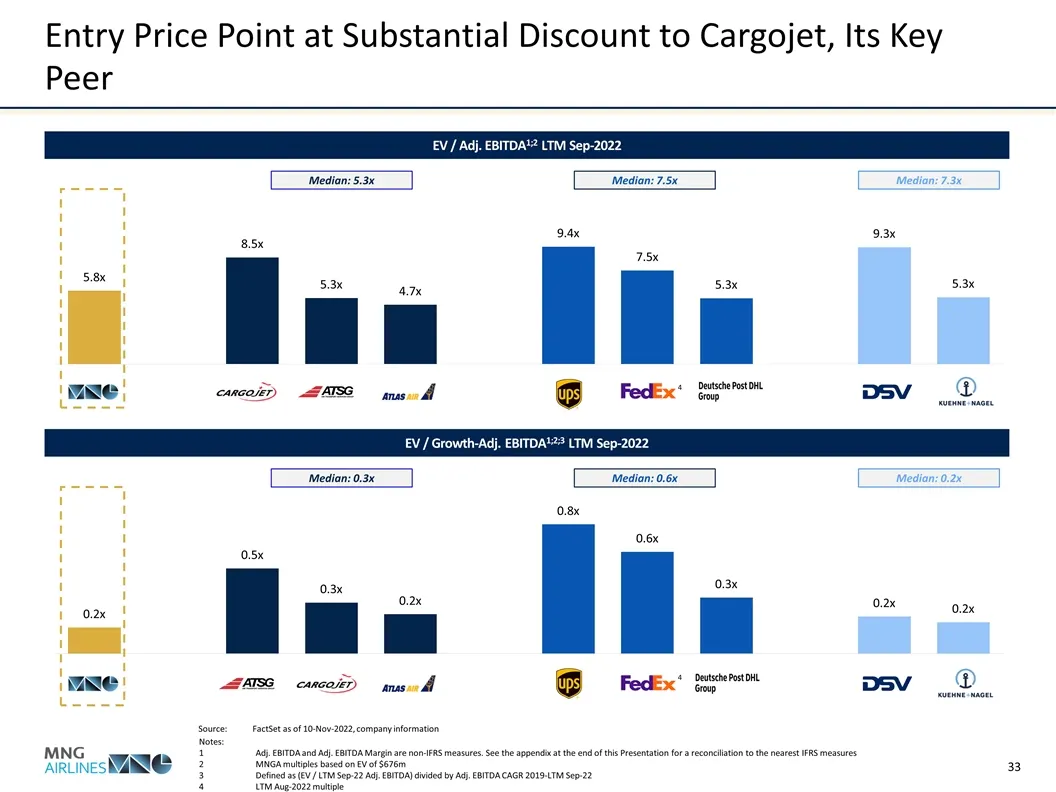
Entry Price Point at Substantial Discount to Cargojet, Its Key Peer Median: 5.3x Median: 7.3x EV / Adj. EBITDA1;2 LTM Sep-2022 Median: 7.5x Median: 0.3x Median: 0.2x EV / Growth-Adj. EBITDA1;2;3 LTM Sep-2022 Median: 0.6x Source:FactSet as of 10-Nov-2022, company information Notes: Adj. EBITDA and Ad
Slide 35: Additional Materials - Appendix C
Additional Materials Appendix C
Slide 36: Long-Haul Fleet Growth for Further Global Connectivity
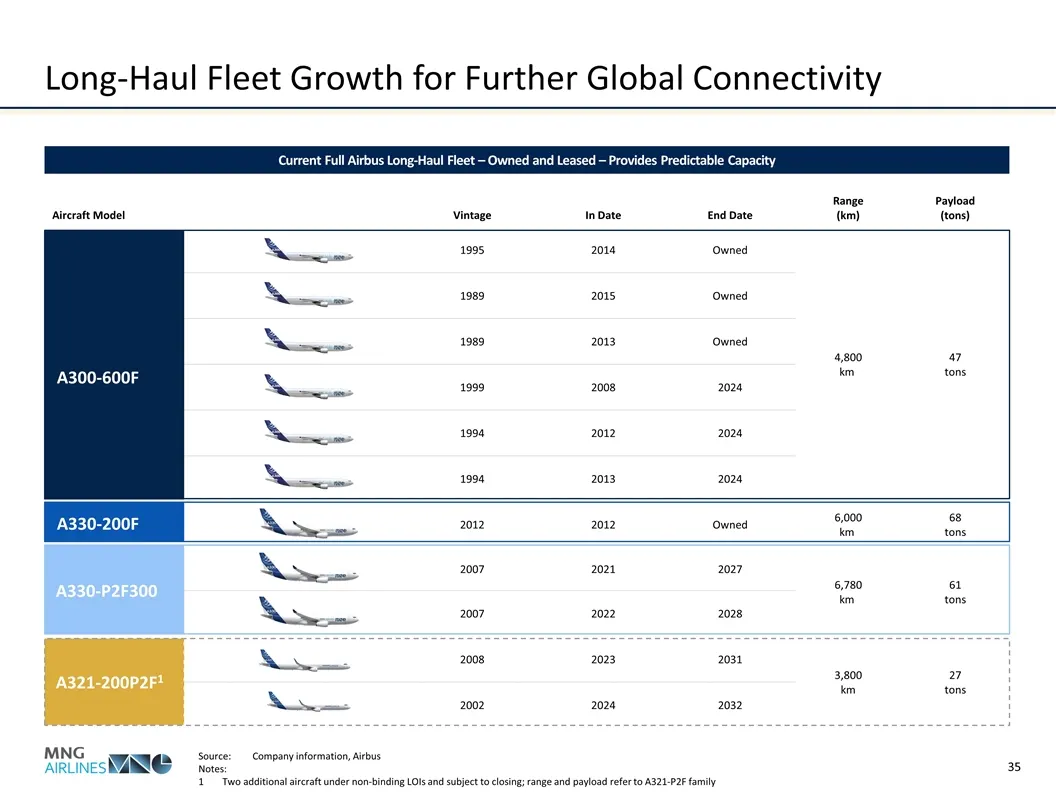
Aircraft Model Vintage In Date End Date Range (km) Payload (tons) 1995 2014 Owned 4,800 km 47 tons 1989 2015 Owned 1989 2013 Owned 1999 2008 2024 1994 2012 2024 1994 2013 2024 2012 2012 Owned 6,000 km 68 tons 2007 2021 2027 6,780 km 61 tons 2007 2022 2028 2008 2023 2031 3,800 km 27 tons 2002 2024 20
Slide 37: MNGA ESG Strategy
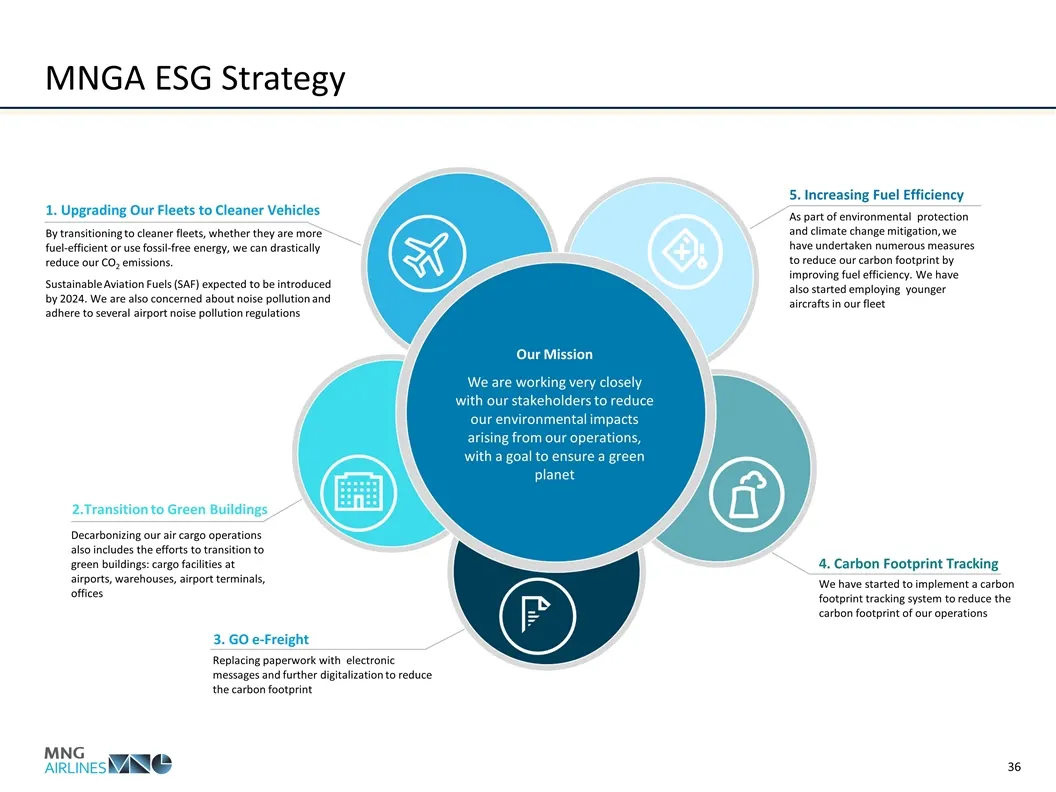
1. Upgrading Our Fleets to Cleaner Vehicles By transitioning to cleaner fleets, whether they are more fuel-efficient or use fossil-free energy, we can drastically reduce our CO2 emissions. Sustainable Aviation Fuels (SAF) expected to be introduced by 2024. We are also concerned about noise pollution
Slide 38: MNGA – Historical Income Statement and Balance Sheet
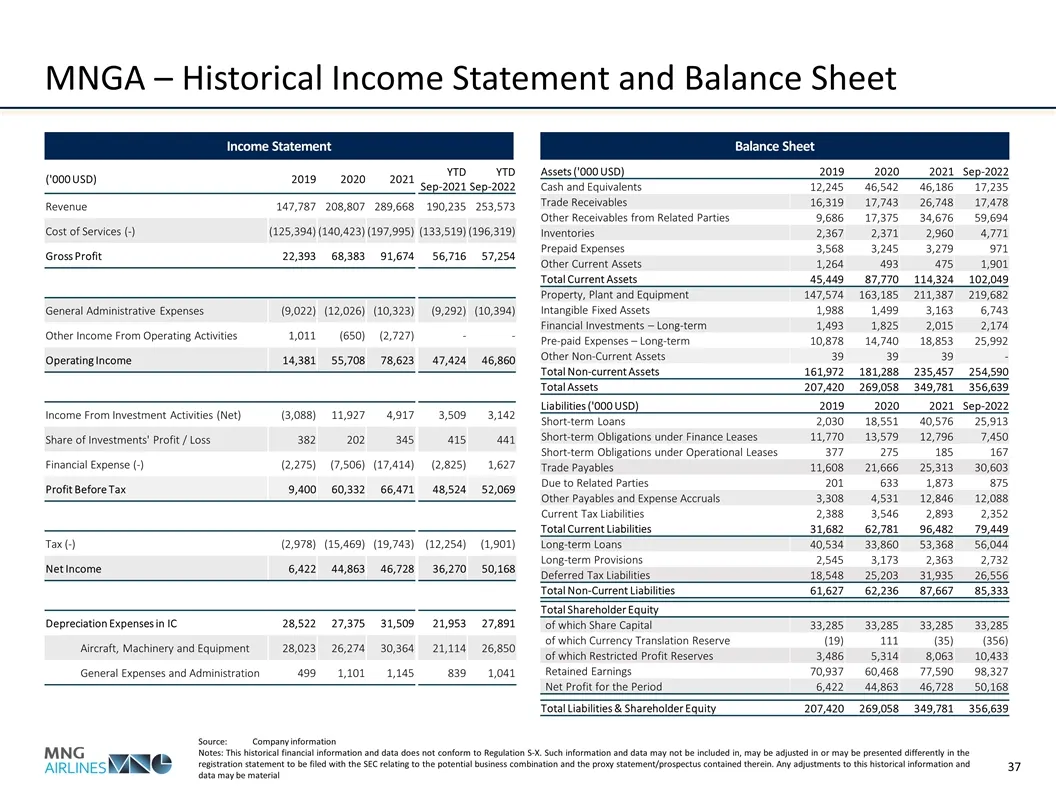
MNGA – Historical Income Statement and Balance Sheet Income Statement Balance Sheet ('000 USD) 2019 2020 2021 YTD Sep-2021 YTD Sep-2022 Revenue 147,787 208,807 289,668 190,235 253,573 Cost of Services (-) (125,394) (140,423) (197,995) (133,519) (196,319) Gross Profit 22,393 68,383 91,674 56,716 57,2
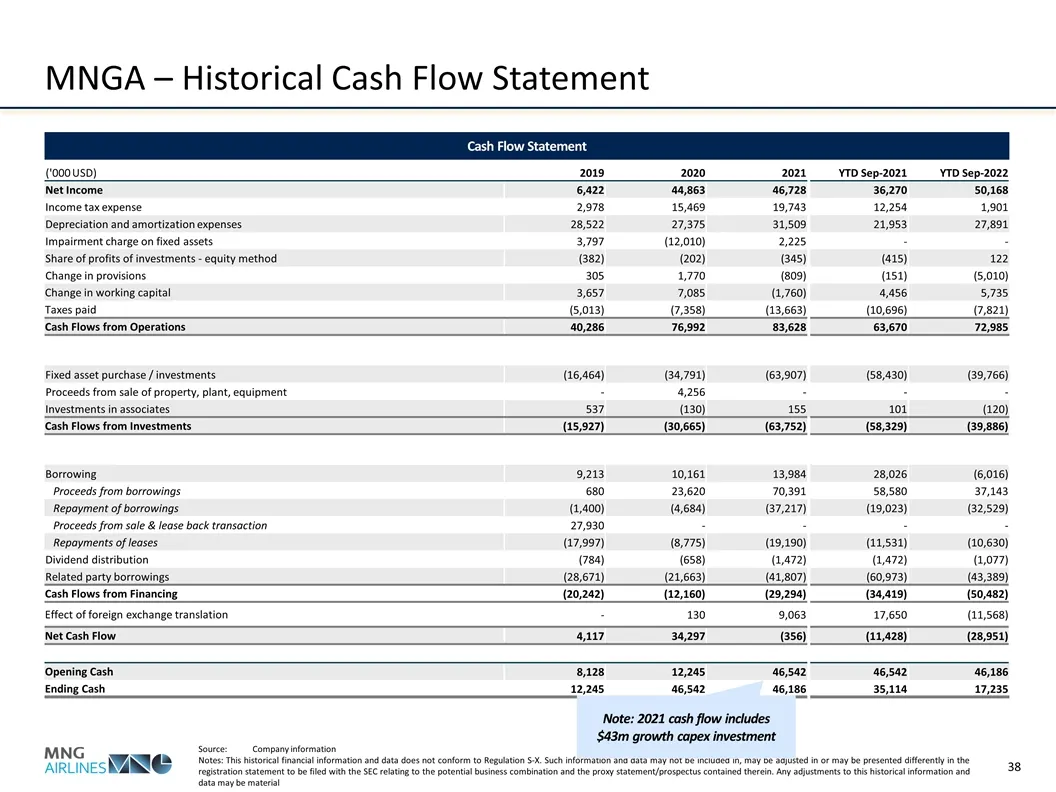
Slide 39: MNGA – Historical Cash Flow Statement
MNGA – Historical Cash Flow Statement Source:Company information Notes: This historical financial information and data does not conform to Regulation S-X. Such information and data may not be included in, may be adjusted in or may be presented differently in the registration statement to be filed wi
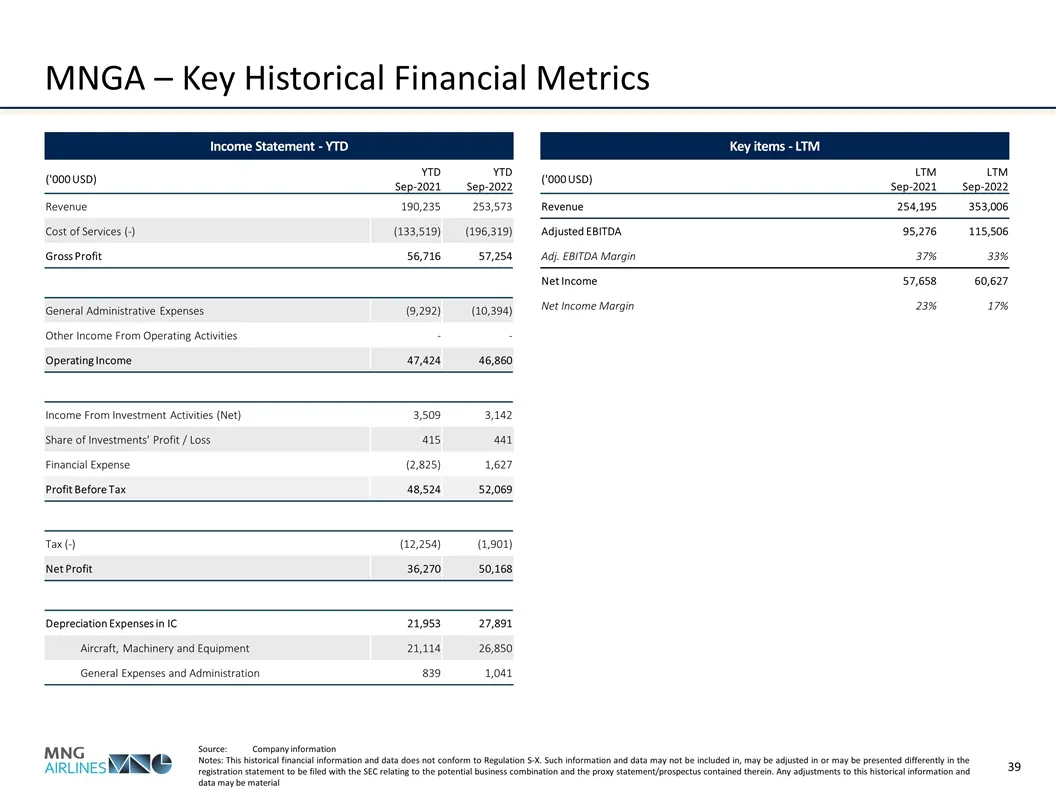
Slide 40: MNGA – Key Historical Financial Metrics
MNGA – Key Historical Financial Metrics Income Statement - YTD ('000 USD) YTD Sep-2021 YTD Sep-2022 Revenue 190,235 253,573 Cost of Services (-) (133,519) (196,319) Gross Profit 56,716 57,254 General Administrative Expenses (9,292) (10,394) Other Income From Operating Activities - - Operating Income
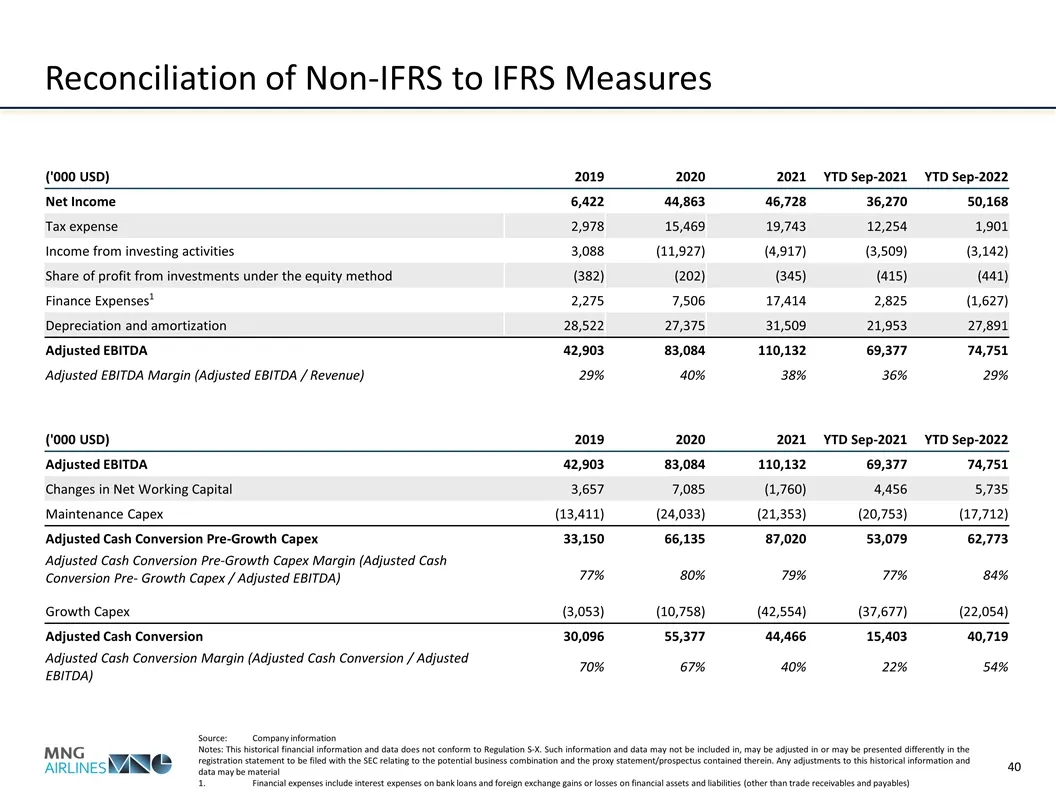
Slide 41: Reconciliation of Non-IFRS to IFRS Measures
Reconciliation of Non-IFRS to IFRS Measures Source:Company information Notes: This historical financial information and data does not conform to Regulation S-X. Such information and data may not be included in, may be adjusted in or may be presented differently in the registration statement to be fi
Slide 42: Industry Outlook - Appendix D
Industry Outlook Appendix D
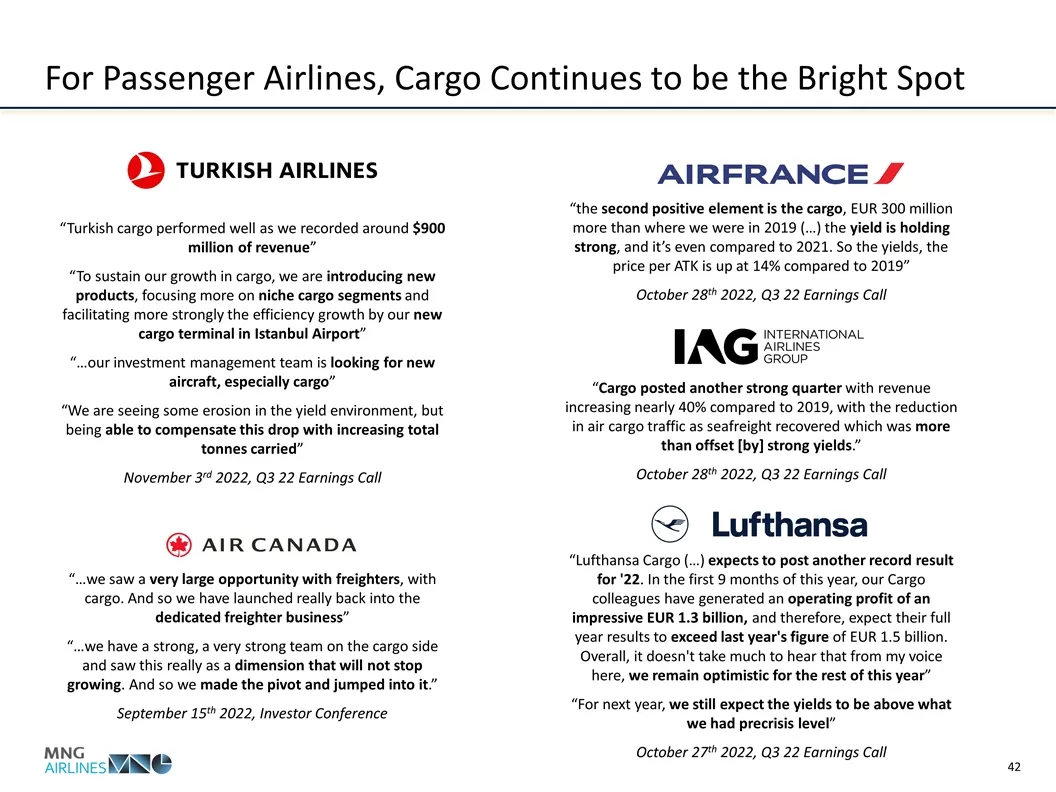
Slide 43: For Passenger Airlines, Cargo Continues to be the Bright Spot
For Passenger Airlines, Cargo Continues to be the Bright Spot “Turkish cargo performed well as we recorded around $900 million of revenue” “To sustain our growth in cargo, we are introducing new products, focusing more on niche cargo segments and facilitating more strongly the efficiency growth by o
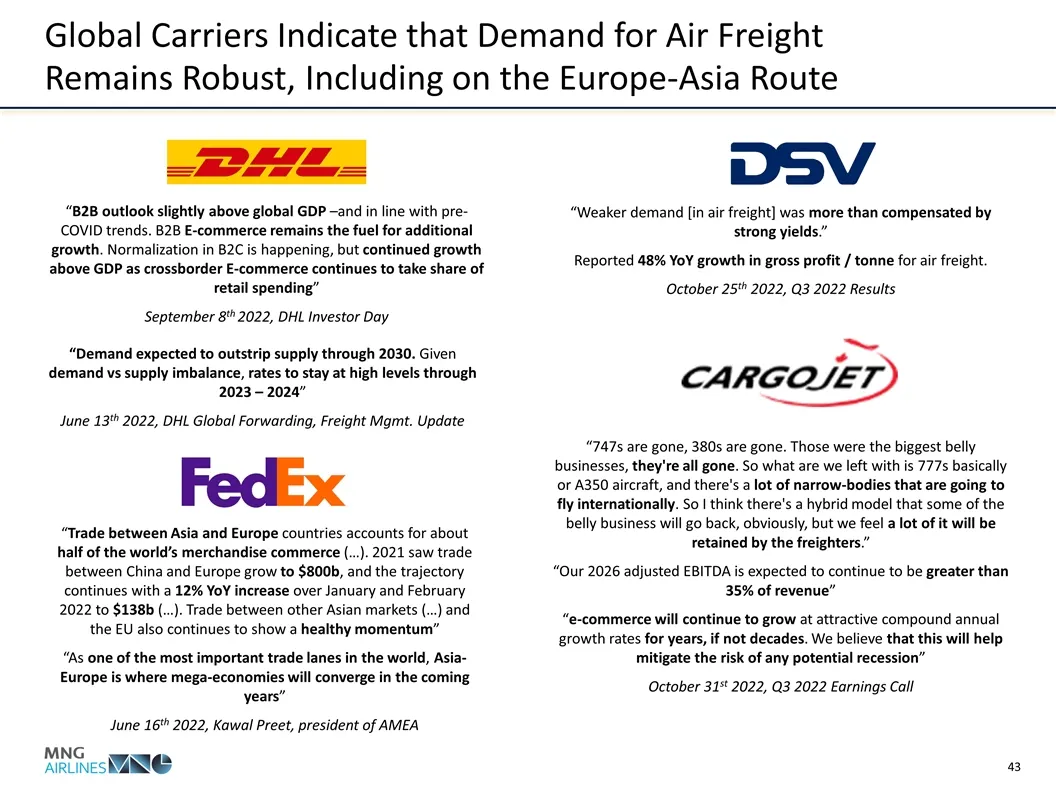
Slide 44: Global Carriers Indicate that Demand for Air Freight Remains Robust
Global Carriers Indicate that Demand for Air Freight Remains Robust, Including on the Europe-Asia Route “B2B outlook slightly above global GDP –and in line with pre-COVID trends. B2B E-commerce remains the fuel for additional growth. Normalization in B2C is happening, but continued growth above GDP
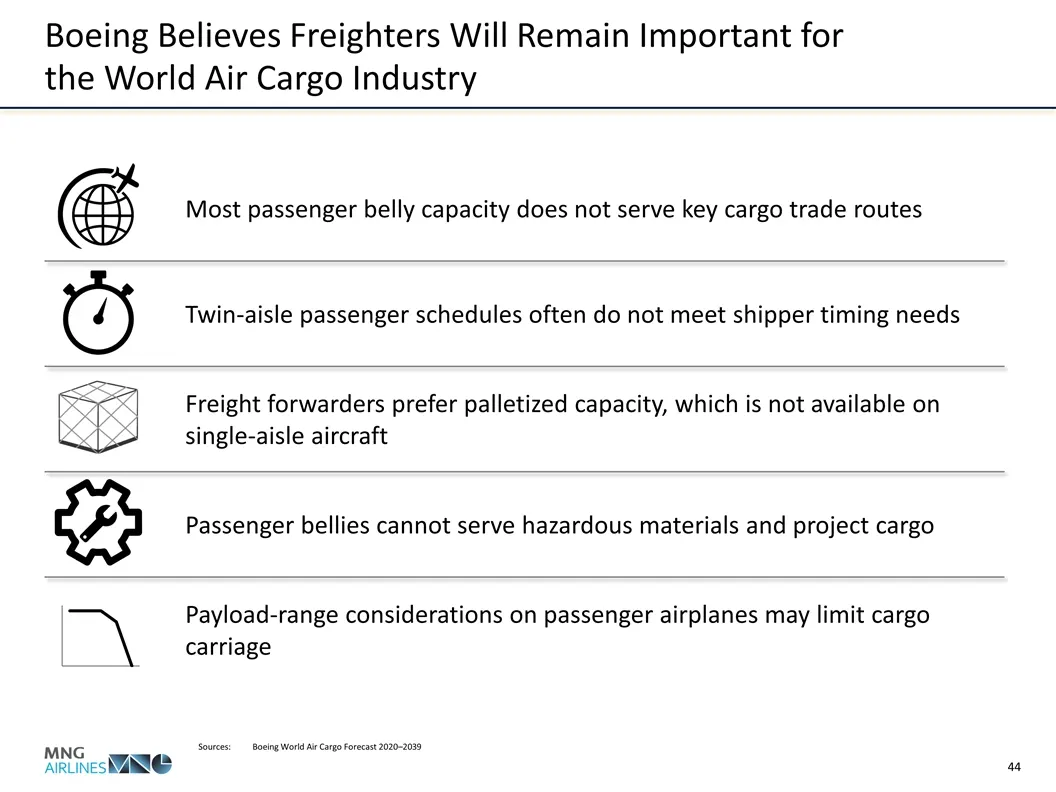
Slide 45: Boeing Believes Freighters Will Remain Important for Air Cargo
Boeing Believes Freighters Will Remain Important for the World Air Cargo Industry Sources:Boeing World Air Cargo Forecast 2020–2039 Most passenger belly capacity does not serve key cargo trade routes Twin-aisle passenger schedules often do not meet shipper timing needs Freight forwarders prefer pall
Slide 46
Slide 47: Risks Related to MNGA
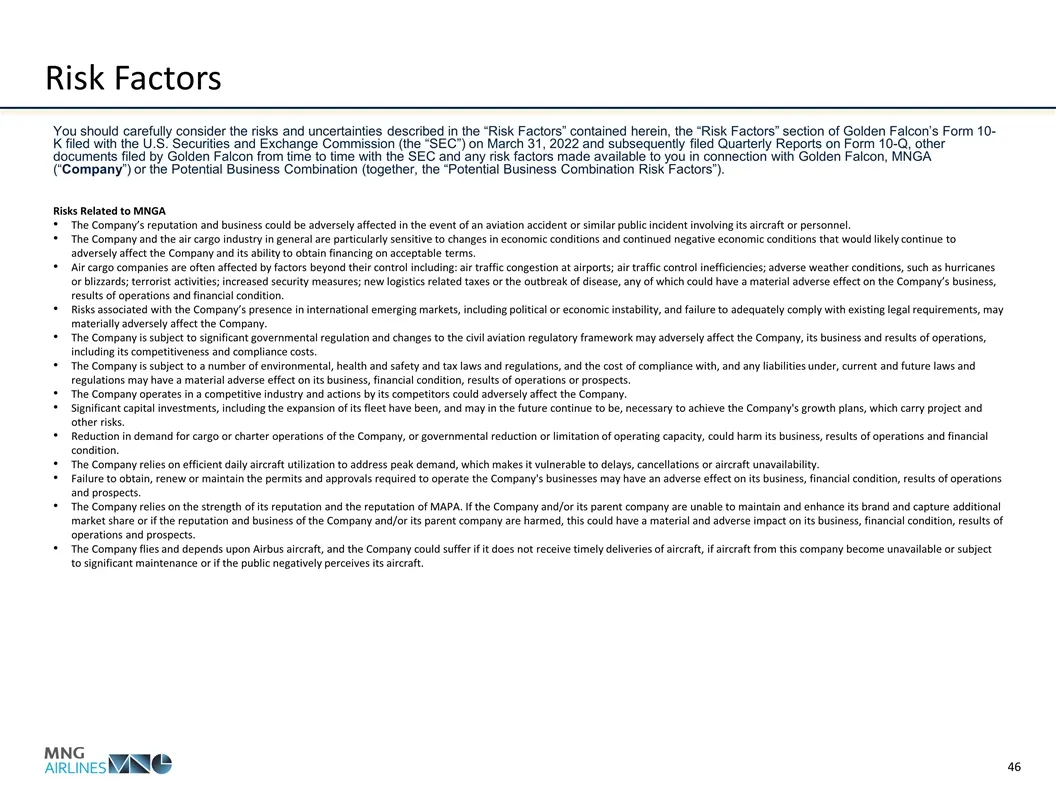
Risks Related to MNGA The Company’s reputation and business could be adversely affected in the event of an aviation accident or similar public incident involving its aircraft or personnel. The Company and the air cargo industry in general are particularly sensitive to changes in economic conditions
Slide 48: Risks Related to MNGA (Cont’d)
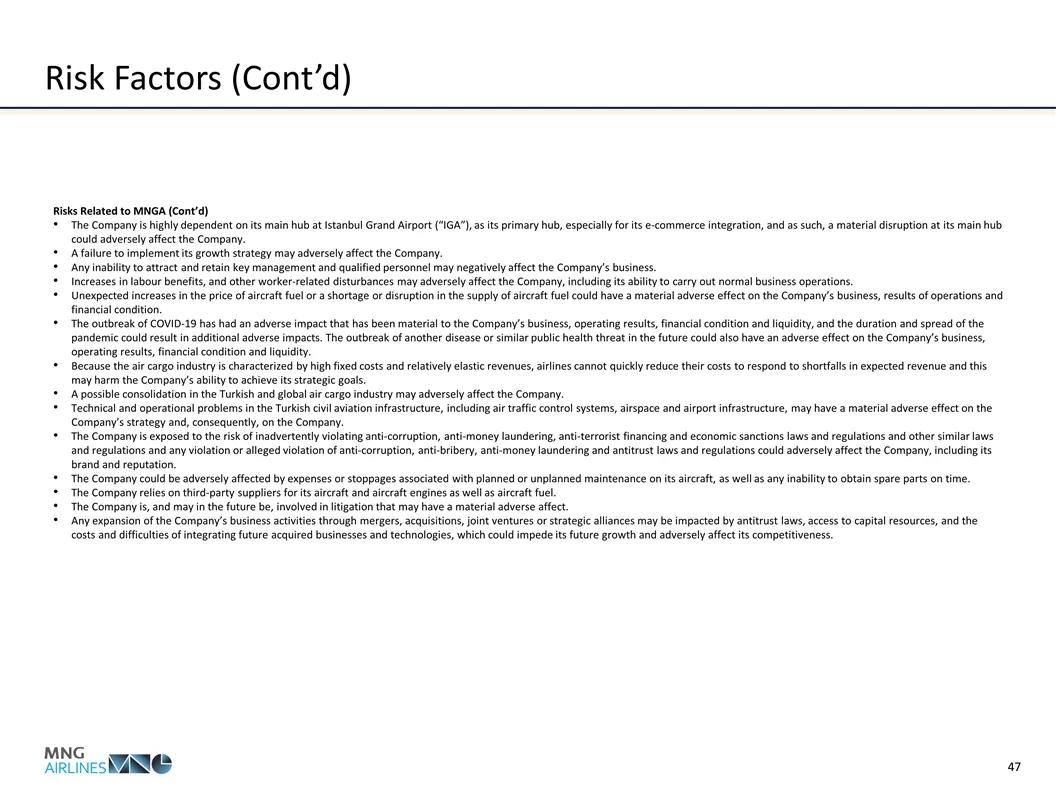
Risks Related to MNGA (Cont’d) The Company is highly dependent on its main hub at Istanbul Grand Airport (“IGA”), as its primary hub, especially for its e-commerce integration, and as such, a material disruption at its main hub could adversely affect the Company. A failure to implement its growth st
Slide 49: Risks Related to MNGA (Cont’d)
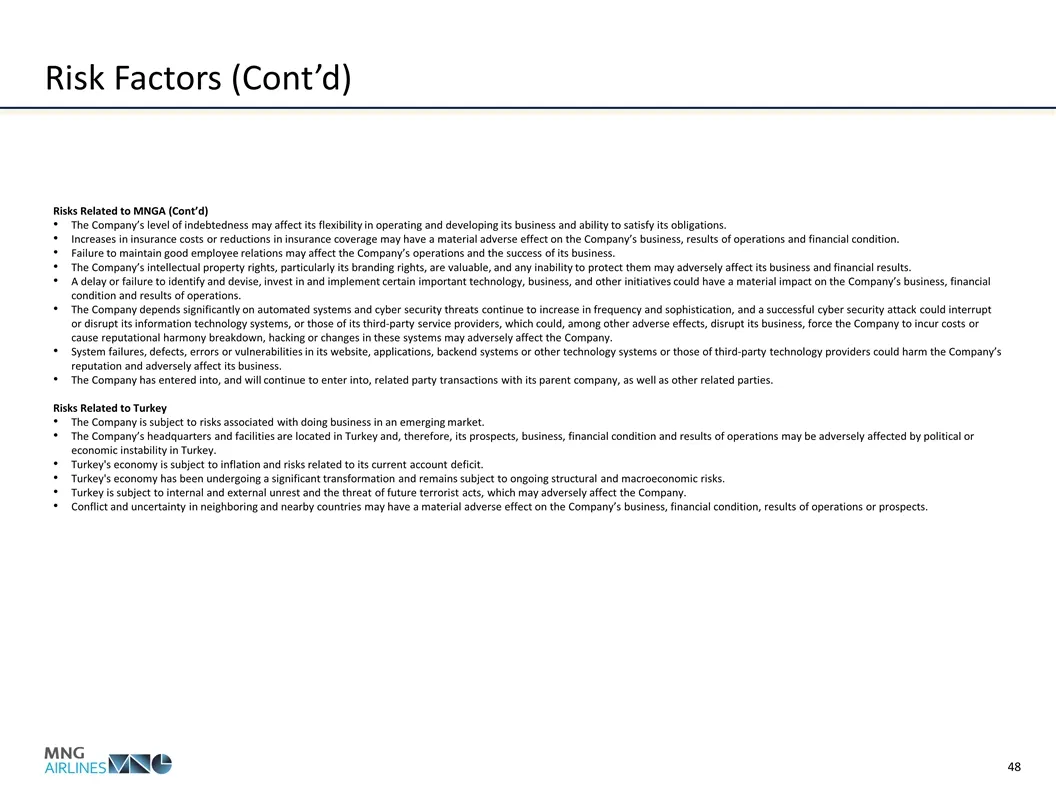
Risks Related to MNGA (Cont’d) The Company’s level of indebtedness may affect its flexibility in operating and developing its business and ability to satisfy its obligations. Increases in insurance costs or reductions in insurance coverage may have a material adverse effect on the Company’s business
Slide 50: Risks Related to Operating as a Public Company
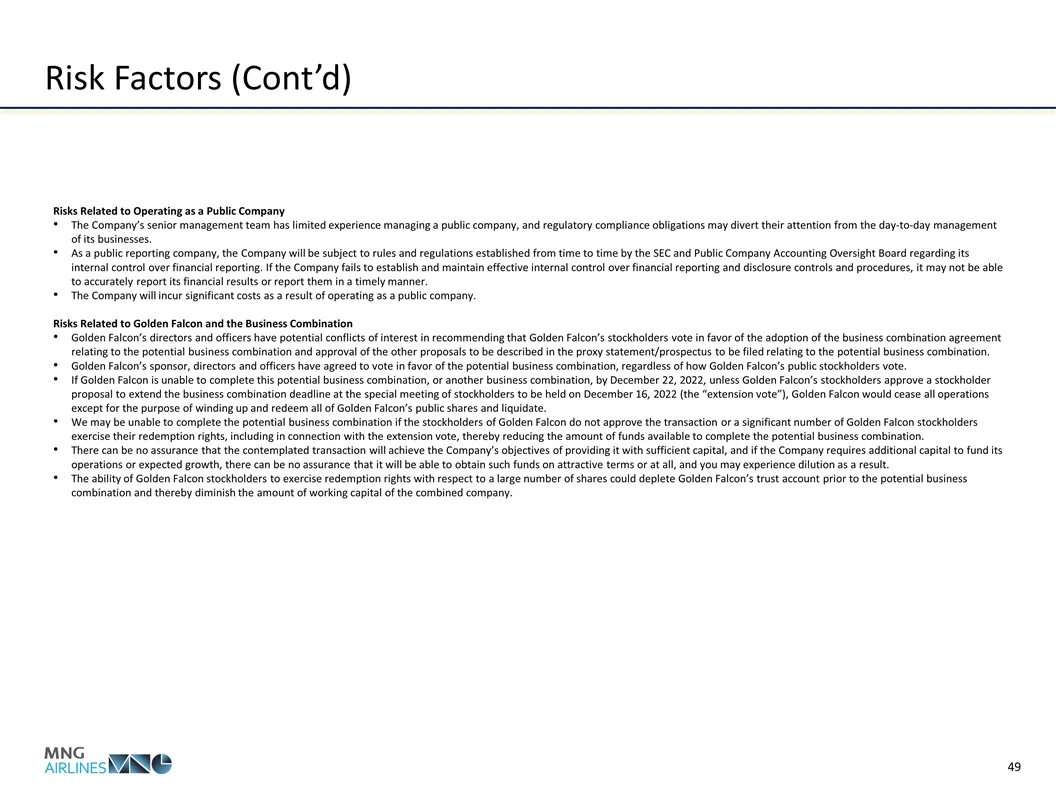
Risks Related to Operating as a Public Company The Company’s senior management team has limited experience managing a public company, and regulatory compliance obligations may divert their attention from the day-to-day management of its businesses. As a public reporting company, the Company will be
Slide 51: Risks Related to Golden Falcon and the Potential Business Combination (Cont’d)
Risks Related to Golden Falcon and the Potential Business Combination (Cont’d) There can be no assurance that the potential business combination will achieve the Company’s objectives of providing it with sufficient capital, and if the Company requires additional capital to fund its operations or exp
Slide 52: Risks Related to Golden Falcon and the Business Combination (Cont’d)
Risks Related to Golden Falcon and the Business Combination (Cont’d) Golden Falcon is dependent upon its directors and officers and their loss could adversely affect Golden Falcon’s ability to complete the potential business combination. Golden Falcon’s sponsor, directors, officers and their affilia
Slide 53: Risks Related to an Investment in MNGA Following the Business Combination
Risks Related to an Investment in MNGA Following the Business Combination MNGA will qualify as a foreign private issuer within the meaning of the rules under the Exchange Act, and as such MNGA will be exempt from certain provisions applicable to United States domestic public companies. As a company
Source: SEC EDGAR · 8-K filed Dec 7, 2022