Village Bank and Trust Financial
Village Bank and Trust Financial — Investor Presentation (August 2014)
24 slides from Village Bank and Trust Financial's investor presentation, Aug 11, 2014
Slide 1: Investor Presentation August and September 2014
1 Investor Presentation August and September 2014
Slide 2: Forward-Looking Statements
2 Forward - Looking Statements This investor presentation contains forward - looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward - looking statements include, but are not limited to, statements about ( i ) the Company’s plans, objectives, expe
Slide 3: High Quality Franchise, Capable Management, Sound Plan
√ High Quality Franchise in a Great Market √ Committed & Capable Management √ Sound Plan – Solid Progress – Back on Offense √ Positive Leverage for Earnings & Book Value 3
Slide 4: Highlights: Village Bank Franchise
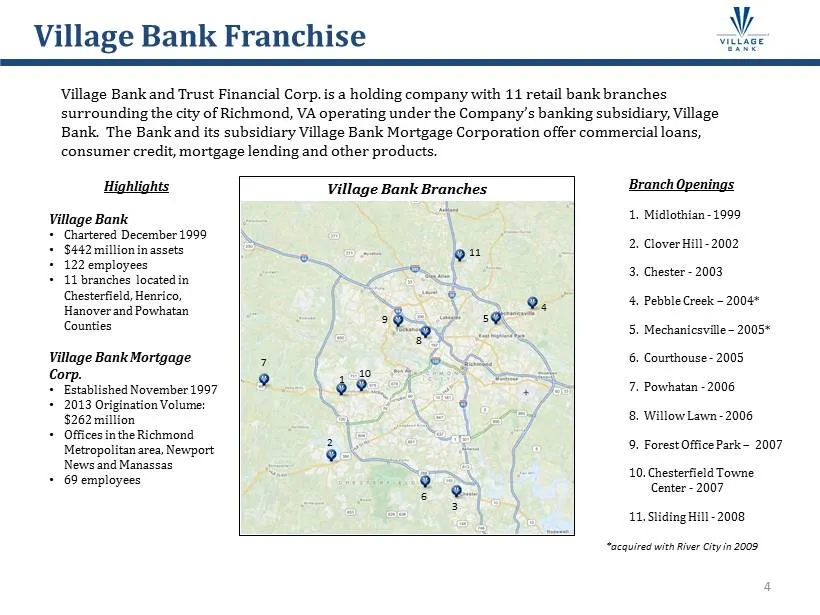
Highlights Village Bank • Chartered December 1999 • $442 million in assets • 122 employees • 11 branches located in Chesterfield, Henrico, Hanover and Powhatan Counties Village Bank Mortgage Corp. • Established November 1997 • 2013 Origination Volume: $262 million • Offices in the Richmond Metropoli
Slide 5: What We Are
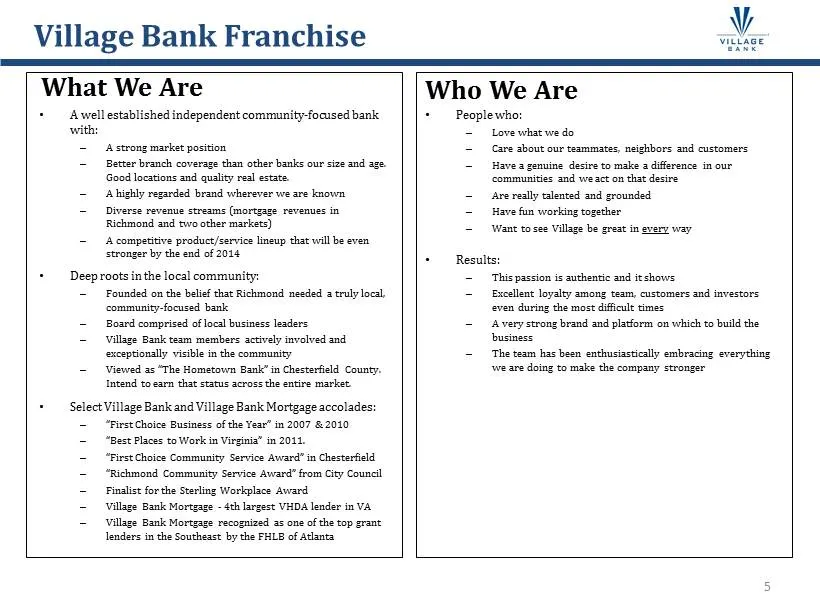
What We Are • A well established independent community - focused bank with: – A strong market position – Better branch coverage than other banks our size and age. Good locations and quality real estate. – A highly regarded brand wherever we are known – Diverse revenue streams (mortgage revenues in R
Slide 6: Central Virginia Market & Village Bank Share
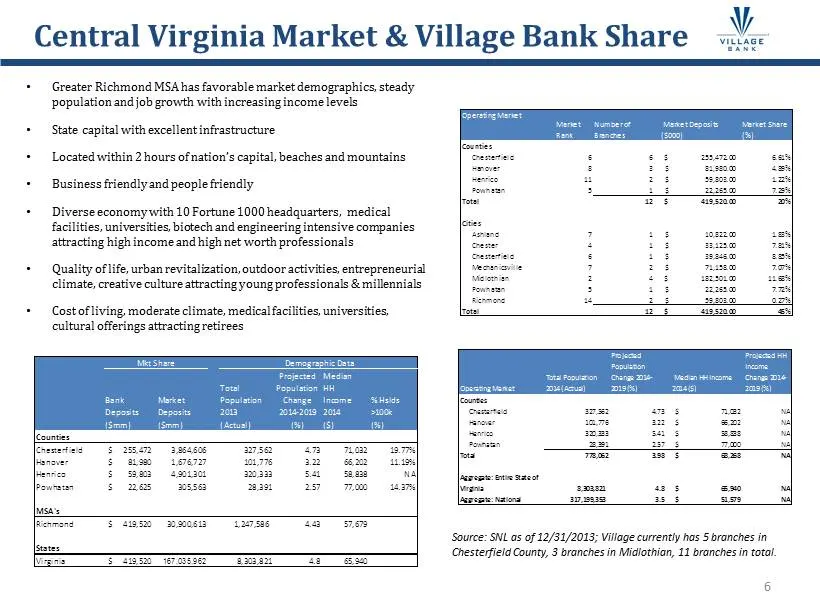
Central Virginia Market & Village Bank Share • Greater Richmond MSA has favorable market demographics, steady population and job growth with increasing income levels • State capital with excellent infrastructure • Located within 2 hours of nation’s capital, beaches and mountains • Business friendly
Slide 7: Deposit Market Share by County
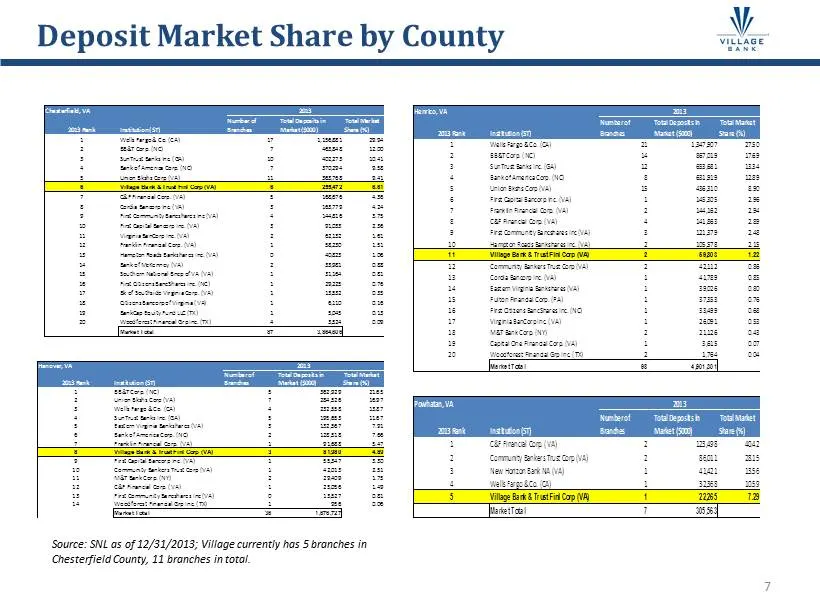
Deposit Market Share by County Chesterfield, VA 2013 Rank Institution (ST) Number of Branches Total Deposits in Market ($000) Total Market Share (%) 1 Wells Fargo & Co. (CA) 17 1,156,881 29.94 2 BB&T Corp. (NC) 7 463,848 12.00 3 SunTrust Banks Inc. (GA) 10 402,273 10.41 4 Bank of America Corp. (NC)
Slide 8: Executive Management
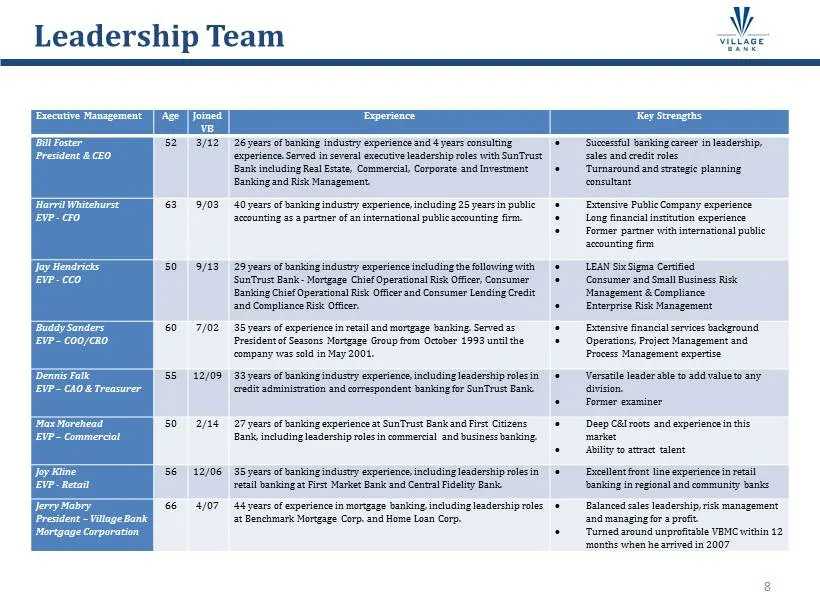
Executive Management Age Joined VB Experience Key Strengths Bill Foster President & CEO 52 3/12 26 years of banking industry experience and 4 years consulting experience. S erved in several executive leadership roles with SunTrust Bank including Real Estate, Commercial, Corporate and Investment Bank
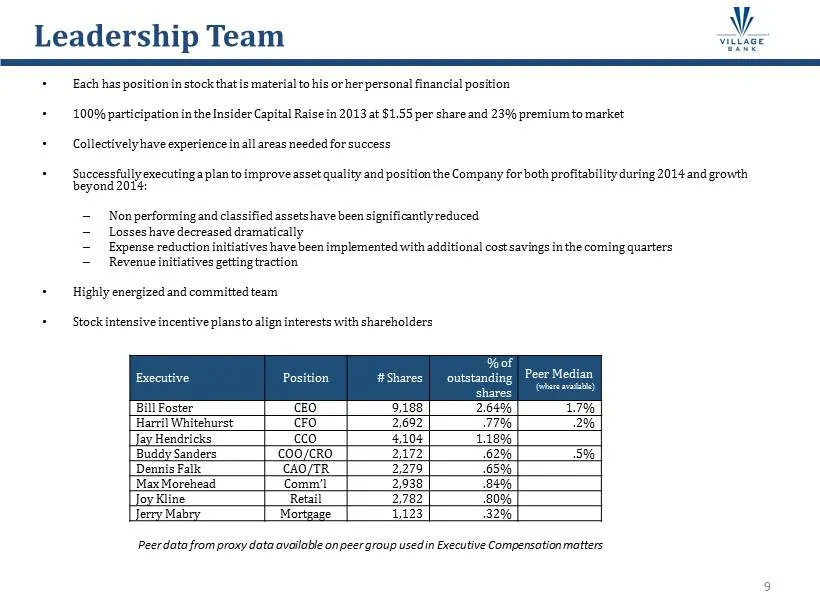
Slide 9: Leadership Team
• Each has position in stock that is material to his or her personal financial position • 100% participation in the Insider Capital Raise in 2013 at $1.55 per share and 23% premium to market • Collectively have experience in all areas needed for success • Successfully executing a plan to improve ass
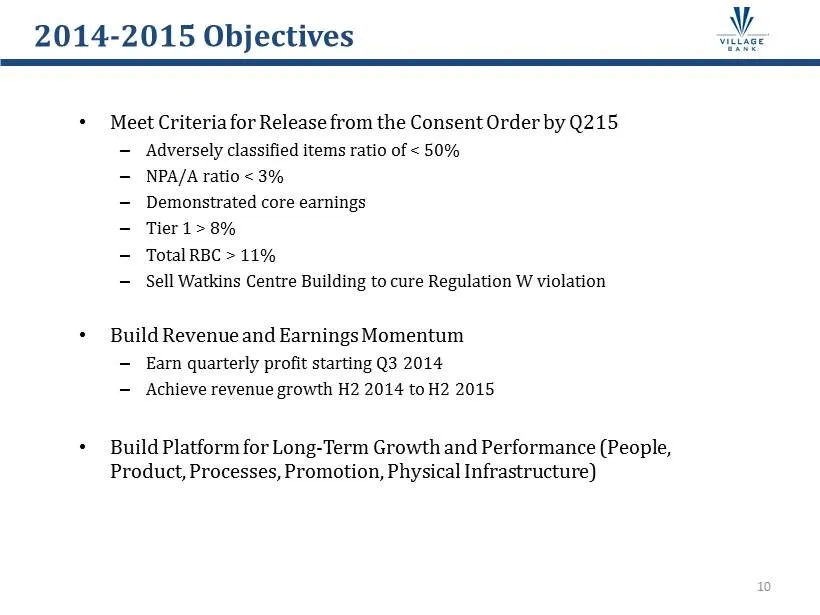
Slide 10: 2014-2015 Objectives
• Meet Criteria for Release from the Consent Order by Q215 – Adversely classified items ratio of < 50% – NPA/A ratio < 3% – Demonstrated core earnings – Tier 1 > 8% – Total RBC > 11% – Sell Watkins Centre Building to cure Regulation W violation • Build Revenue and Earnings Momentum – Earn quarterly
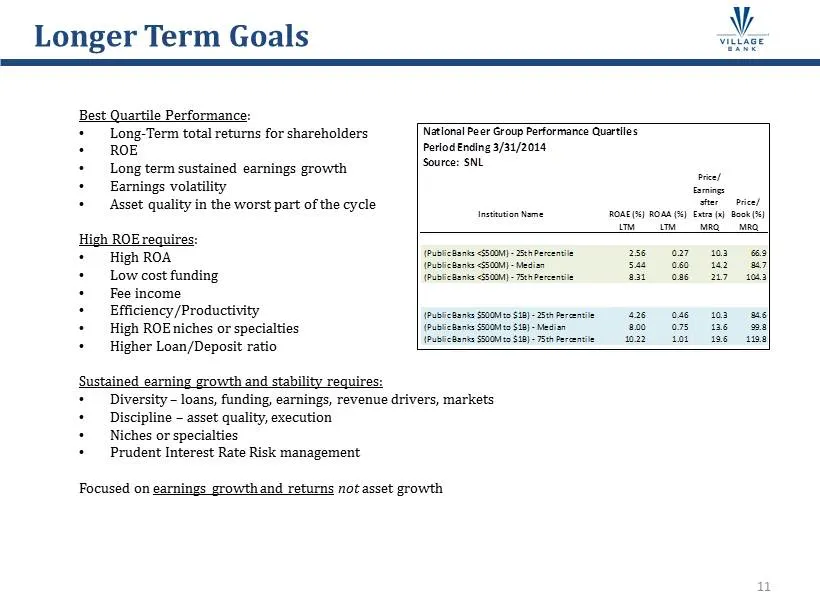
Slide 11: Longer Term Goals
Best Quartile Performance : • Long - Term total returns for shareholders • ROE • Long term sustained earnings growth • Earnings volatility • Asset quality in the worst part of the cycle High ROE requires : • High ROA • Low cost funding • Fee income • Efficiency/Productivity • High ROE niches or spec
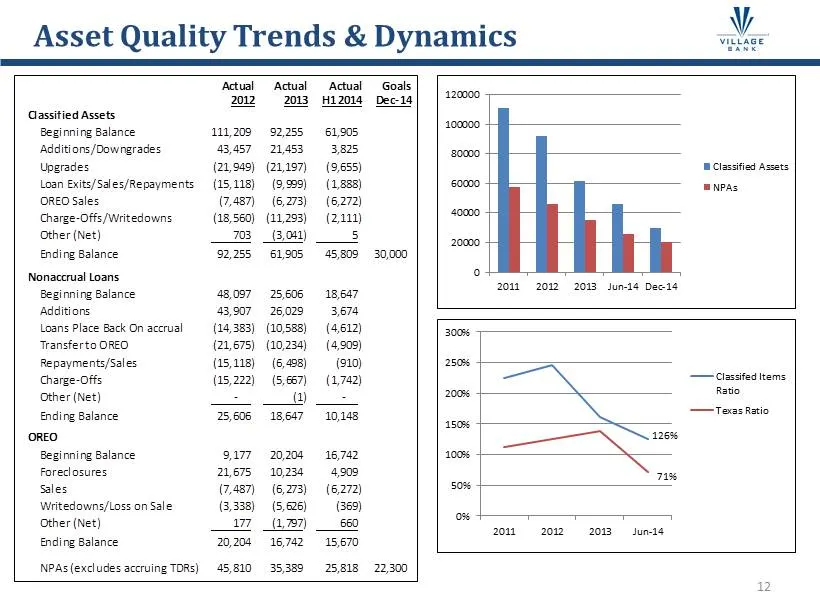
Slide 12: Asset Quality Trends & Dynamics
Asset Quality Trends & Dynamics 12 Actual Actual Actual Goals 2012 2013 H1 2014 Dec-14 Classified Assets Beginning Balance 111,209 92,255 61,905 Additions/Downgrades 43,457 21,453 3,825 Upgrades (21,949) (21,197) (9,655) Loan Exits/Sales/Repayments (15,118) (9,999) (1,888) OREO Sales (7,487) (6,273)
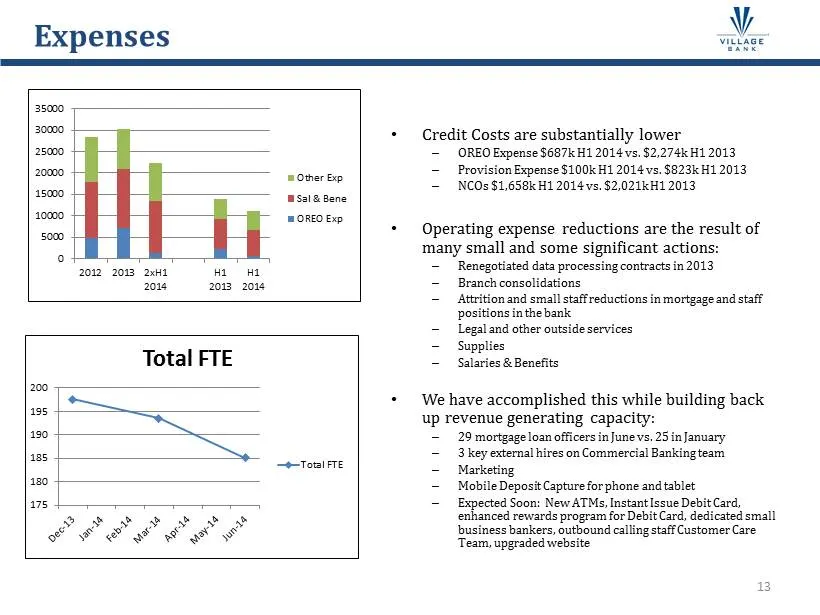
Slide 13: Credit Costs and Operating Expense Reductions
• Credit Costs are substantially lower – OREO Expense $687k H1 2014 vs. $2,274k H1 2013 – Provision Expense $100k H1 2014 vs. $823k H1 2013 – NCOs $1,658k H1 2014 vs. $2,021k H1 2013 • Operating expense reductions are the result of many small and some significant actions: – Renegotiated data process
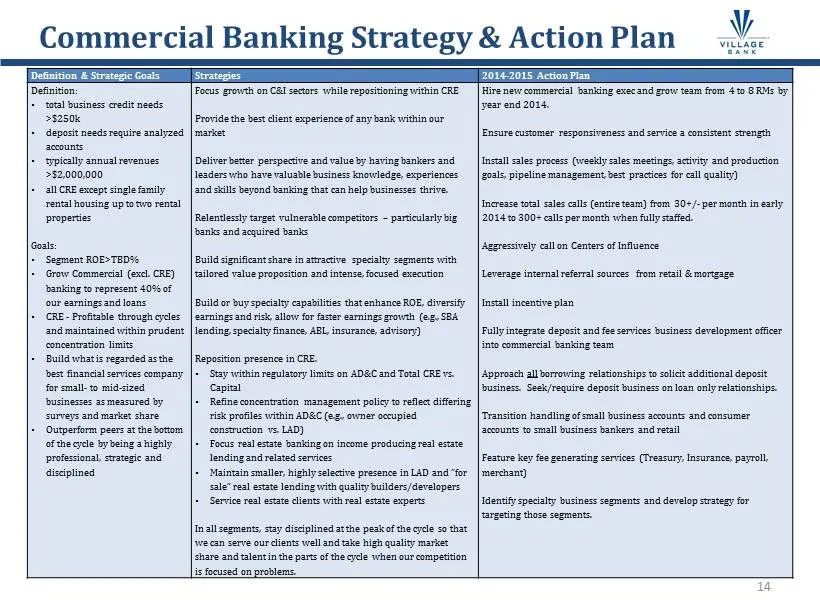
Slide 14: Commercial Banking Strategy & Action Plan
Commercial Banking Strategy & Action Plan Definition & Strategic Goals Strategies 2014 - 2015 Action Plan Definition: • total business credit needs >$250k • deposit needs require analyzed accounts • typically annual revenues >$2,000,000 • all CRE except single family rental housing up to two rental
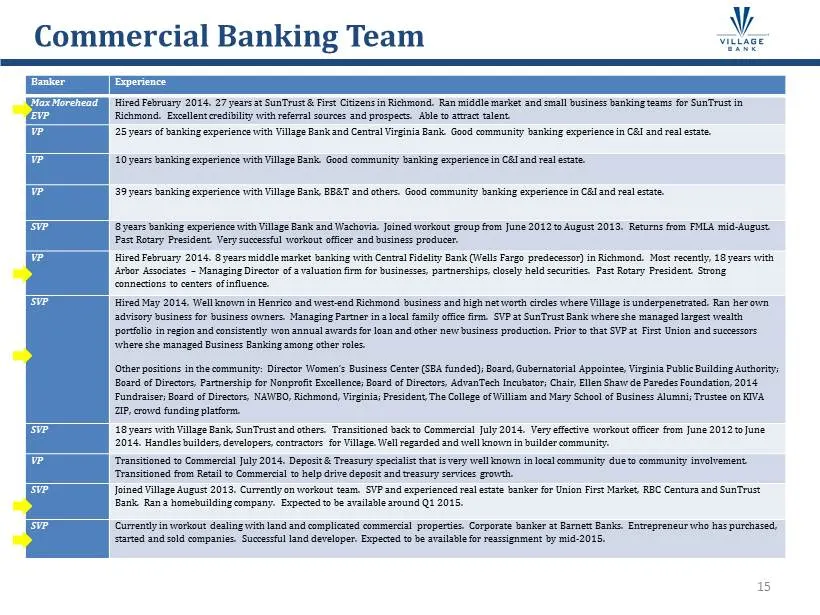
Slide 15: Banker Experience
Banker Experience Max Morehead EVP Hired February 2014 . 27 years at SunTrust & First Citizens in Richmond. Ran middle market and small business banking teams for SunTrust in Richmond. Excellent credibility with referral sources and prospects. Able to attract talent. VP 25 years of banking experienc
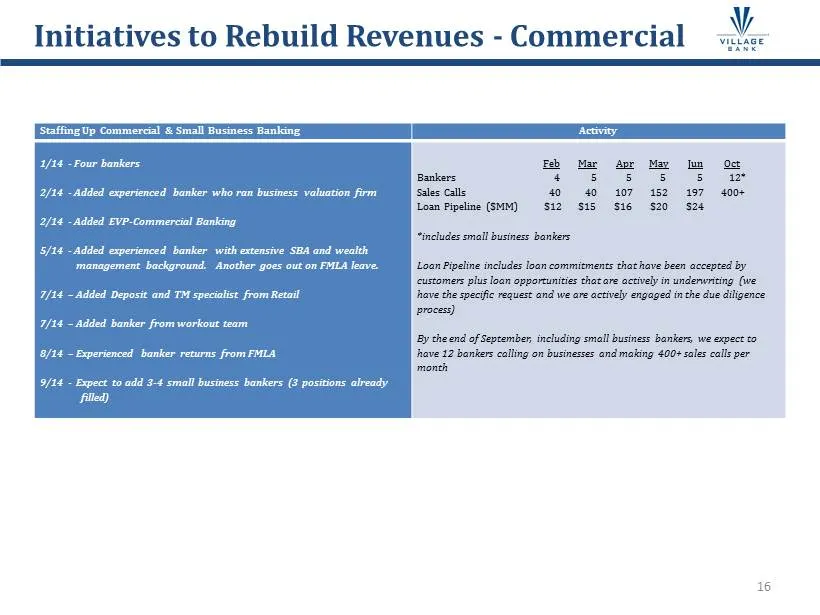
Slide 16: Staffing Up Commercial & Small Business Banking
Staffing Up Commercial & Small Business Banking Activity 1/14 - Four bankers 2/14 - Added experienced banker who ran business valuation firm 2/14 - Added EVP - Commercial Banking 5/14 - Added experienced banker with extensive SBA and wealth management background. Another goes out on FMLA leave. 7/14
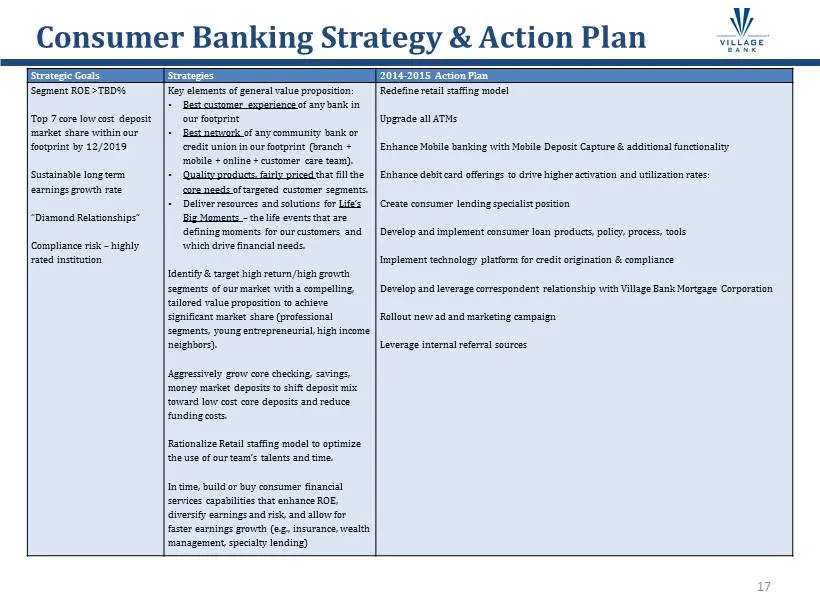
Slide 17: Strategic Goals and Strategies 2014-2015
17 Strategic Goals Strategies 2014 - 2015 Action Plan Segment ROE >TBD% Top 7 core low cost deposit market share within our footprint by 12/2019 Sustainable long term earnings growth rate “ Diamond Relationships” Compliance risk – highly rated institution Key elements of general value proposition: •
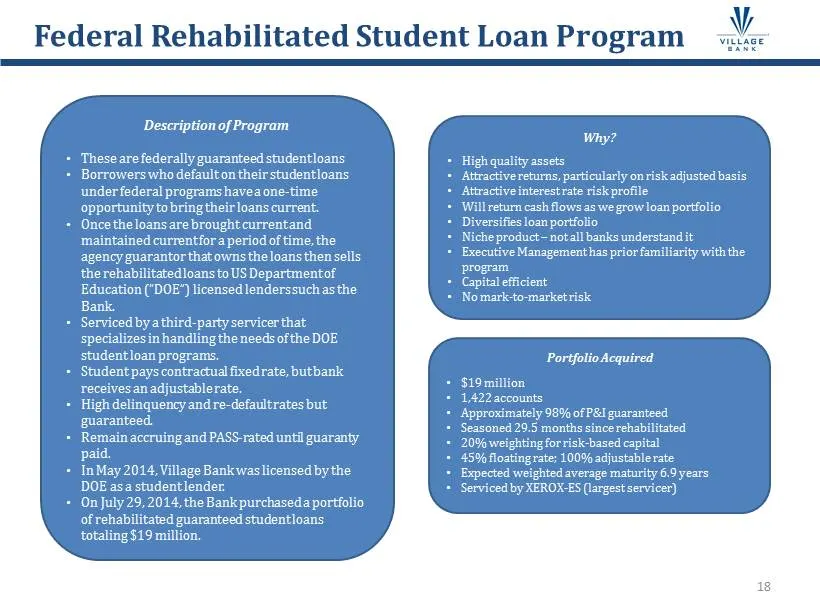
Slide 18: Description of Program: Guaranteed Student Loans
Description of Program • These are federally guaranteed student loans • Borrowers who default on their student loans under federal programs have a one - time opportunity to bring their loans current. • Once the loans are brought current and maintained current for a period of time, the agency guarant
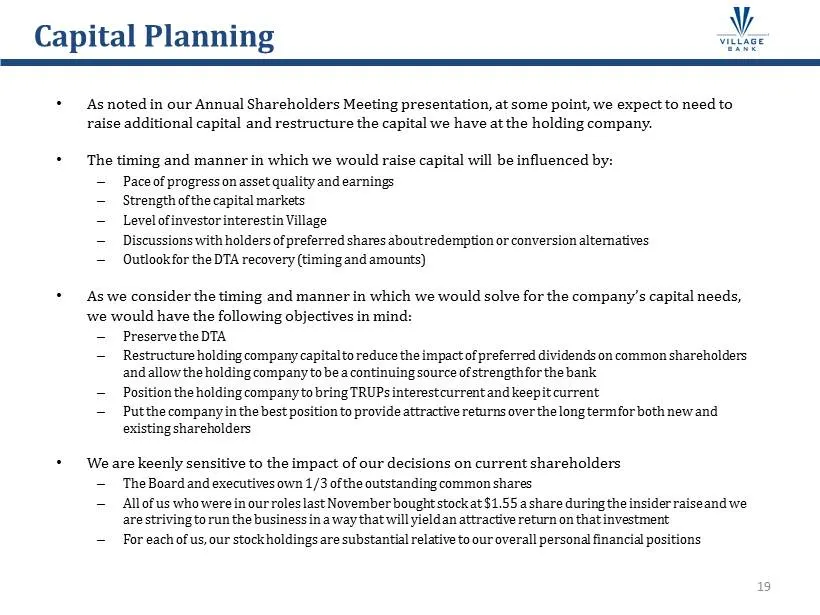
Slide 19: Capital Needs and Restructuring
• As noted in our Annual Shareholders Meeting presentation, at some point, we expect to need to raise additional capital and restructure the capital we have at the holding company. • The timing and manner in which we would raise capital will be influenced by: – Pace of progress on asset quality and
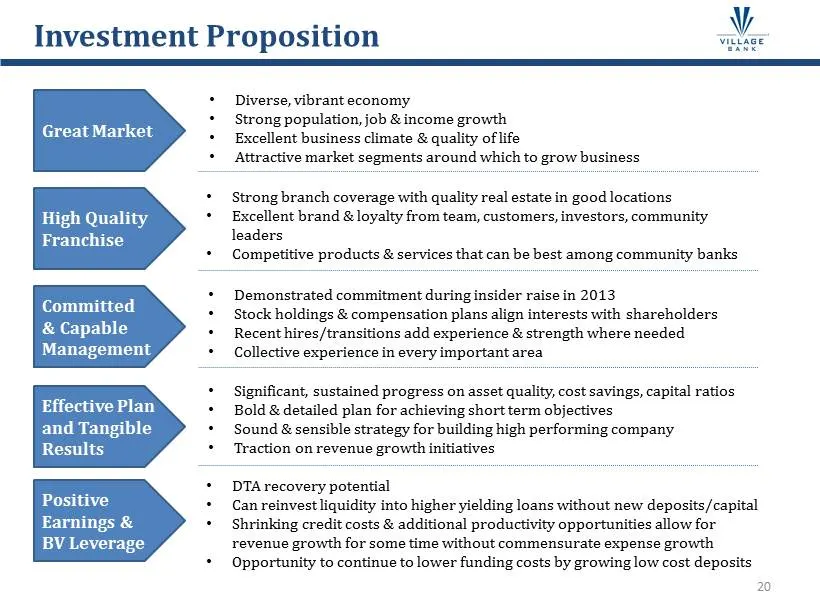
Slide 20: Investment Proposition
Great Market • Strong branch coverage with quality real estate in good locations • Excellent brand & loyalty from team, customers, investors, community leaders • Competitive products & services that can be best among community banks • Demonstrated commitment during insider raise in 2013 • Stock hold
Slide 21: Additional Information
Additional Information 21
Slide 22: Securities Portfolio Information
Securities Portfolio Information 22 • At 6/30/14, the investment portfolio totaled $106.3 million. – $57.5 million in securities – $48.8 million in Federal funds sold and bank balances • The securities portfolio is comprised fully of debt securities. – $7.6 million in US Treasuries – $36.1 million i
Slide 23: Interest Rate Risk Management
Interest Rate Risk Management • Modelling & Analysis – Have been working with SunTrust Robinson Humphrey since late 2013 on portfolio modelling and analysis – Based on our work with STRH, we believe that our interest rate margin sensitivity is in line with community bank peers – During the recession
Slide 24: Mortgage Banking
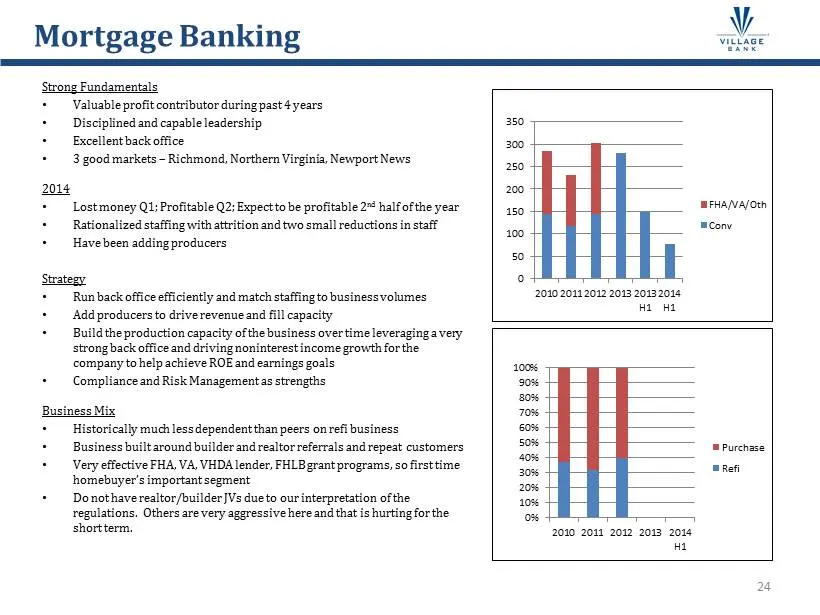
Mortgage Banking 24 0 50 100 150 200 250 300 350 2010 2011 2012 2013 2013 H1 2014 H1 FHA/VA/Oth Conv 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 2010 2011 2012 2013 2014 H1 Purchase Refi Strong Fundamentals • Valuable profit contributor during past 4 years • Disciplined and capable leadership • Exce
Source: SEC EDGAR · 8-K filed Aug 11, 2014
More decks from Village Bank and Trust Financial
 Shareholder Meeting (May 2024)23 slides · May 21, 2024
 Investor Presentation (January 2024)27 slides · Jan 26, 2024
 Shareholder Meeting (May 2023)25 slides · May 23, 2023
 Investor Presentation (September 2022)27 slides · Sep 19, 2022
 Shareholder Meeting (May 2022)19 slides · May 24, 2022
 Investor Presentation (January 2022)26 slides · Jan 28, 2022