Polypore International — Robert W. Baird & Co. 2011 Industrial Conference
24 slides from Polypore International's conference presentation, Nov 3, 2011
Slide 1: Robert W. Baird & Co. 2011 Industrial Conference
1 (NYSE Listed: PPO) Robert W. Baird & Co. 2011 Industrial Conference November 2011
Slide 2: Forward-looking statements
2 These materials include "forward-looking statements". In these materials, the words “Polypore International,” “Company,” “we,” “us” and “our” refer to Polypore International, Inc. together with its subsidiaries, unless the context indicates otherwise. All statements other than statements of histor
Slide 3: Polypore Overview
3 Polypore Overview ROBERT TOTH President & Chief Executive Officer
Slide 4: Polypore is a leading global high technology filtration company
4 Polypore is a leading global high technology filtration company specializing in microporous membranes.
Slide 5: Polypore is well positioned for long-term growth
5 Polypore is well positioned for long-term growth Leading market positions Proven innovation through a breadth of proprietary process and product technology Our markets have an attractive mix of growth and stability characteristics Global presence and customer base Polypore is well positioned to ca
Slide 6: Leading positions in our business segments
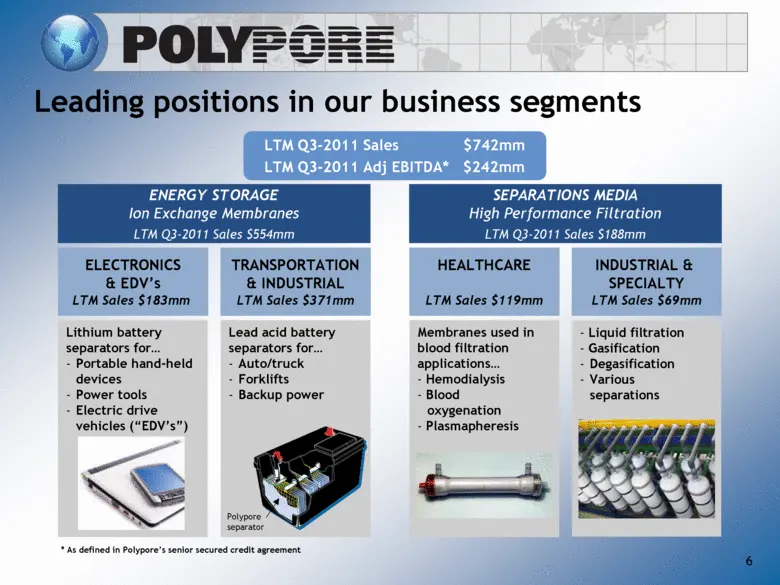
6 Leading positions in our business segments Lead acid battery separators for Auto/truck Forklifts Backup power Polypore separator Lithium battery separators for Portable hand-held devices Power tools Electric drive vehicles (“EDV’s”) Membranes used in blood filtration applications Hemodialysis Bloo
Slide 7: Differentiation in high performance filtration depends on membrane technology
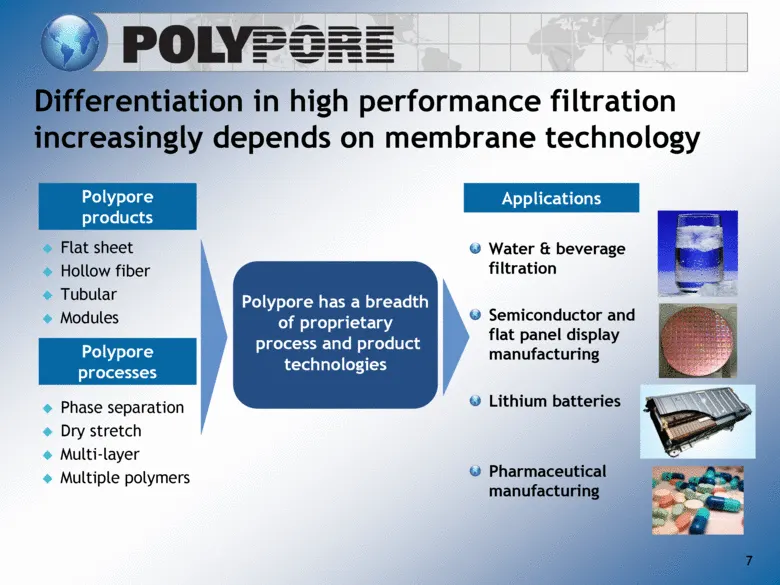
7 Differentiation in high performance filtration increasingly depends on membrane technology Polypore products Flat sheet Hollow fiber Tubular Modules Phase separation Dry stretch Multi-layer Multiple polymers Water & beverage filtration Semiconductor and flat panel display manufacturing Lithium bat
Slide 8: High growth market with significant upside potential
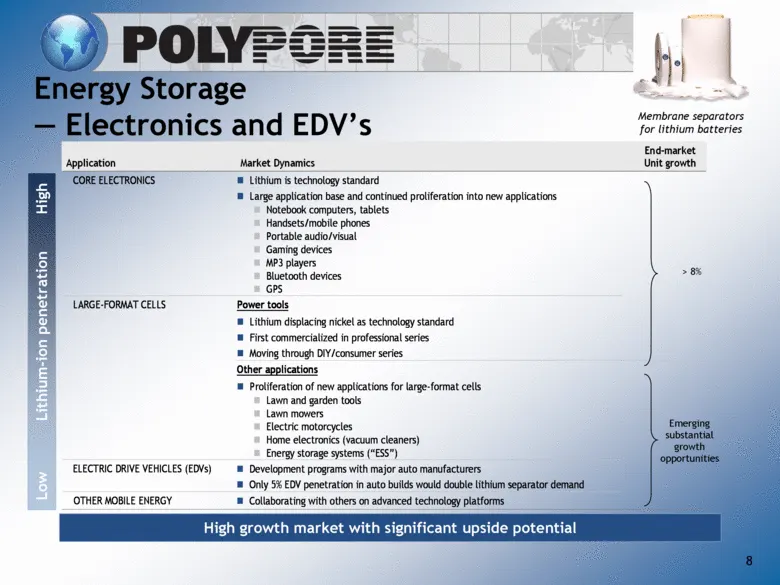
8 High growth market with significant upside potential Energy Storage — Electronics and EDV’s Membrane separators for lithium batteries Emerging substantial growth opportunities Low Lithium-ion penetration High > 8% Application Market Dynamics End-market Unit growth CORE ELECTRONICS Lithium is techn
Slide 9: Emergence of lithium-ion technology in Electric Drive Vehicles
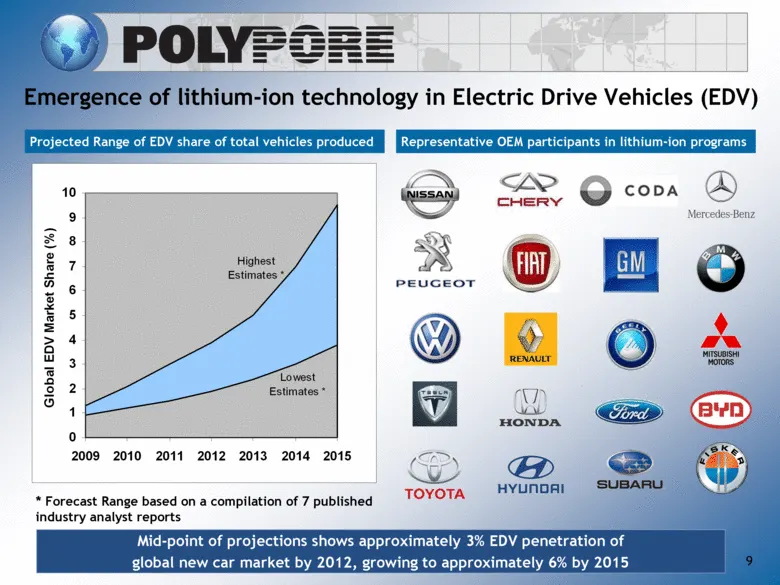
9 Projected Range of EDV share of total vehicles produced Representative OEM participants in lithium-ion programs Emergence of lithium-ion technology in Electric Drive Vehicles (EDV) Mid-point of projections shows approximately 3% EDV penetration of global new car market by 2012, growing to approxim
Slide 10: $334 million of Lithium Battery Separator Capacity Expansions
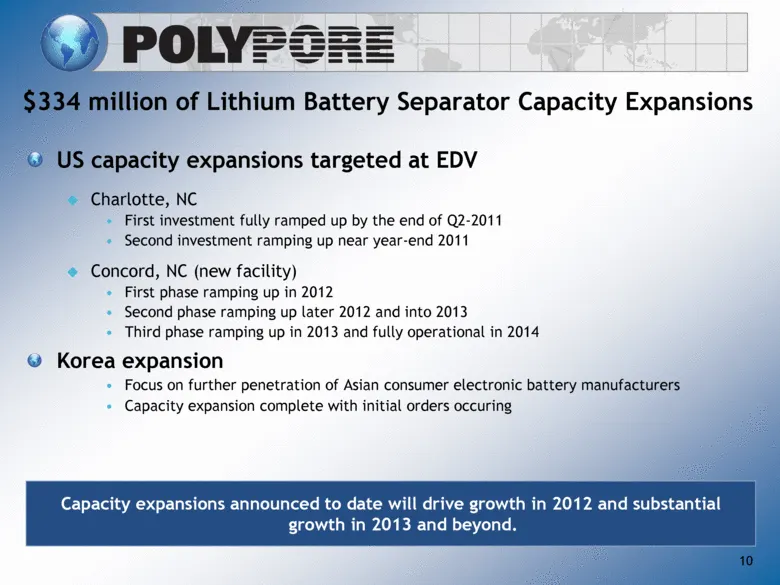
10 $334 million of Lithium Battery Separator Capacity Expansions US capacity expansions targeted at EDV Charlotte, NC First investment fully ramped up by the end of Q2-2011 Second investment ramping up near year-end 2011 Concord, NC (new facility) First phase ramping up in 2012 Second phase ramping
Slide 11: Energy Storage — Transportation & Industrial: lead-acid separators
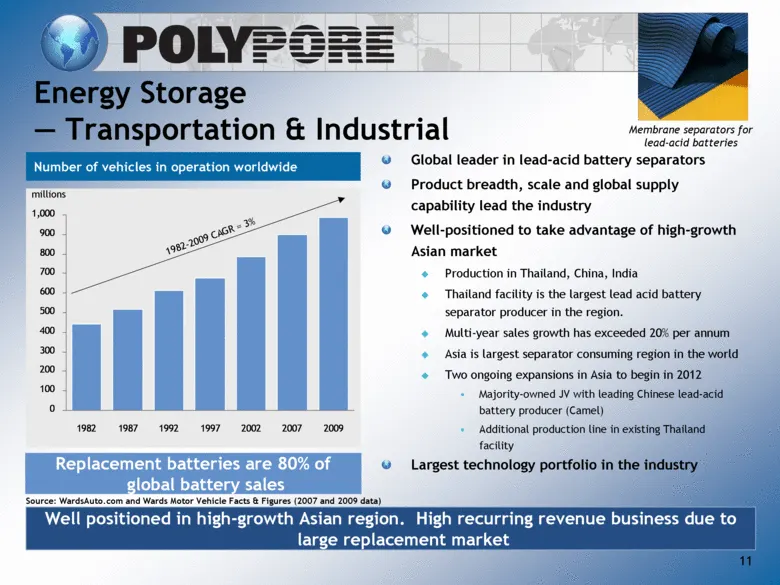
11 Replacement batteries are 80% of global battery sales Number of vehicles in operation worldwide Source: WardsAuto.com and Wards Motor Vehicle Facts & Figures (2007 and 2009 data) 1982-2009 CAGR = 3% Energy Storage — Transportation & Industrial Well positioned in high-growth Asian region. High rec
Slide 12: Separations Media — Healthcare
12 Separations Media — Healthcare Membranes for medical applications Blood Oxygenation >6% market growth Clinically demonstrated best-in-class PUREMA® membrane Unique position as leading independent producer with broad product line New PUREMA® capacity beginning to ramp up World’s leading supplier H
Slide 13: Separations Media — Industrial & Specialty Filtration
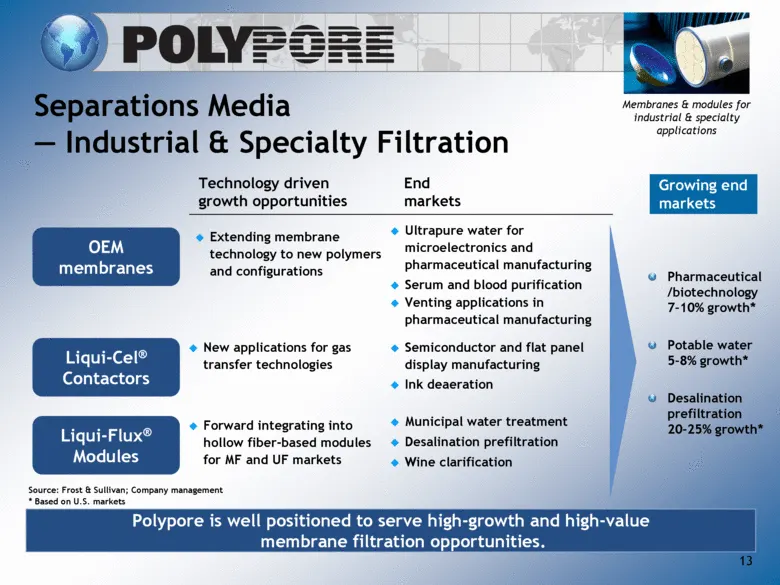
13 Separations Media — Industrial & Specialty Filtration Polypore is well positioned to serve high-growth and high-value membrane filtration opportunities. Membranes & modules for industrial & specialty applications OEM membranes Liqui-Flux® Modules Technology driven growth opportunities New applica
Slide 14: Polypore serves attractive end markets
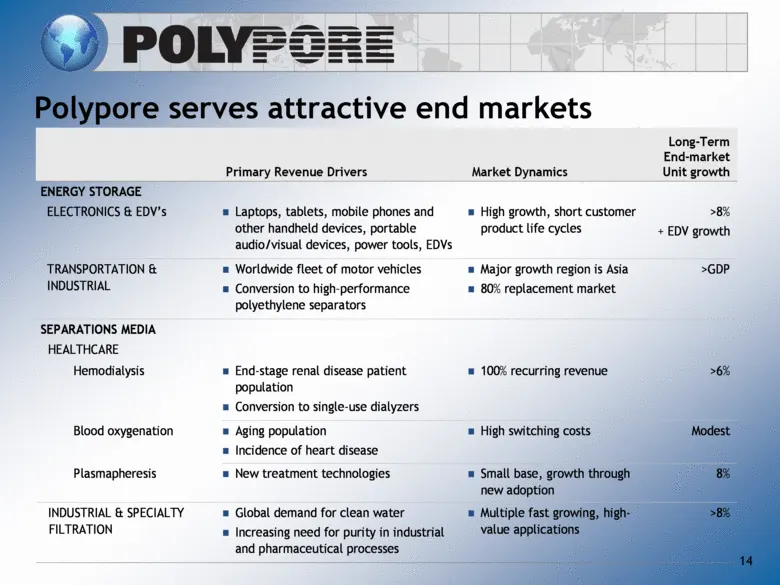
14 Polypore serves attractive end markets Primary Revenue Drivers Market Dynamics Long-Term End-market Unit growth ENERGY STORAGE ELECTRONICS & EDV’s Laptops, tablets, mobile phones and other handheld devices, portable audio/visual devices, power tools, EDVs High growth, short customer product life
Slide 15: Global infrastructure and customer base
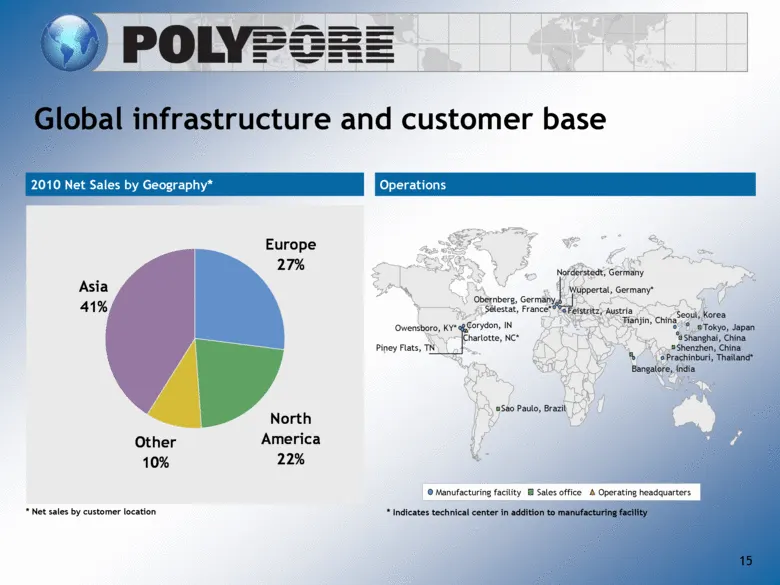
15 Global infrastructure and customer base 2010 Net Sales by Geography* Operations * Net sales by customer location * Indicates technical center in addition to manufacturing facility Piney Flats, TN Corydon, IN Charlotte, NC* Owensboro, KY* Sélestat, France* Wuppertal, Germany* Tokyo, Japan Shanghai
Slide 16: Key Takeaways and Strategic Direction
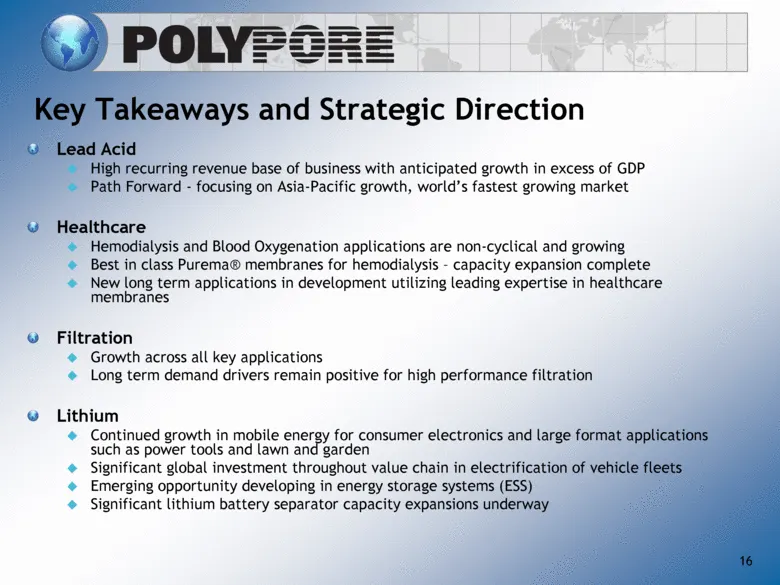
16 Key Takeaways and Strategic Direction Lead Acid High recurring revenue base of business with anticipated growth in excess of GDP Path Forward - focusing on Asia-Pacific growth, world’s fastest growing market Healthcare Hemodialysis and Blood Oxygenation applications are non-cyclical and growing B
Slide 17: Financials
17 Financials LYNN AMOS Chief Financial Officer
Slide 18: Revenue and Adjusted EBITDA
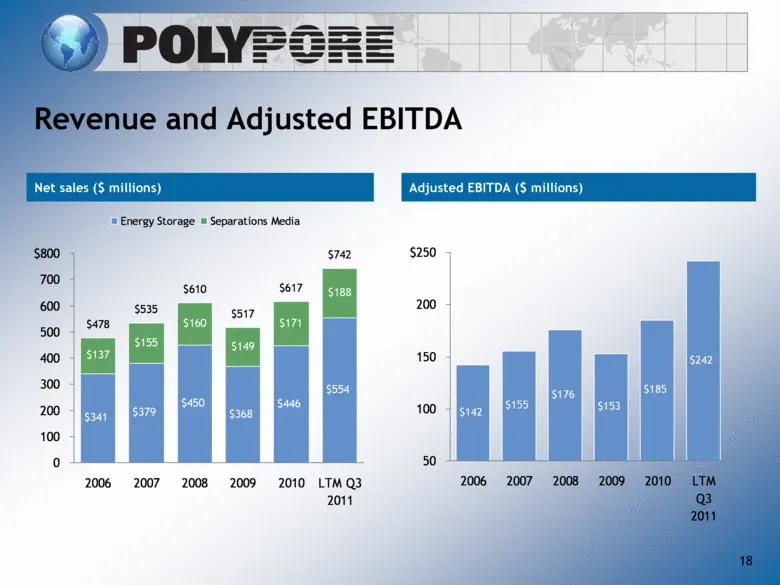
18 Revenue and Adjusted EBITDA Adjusted EBITDA ($ millions) Net sales ($ millions) $341 $379 $450 $368 $446 $554 $137 $155 $160 $149 $171 $188 $478 $535 $610 $517 $617 $742 0 100 200 300 400 500 600 700 $800 2006 2007 2008 2009 2010 LTM Q3 2011 Energy Storage Separations Media $142 $155 $176 $153 $1
Slide 19: Capital Structure in Place to Support Growth
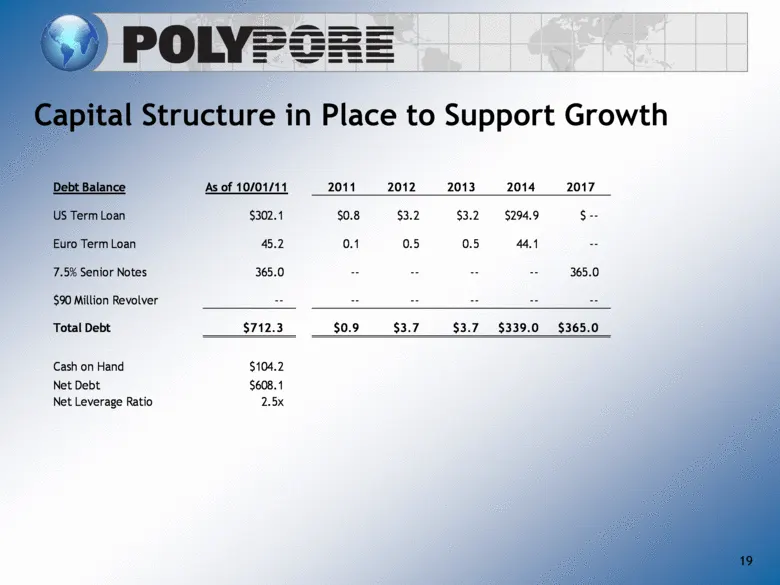
19 Capital Structure in Place to Support Growth Debt Balance As of 10/01/11 2011 2012 2013 2014 2017 US Term Loan $302.1 $0.8 $3.2 $3.2 $294.9 $ -- Euro Term Loan 45.2 0.1 0.5 0.5 44.1 -- 7.5% Senior Notes 365.0 -- -- -- -- 365.0 $90 Million Revolver -- -- -- -- -- -- Total Debt $712.3 $0.9 $3.7 $3.
Slide 20: Cash & Liquidity Summary
20 Cash & Liquidity Summary Strengthened capital structure and increased liquidity over the last 4 years Paid down $75 million and refinanced remaining 8.75% senior subordinated notes by issuing $365 million of new 7.5% senior notes in November 2010 Total net leverage improved from 5x at year-end 20
Slide 21: Financial Takeaways
21 Financial Takeaways Growth company driven by secular trends High recurring revenue core businesses Step change growth opportunity with electrification of vehicles High value application space Strong margin and cash generation to fund growth Leading market positions and technology Global presence
Slide 22: Appendix
22 APPENDIX
Slide 23: Non-GAAP Supplemental Information
23 Non-GAAP Supplemental Information Adjusted EBITDA is a non-GAAP financial measure presented herein as a supplemental disclosure to net income and reported results. Adjusted EBITDA is defined in our credit agreement and represents earnings before interest, taxes, depreciation and amortization and
Slide 24: Appendix A Adjusted EBITDA
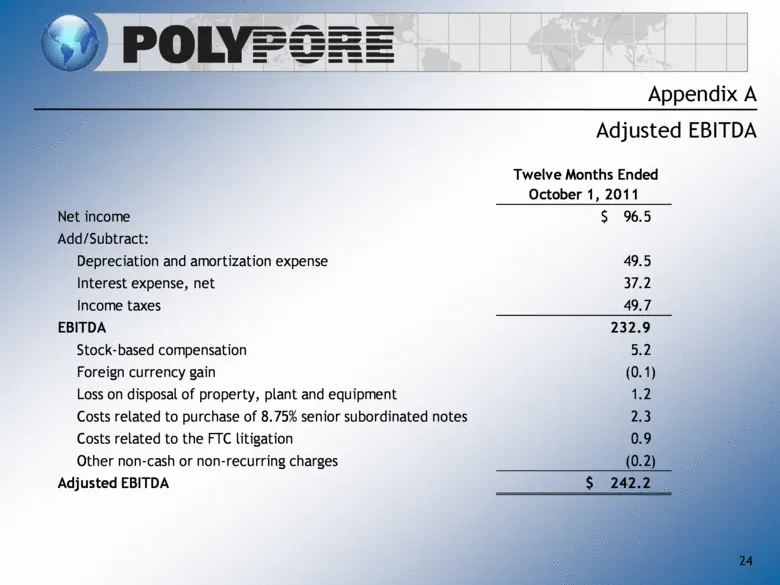
24 Appendix A Adjusted EBITDA Twelve Months Ended October 1, 2011 Net income $ 96.5 Add/Subtract: Depreciation and amortization expense 49.5 Interest expense, net 37.2 Income taxes 49.7 EBITDA 232.9 Stock-based compensation 5.2 Foreign currency gain (0.1) Loss on disposal of property, plant and equi
Source: SEC EDGAR · 8-K filed Nov 3, 2011
More decks from Polypore International Inc
 Q2 2015 Earnings Presentation10 slides · Aug 13, 2015
 Q1 2015 Earnings Presentation8 slides · May 8, 2015
 Q4 2014 Earnings Presentation10 slides · Mar 4, 2015
 Merger or Acquisition (February 2015)20 slides · Feb 23, 2015
 Investor Presentation (November 2014)16 slides · Nov 6, 2014
 Q3 2014 Earnings Presentation10 slides · Nov 5, 2014